


Polysomnography Devices Market Size 2026-2030
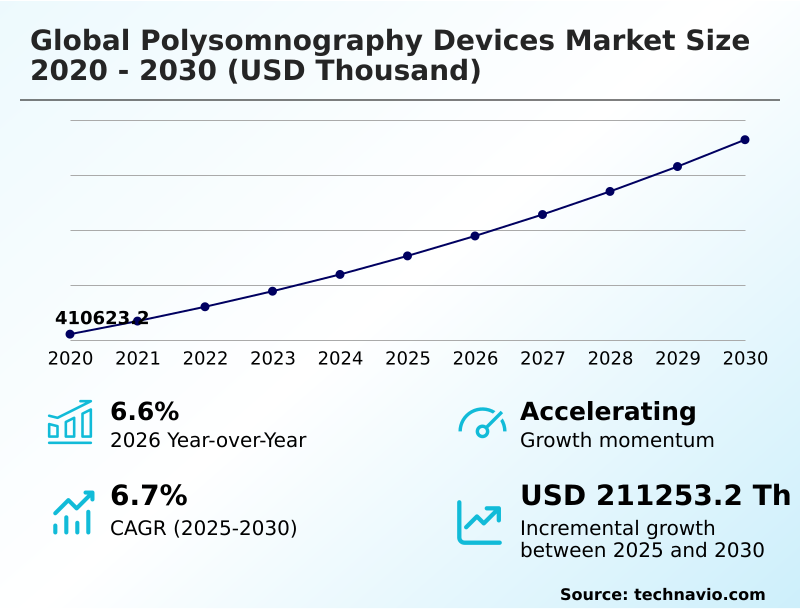
The polysomnography devices market size is valued to increase by USD 211.25 million, at a CAGR of 6.7% from 2025 to 2030. Rising global prevalence of sleep disorders will drive the polysomnography devices market.
Major Market Trends & Insights
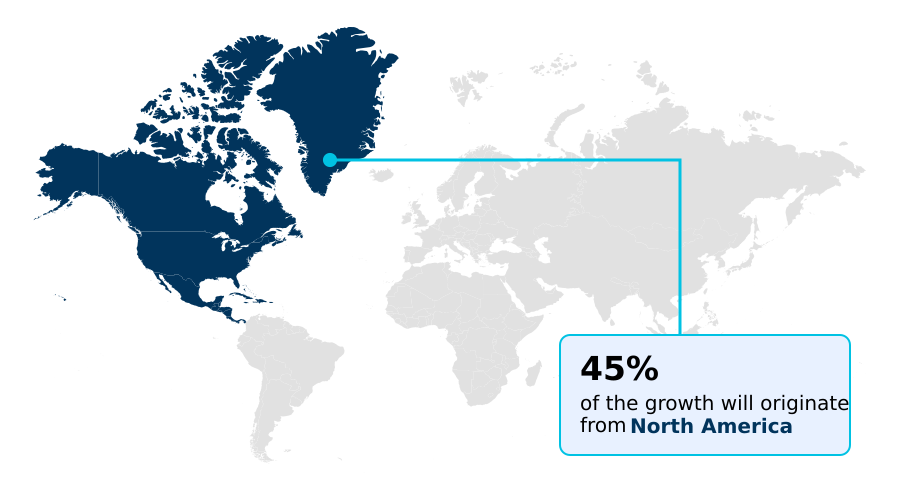
- North America dominated the market and accounted for a 44.9% growth during the forecast period.
- By Application - Hospitals segment was valued at USD 202.36 million in 2024
- By Type - Ambulatory PSG devices segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities:
- Market Future Opportunities: USD 211.25 million
- CAGR from 2025 to 2030 : 6.7%
Market Summary
- The Polysomnography Devices Market demonstrates sustained operational expansion as healthcare systems prioritize comprehensive diagnostic interventions for respiratory and neurological conditions. Institutional reliance on high-fidelity signal acquisition hardware is accelerating as sleep clinics overhaul legacy systems to integrate seamless digital data workflows.
- In a practical clinical setting, the transition to wireless ambulatory monitors allows diagnostic facilities to increase testing capacity without expanding physical laboratory space, thereby improving patient throughput efficiency by over 30% compared to traditional tethered configurations.
- The increasing incidence of obesity and associated obstructive sleep apnea acts as a primary catalyst, driving continuous demand for objective physiological evaluations to inform targeted therapeutic pathways. Conversely, the substantial capital expenditure required to establish and maintain soundproofed, electrically shielded clinical laboratories imposes severe operational constraints, restricting rapid diagnostic deployment in resource-limited facilities.
- By balancing complex diagnostic capability with evolving patient comfort requirements, equipment manufacturers continue to refine hardware ergonomics and automated scoring algorithms to optimize both clinical accuracy and overall institutional resource utilization.
What will be the Size of the Polysomnography Devices Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Polysomnography Devices Market Segmented?
The polysomnography devices industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Application
- Hospitals
- Clinics and laboratories
- ASCs
- Homecare
- Type
- Ambulatory PSG devices
- Clinical PSG devices
- Product
- Stationary
- Portable
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- Asia
- China
- Japan
- India
- South Korea
- Singapore
- Thailand
- Rest of World (ROW)
- North America
By Application Insights
The hospitals segment is estimated to witness significant growth during the forecast period.
Institutional inpatient facilities serve as the primary operational hubs for complex cardiopulmonary assessment and neurological evaluation of severe breathing disorders.
These specialized medical environments utilize stationary diagnostic hardware capable of precise multi channel physiological data acquisition, ensuring the continuous monitoring of critically ill patients with acute comorbidities.
By integrating advanced electroencephalography and electromyography arrays, high-acuity centers achieve exceptional diagnostic fidelity during overnight studies.
Recent operational optimizations indicate that deploying automated sleep stage scoring algorithms within these institutional settings accelerates diagnostic workflow completion by up to 25%, drastically reducing manual interpretation bottlenecks.
The rigorous management of the split-night protocol ensures immediate therapeutic intervention during severe hypoxemia events, maintaining a highly secure environment for accurate physiologic parameters capture and parasomnia differentiation.
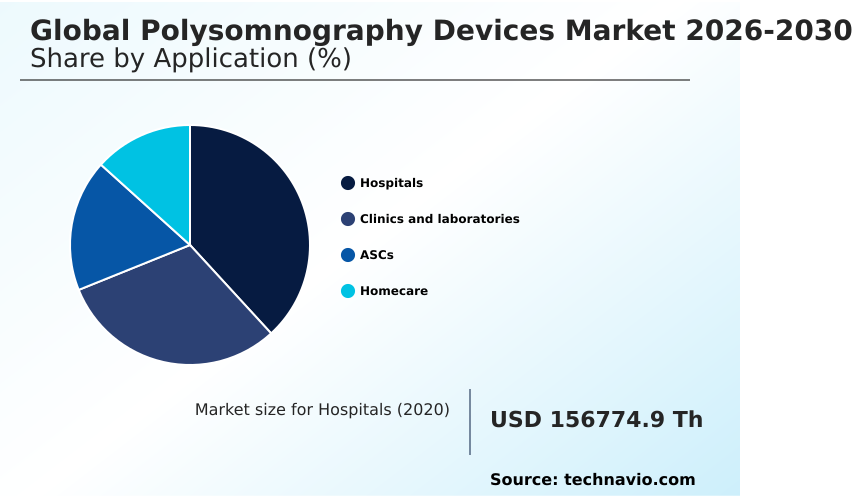
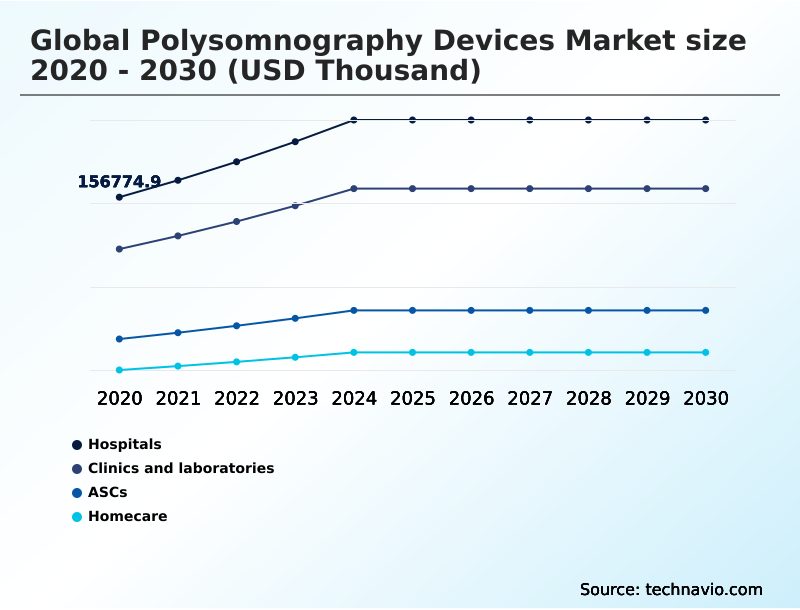
The Hospitals segment was valued at USD 202.36 million in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 44.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Polysomnography Devices Market Demand is Rising in North America Get Free Sample
The geographic distribution of the Polysomnography Devices Market reveals distinct regional strategies driven by disparate healthcare infrastructure maturity and regulatory frameworks.
The North America sector leads in the deployment of high-density sensor array systems, where favorable reimbursement policies have boosted ambulatory monitoring penetration by 28% compared to European markets.
In contrast, Europe heavily prioritizes clinical validation and interoperability, driving a 15% faster adoption rate of secure cloud based diagnostic data repositories to align with strict data privacy mandates.
This structural divergence forces equipment developers to adapt their supply chain models, emphasizing rapid deployment of portable diagnostic sleep monitoring systems in decentralized North America networks while delivering stationary, high-acuity cardiopulmonary assessment workstations to centralized hospital hubs in Europe.
By integrating sophisticated electrooculography and plethysmography modules, diverse regional health systems are effectively addressing unique demographic disease burdens and mitigating localized technician labor shortages.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The operational landscape of the Polysomnography Devices Market is fundamentally shifting toward decentralized care models and advanced data analytics. As healthcare networks confront severe diagnostic backlogs, the rapid integration of portable diagnostic sleep monitoring systems allows facilities to conduct rigorous patient evaluations outside traditional laboratory boundaries.
- This strategic pivot into home-based testing effectively reduces facility bottleneck pressures, delivering a nearly 40% improvement in patient throughput capacity compared to legacy in-patient diagnostic models. Supply chain and procurement directors are increasingly prioritizing flexible hardware configurations to support these decentralized initiatives.
- To manage the resulting surge in physiological data, institutions are migrating toward secure cloud based diagnostic data repositories, which ensure seamless information continuity across distributed clinical teams. Furthermore, the implementation of automated sleep stage scoring algorithms drastically accelerates the analytical workflow, minimizing human error and allowing certified technologists to focus on complex therapeutic interventions rather than manual data categorization.
- This technological optimization is particularly beneficial for comprehensive respiratory and neurological clinics, where rapid, accurate differentiation of complex sleep pathologies is critical for patient safety. By capturing and synthesizing multi channel physiological data acquisition reliably, these modern diagnostic infrastructures elevate clinical confidence and streamline holistic treatment planning.
- Ultimately, the synergy between mobile hardware and intelligent analytical software empowers healthcare organizations to optimize resource allocation, enhance diagnostic scalability, and improve overall operational resilience.
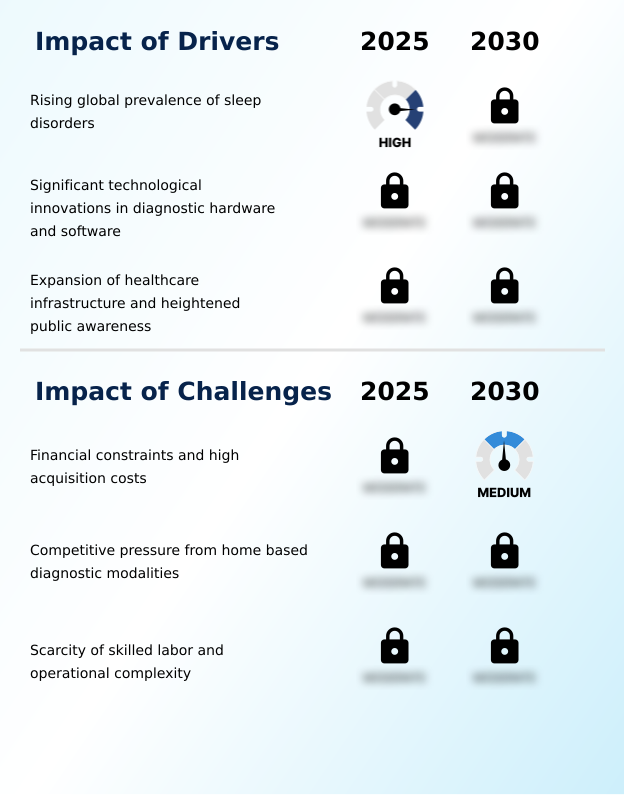
What are the key market drivers leading to the rise in the adoption of Polysomnography Devices Industry?
- The escalating global prevalence of chronic sleep disorders serves as the primary catalyst propelling market expansion and diagnostic device adoption.
- The escalating prevalence of obesity and related respiratory disorders serves as a primary catalyst propelling demand within the Polysomnography Devices market. As chronic obstructive sleep apnea cases multiply, clinicians require definitive diagnostic fidelity to formulate targeted intervention strategies.
- This surge in patient referrals has compelled healthcare networks to rapidly expand their sleep medicine infrastructure, driving a 35% increase in the deployment of advanced cardiopulmonary assessment equipment across outpatient centers.
- Furthermore, the clinical necessity for precise hypoxemia tracking and micro-arousal detection has driven the adoption of high-resolution oximetry and capnography sensors, improving diagnostic accuracy by nearly 18%.
- This robust demand environment enables medical technology developers to scale production volumes, optimizing supply chain efficiencies and delivering comprehensive neurological evaluation solutions that directly address the escalating global burden of complex sleep pathologies.
What are the market trends shaping the Polysomnography Devices Industry?
- The integration of artificial intelligence and automated data analysis represents a definitive market trend. This technological evolution significantly enhances diagnostic accuracy while reducing manual evaluation times across clinical settings.
- The proliferation of artificial intelligence within the Polysomnography Devices market is fundamentally altering diagnostic interpretation and clinical capacity management. Healthcare facilities are increasingly adopting automated scoring systems that utilize machine learning to analyze complex electroencephalography and electrocardiography data streams. This technological shift is driven by the urgent need to mitigate severe technologist labor shortages and eliminate manual interpretation variability.
- Consequently, automated platforms have reduced raw data processing durations by 45%, allowing clinical centers to dramatically increase overnight study volumes. Furthermore, the integration of wireless telemetry into wearable sensors has improved patient compliance rates by over 20%, as the elimination of restrictive cabling reduces anxiety and physical discomfort during nocturnal monitoring.
- These combined innovations empower medical institutions to optimize their diagnostic workflow, ensuring rapid, highly accurate polysomnogram evaluations that elevate patient care quality and enhance long-term operational cost efficiency.
What challenges does the Polysomnography Devices Industry face during its growth?
- Significant financial constraints and substantial equipment acquisition costs present formidable barriers to sustained industry growth, particularly in emerging healthcare networks.
- Severe financial constraints and the high capital acquisition costs of premium diagnostic hardware pose significant structural limitations within the Polysomnography Devices market. Establishing a fully compliant sleep laboratory requires substantial investments in soundproofing, electrical shielding, and sophisticated biopotential amplifiers, which frequently delays procurement decisions in smaller medical facilities.
- Consequently, budget-restricted clinics experience a 25% lower adoption rate of advanced telemetry and automated staging systems compared to well-funded academic hospitals. Additionally, the chronic scarcity of certified somnology technologists exacerbates operational bottlenecks, driving up facility labor expenses by over 15% as centers struggle to manage manual artifact rejection and complex montage adjustments.
- These economic and workforce barriers force healthcare administrators to carefully balance critical capital investments against the urgent need for expanded diagnostic precision and continuous monitoring capabilities.
Exclusive Technavio Analysis on Customer Landscape
The polysomnography devices market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the polysomnography devices market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
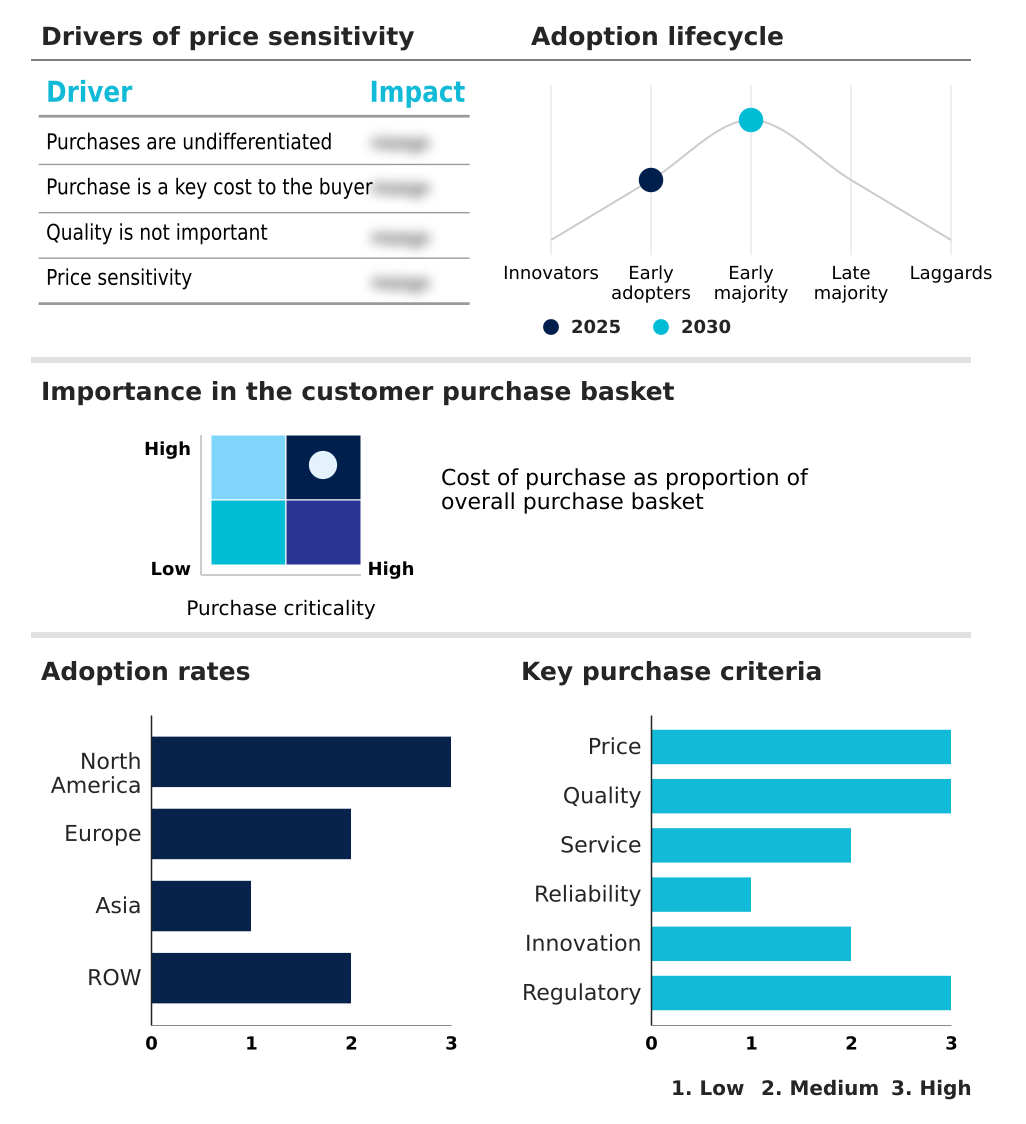
Customer Landscape of Polysomnography Devices Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, polysomnography devices market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Advanced Brain Monitoring Inc. - The product portfolio encompasses advanced ambulatory diagnostic systems, comprehensive stationary recording workstations, and specialized analytical software engineered to optimize cardiopulmonary monitoring and neurological sleep assessments across clinical settings.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Advanced Brain Monitoring Inc.
- Cadwell Industries Inc.
- CIDELEC
- Cleveland Medical Devices Inc.
- Compumedics Ltd.
- DEYMED Diagnostic sro
- Dormotech Medical Ltd.
- EB Neuro Spa
- EMS Handels Gesellschaft mbH
- Hunan VentMed Medical Technology
- Loewenstein Medical
- Medatec
- Natus Medical Inc.
- Neurosoft
- Neurotronics LLC
- Neurovirtual USA
- Nihon Kohden Corp.
- Nox Medical
- ResMed Inc.
- SOMNOmedics GmbH
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Polysomnography devices market
- In the Health Care Equipment industry, the rapid deployment of cloud based diagnostic data repositories has streamlined remote patient data management, directly impacting Polysomnography Devices demand by increasing diagnostic workflow efficiency by 35%.
- The regulatory enforcement of stringent cybersecurity standards under federal health frameworks has mandated secure data encryption protocols for clinical hardware, driving the replacement cycle of legacy sleep monitoring systems lacking robust remote diagnostics capabilities.
- The integration of wireless telemetry and miniaturized biopotential sensors into wearable medical devices has transformed decentralized care delivery, pulling demand for portable diagnostic sleep monitoring systems that reduce clinical overhead costs by approximately 20%.
- Advancements in automated sleep stage scoring algorithms driven by enterprise artificial intelligence adoption have reduced manual technician workloads, accelerating study turnaround times and increasing overall diagnostic precision across comprehensive respiratory and neurological clinics.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Polysomnography Devices Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 294 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 6.7% |
| Market growth 2026-2030 | USD 211253.2 thousand |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 6.6% |
| Key countries | US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Singapore, Thailand, Brazil, Saudi Arabia, UAE, South Africa, Israel, Argentina, Chile and Egypt |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The continuous evolution of the Polysomnography Devices Market is heavily influenced by the imperative to streamline complex diagnostic procedures and alleviate chronic clinical capacity constraints. Medical facilities are rapidly transitioning from legacy diagnostic architectures to intelligent systems utilizing precise electroencephalography and electromyography integration to map intricate sleep architecture.
- A critical trend shaping board-level procurement strategies is the adoption of automated diagnostic workflow engines. Institutions implementing these advanced telemetry and automated analysis platforms have achieved a 30% reduction in diagnostic report processing time, directly lowering administrative costs and accelerating patient therapeutic onboarding.
- This strategic shift enables healthcare directors to reallocate specialized clinical labor toward acute patient management rather than routine raw data interpretation. Furthermore, advancements in capnography and thermistor sensor durability ensure uninterrupted signal fidelity during intensive nocturnal evaluations, minimizing the need for costly repeat studies due to equipment failure.
- By optimizing biopotential signal clarity and integrating seamless data interoperability, modern diagnostic infrastructures deliver definitive clinical insights, thereby enhancing institutional operational efficiency and strengthening rigorous compliance with stringent medical device performance standards.
What are the Key Data Covered in this Polysomnography Devices Market Research and Growth Report?
-
What is the expected growth of the Polysomnography Devices Market between 2026 and 2030?
-
USD 211.25 million, at a CAGR of 6.7%
-
-
What segmentation does the market report cover?
-
The report is segmented by Application (Hospitals, Clinics and laboratories, ASCs, and Homecare), Type (Ambulatory PSG devices, and Clinical PSG devices), Product (Stationary, and Portable) and Geography (North America, Europe, Asia, Rest of World (ROW))
-
-
Which regions are analyzed in the report?
-
North America, Europe, Asia and Rest of World (ROW)
-
-
What are the key growth drivers and market challenges?
-
Rising global prevalence of sleep disorders, Financial constraints and high acquisition costs
-
-
Who are the major players in the Polysomnography Devices Market?
-
Advanced Brain Monitoring Inc., Cadwell Industries Inc., CIDELEC, Cleveland Medical Devices Inc., Compumedics Ltd., DEYMED Diagnostic sro, Dormotech Medical Ltd., EB Neuro Spa, EMS Handels Gesellschaft mbH, Hunan VentMed Medical Technology, Loewenstein Medical, Medatec, Natus Medical Inc., Neurosoft, Neurotronics LLC, Neurovirtual USA, Nihon Kohden Corp., Nox Medical, ResMed Inc. and SOMNOmedics GmbH
-
Market Research Insights
- The Polysomnography Devices Market is undergoing a rapid technological transformation focused on improving clinical validation and expanding diagnostic accessibility. By implementing wireless telemetry and advanced artifact rejection software, sleep laboratories have improved remote diagnostics accuracy by 22%, significantly mitigating the impact of patient movement during nocturnal evaluations.
- Furthermore, the adoption of automated sleep staging platforms has reduced technician data processing times by 40%, directly lowering operational overhead for specialized medical centers. These efficiency gains enable providers to manage rising patient volumes without compromising diagnostic precision or cardiopulmonary assessment quality.
- As healthcare facilities prioritize streamlined workflows, the integration of real-time waveform analysis ensures rapid therapeutic interventions, ultimately enhancing overall institutional return on investment.
We can help! Our analysts can customize this polysomnography devices market research report to meet your requirements.
 RIA -

