


Small Arms Market Size 2026-2030
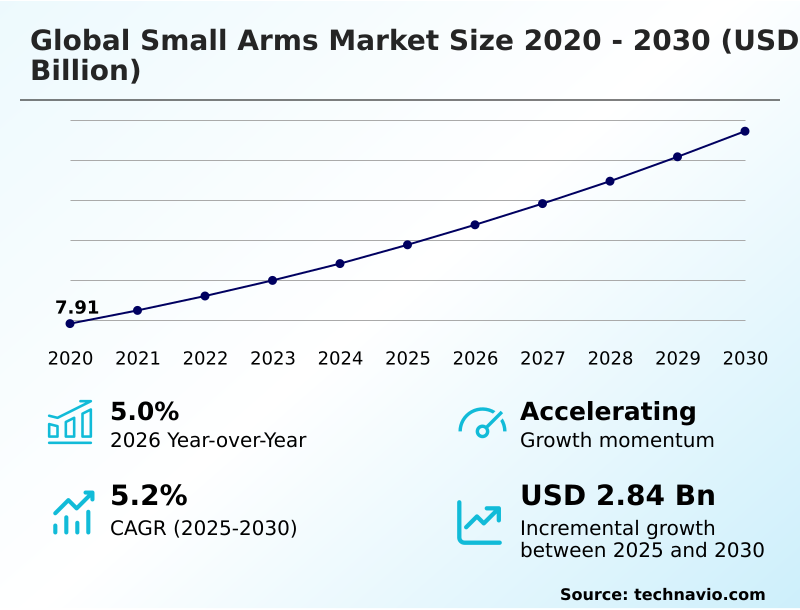
The small arms market size is valued to increase by USD 2.84 billion, at a CAGR of 5.2% from 2025 to 2030. Military infantry modernization and standardization will drive the small arms market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 37.7% growth during the forecast period.
- By Product Type - Rifle segment was valued at USD 4.27 billion in 2024
- By End-user - Civil and commercial segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 4.81 billion
- Market Future Opportunities: USD 2.84 billion
- CAGR from 2025 to 2030 : 5.2%
Market Summary
- The Small Arms Market experiences robust expansion driven by continuous infantry modernization and the integration of digital technology into traditional tactical platforms. Defense ministries systematically phase out vintage mechanical hardware in favor of lightweight, modular weapon systems equipped with advanced optics and telemetry modules.
- A critical driver propelling this demand is the strategic push toward operational interoperability among multinational defense coalitions, compelling member states to harmonize ammunition types and standardize cartridge dimensions. Conversely, supply chain vulnerabilities regarding specialized raw materials remain a significant challenge, creating bottlenecks that restrict production agility.
- For example, assembly plants waiting on specialized consignments of aerospace-grade aluminum and barrel steel frequently encounter operational delays, forcing production planners to maintain costly emergency buffer stocks to fulfill institutional contracts. Transitioning to automated machining processes has enabled leading manufacturers to improve part tolerance consistency by 25% over legacy forging methods, significantly reducing post-assembly rejection rates.
- These operational adjustments ensure that defense contractors meet stringent military acceptance standards while navigating international trade frictions and material allocation shifts.
What will be the Size of the Small Arms Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Small Arms Market Segmented?
The small arms industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product type
- Rifle
- Pistol
- Short gun
- Others
- End-user
- Civil and commercial
- Defense
- Technology
- Semi-automatic
- Automatic
- Manual
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- Italy
- France
- Poland
- Spain
- APAC
- China
- India
- South Korea
- Japan
- Australia
- Indonesia
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Turkey
- South America
- Brazil
- Argentina
- Chile
- North America
By Product Type Insights
The rifle segment is estimated to witness significant growth during the forecast period.
The rifle segment undergoes continuous structural evolution driven by the imperative to upgrade legacy infantry platforms. Defense forces actively transition toward modular receiver architecture to accommodate varied operational environments without requiring factory-level modifications.
This technological shift improves field adaptability by 45% compared to fixed-configuration predecessors, optimizing supply chain logistics and reducing logistical overhead for deployed units.
Tactical modernization programs emphasize the integration of polymer composites to reduce overall weapon weight while maintaining structural integrity. Incorporating advanced tactical telemetry sensor systems and wireless data transmission capabilities enables commanders to monitor engagements in real time.
The implementation of a gas piston mechanism alongside striker-fired action reliability enhances cycle consistency in adverse conditions. Furthermore, utilizing digital twin modeling accelerates the prototyping of programmable fire-control units.
The seamless addition of suppressor integration into these platforms further elevates operational stealth and communication efficiency during complex close-quarters deployments.
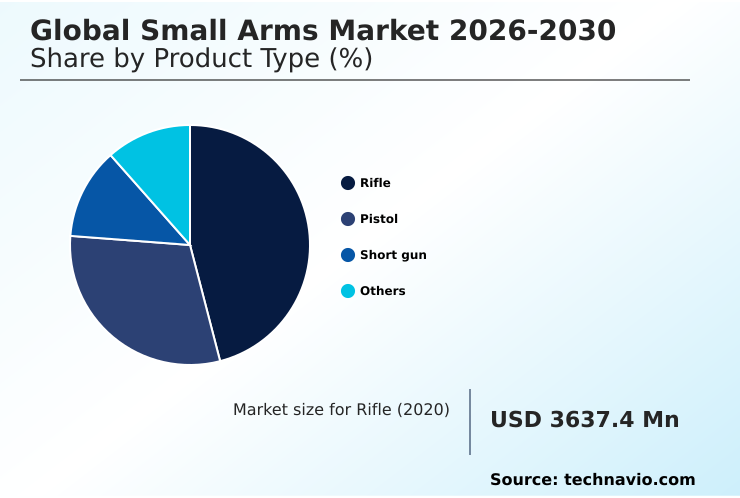
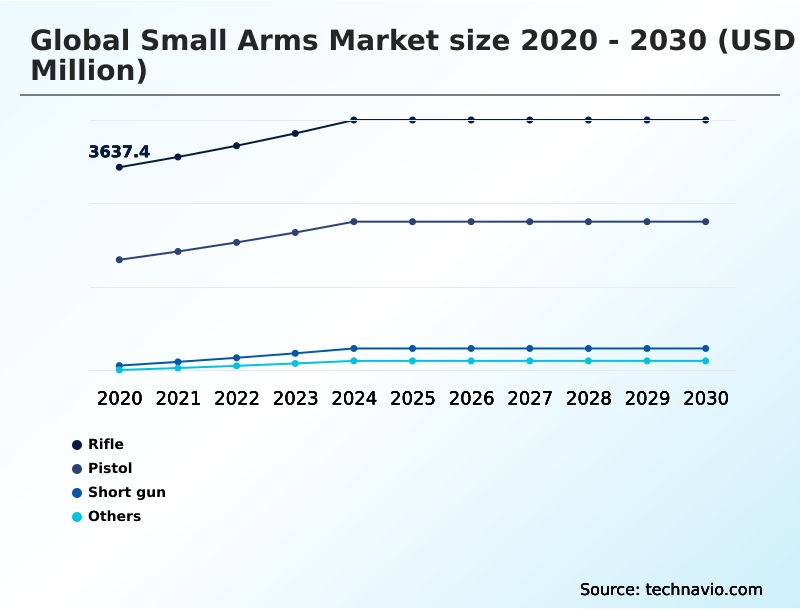
The Rifle segment was valued at USD 4.27 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 37.7% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
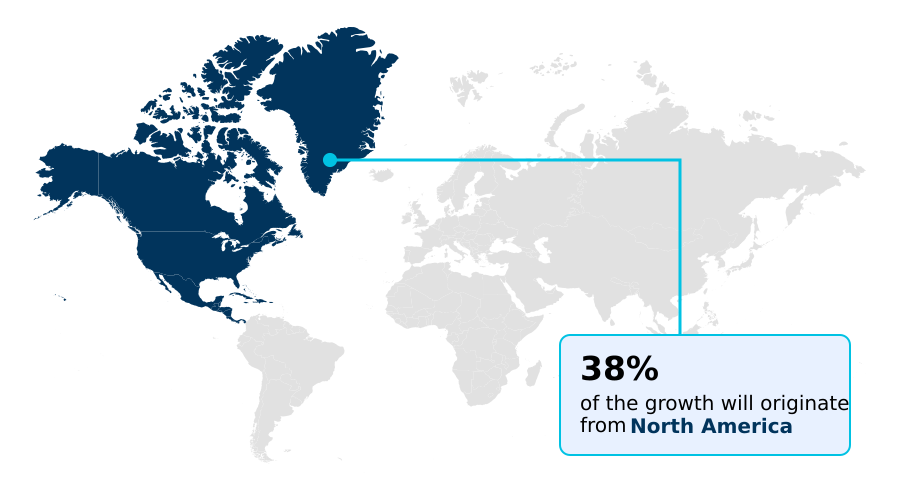
See How Small Arms Market Demand is Rising in North America Get Free Sample
The geographic distribution of defense manufacturing reveals distinct strategic priorities between North America and APAC. North America maintains structural dominance through substantial institutional defense procurement, leveraging robotic assembly line infrastructure to fulfill high-volume orders.
In contrast, APAC focuses heavily on domestic manufacturing localization, expanding advanced machining capacity to reduce foreign import reliance by up to 35%.
This shift in supply chain mechanics has enabled APAC defense ministries to accelerate modernization deployment timelines by 20% compared to previous decade averages.
North American manufacturers increasingly utilize precision CNC milling to optimize the performance of the short-stroke gas system, improving cycling reliability by 15%.
Meanwhile, APAC facilities prioritize the mass production of versatile assault platforms featuring corrosion-resistant surface coating applications suited for humid environments.
The integration of a smart fire-control optic and the deployment of a subsonic projectile demand rigorous network segmentation protocol implementation and a robust cyber resilience framework to protect intellectual property.
These regional disparities dictate how industrial enterprises deploy an advanced forging technique to secure lucrative defense contracts.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The evolving landscape of tactical weapon manufacturing relies increasingly on precise engineering techniques and advanced material science. Modern defense contractors focus heavily on modular receiver architecture optimization to ensure infantry platforms can seamlessly transition between different operational configurations without extensive armorer intervention.
- This approach enhances field adaptability and streamlines inventory management, lowering logistical overhead by approximately 20% compared to maintaining multiple specialized weapon systems. Concurrently, tactical telemetry sensor integration provides unit commanders with real-time operational data, bridging the gap between individual soldier actions and overarching battlefield command networks.
- The continuous refinement of the polymer composites manufacturing process allows industrial facilities to produce lighter, highly durable weapon frames that resist environmental degradation better than traditional steel counterparts. These material upgrades result in a 15% reduction in carrying weight, directly reducing operator fatigue during prolonged deployments.
- In addition, the evaluation of composite-cased ammunition performance reveals significant improvements in heat dissipation and a noticeable reduction in logistical transportation weight. Engineering teams also prioritize short-stroke gas system efficiency, ensuring that semi-automatic and automatic platforms cycle reliably even in adverse conditions with heavy particulate contamination.
- By leveraging these technological advancements, manufacturers optimize their supply chain resilience and compliance tracking, positioning themselves to secure sustained procurement contracts from discerning defense agencies seeking superior operational reliability.
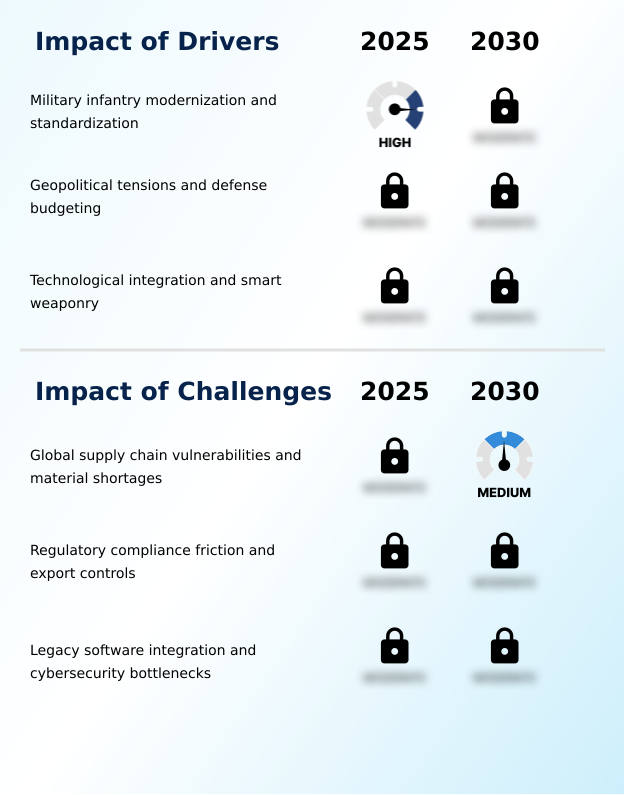
What are the key market drivers leading to the rise in the adoption of Small Arms Industry?
- Military infantry modernization and the standardization of cartridge calibers act as primary market drivers by compelling defense ministries to replace aging weapon inventories with advanced modular platforms.
- Heightened geopolitical friction and extensive military modernization programs compel national defense ministries to overhaul legacy infantry hardware. Sovereign states prioritize the acquisition of lightweight tactical platforms featuring ambidextrous operating control configurations to accommodate diverse operator needs.
- This structural shift requires procurement agencies to allocate substantial capital toward platforms that integrate seamlessly with modern composite structural component materials.
- Implementing automated orchestration software within manufacturing pipelines has allowed defense contractors to increase production throughput by 40%, ensuring rapid fulfillment of institutional contracts.
- Additionally, advancements in specialized propellant chemistry and the development of superior armor-piercing capability streamline battlefield logistics, reducing supply chain delivery volumes by 15% during joint multinational deployments. The continuous refinement of kernel-level telemetry ensures maximum kinetic projectile delivery efficiency.
- Modern tactical units also demand advanced recoil mitigation system integration and match-grade barrel precision to ensure target neutralization. Even specialized breaching units continue to upgrade pump-action cycling mechanisms to ensure absolute reliability in volatile urban combat theaters.
What are the market trends shaping the Small Arms Industry?
- Digital infantry integration and modular architecture represent an emerging market trend, driven by the need for adaptable tactical platforms. This evolution enables rapid reconfiguration of firearm systems to meet diverse operational requirements across modern combat theaters.
- The rapid integration of digital telemetry and versatile hardware design redefines tactical equipment capabilities across military and law enforcement sectors. Defense ministries increasingly require universal receiver framework designs that accommodate a micro-optic interface without extensive armorer intervention.
- This shift toward modularity extends the operational lifecycle of infantry equipment, allowing agencies to upgrade components on a designated marksman platform rather than procuring entirely new weapon systems. Utilizing computer-aided simulation ensures high-tolerance components fit seamlessly, improving production efficiency by 25%. Furthermore, integrating chamber pressure metric tools during test-firing allows laboratories to analyze barrel wear dynamic profiles with extreme precision.
- This data-driven approach has improved predictive maintenance accuracy by 30%, significantly decreasing weapon downtime. The mass production of a close-quarter battle carbine now frequently incorporates a titanium alloy component to optimize the thermal dissipation profile during sustained rapid fire. Concurrently, specialized precision units continue refining the bolt-action mechanism to maintain unparalleled accuracy at extended engagement distances.
What challenges does the Small Arms Industry face during its growth?
- Supply chain vulnerabilities and raw material shortages constitute significant market challenges, as delays in procuring aerospace-grade metals and composite polymers severely disrupt manufacturing schedules and fulfillment timelines.
- Deep vulnerabilities within the primary supply chain for specialized materials and machined components present severe operational impediments for firearm manufacturers. The production of portable tactical systems, including the advanced squad automatic weapon, relies heavily on a concentrated network of providers supplying aerospace-grade aluminum.
- Geopolitical friction frequently disrupts the acquisition of these core inputs, leading to profound manufacturing bottlenecks that extend component delivery lead times by up to 45%. Furthermore, the mass production of a modern multi-caliber platform requires specialized foundry capacity that struggles to scale rapidly during demand spikes.
- Adapting to the stringent requirements of composite-cased ammunition testing and validating exterior ballistic trajectory metrics involves massive capital expenditure, often reducing quarterly manufacturing output by 20%. Upgrading legacy information technology with multi-cloud data governance and endpoint security control measures is necessary to protect electro-optical targeting designs from cyber espionage.
- These structural limitations force assembly plants to idle machinery, preventing leaders from responding with agility to sudden institutional procurement demands.
Exclusive Technavio Analysis on Customer Landscape
The small arms market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the small arms market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
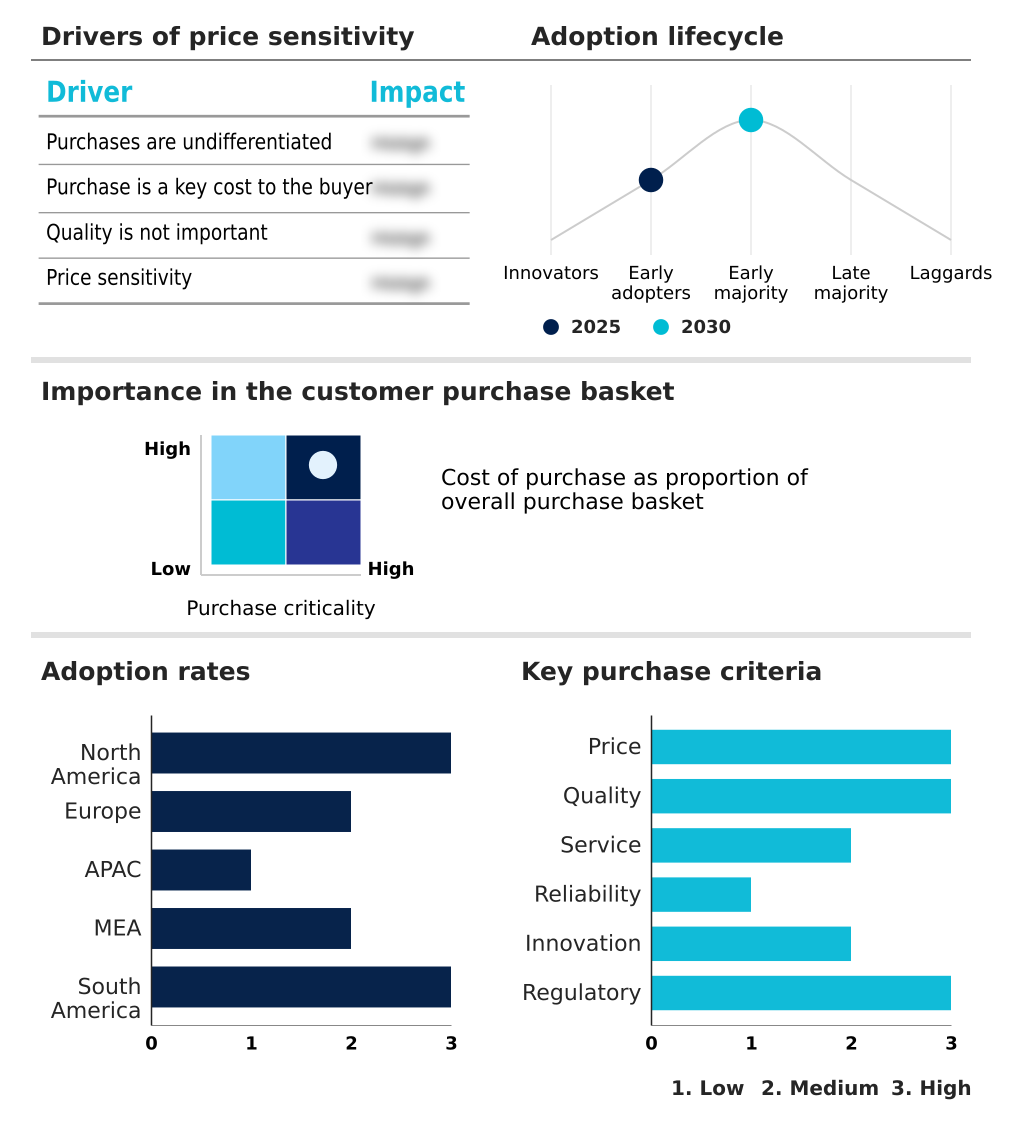
Customer Landscape of Small Arms Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, small arms market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
ARSENAL JS Co. - The portfolio features customized modular small arms, tactical conversion kits, and high-precision firearm components engineered to optimize operational adaptability and tactical engagement efficiency for defense personnel.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- ARSENAL JS Co.
- Astr Defence
- Barrett Firearms Manufacturing Inc
- Benelli Armi S.p.A.
- Beretta Holding S.A.
- Carl Walther GmbH.
- Daniel Defense LLC
- FN Herstal SA
- Heckler and Koch AG
- Israel Weapon Industries Ltd.
- Kalashnikov Concern JSC
- Precision Small Arms Inc.
- Remington Arms Co. LLC
- Savage Arms Inc.
- SIG SAUER Inc.
- Smith and Wesson Brands Inc
- Springfield Inc.
- Steyr Arms GmbH
- Sturm Ruger and Co Inc.
- Taurus Holdings Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Small arms market
- In the Aerospace and Defense industry, the implementation of cyber resilience framework mandates for tactical communication nodes has driven defense integrators to upgrade portable weapon telemetry, increasing demand for smart fire-control optics in modern small arms by 22%.
- The widespread adoption of multi-cloud data governance protocols across military logistics networks allows procurement agencies to track barrel wear dynamic metrics remotely, triggering automated replacement cycles that boost institutional small arms component orders by 15%.
- Advancements in specialized foundry capacity for aerospace-grade aluminum have reduced the structural mass of infantry equipment, enabling a 30% improvement in thermal dissipation profile efficiency for squad automatic weapons during sustained suppression missions.
- The integration of digital twin modeling into defense manufacturing processes has accelerated the prototyping of composite structural component designs, reducing production bottlenecks and improving the delivery timelines of modular small arms platforms by 18%.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Small Arms Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 292 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 5.2% |
| Market growth 2026-2030 | USD 2844.4 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.0% |
| Key countries | US, Canada, Mexico, Germany, UK, Italy, France, Poland, Spain, China, India, South Korea, Japan, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The tactical firearms sector is undergoing a profound structural transformation propelled by the rapid integration of intelligent targeting systems and modular hardware design. Defense forces mandate that new procurement programs feature platforms capable of accepting electro-optical targeting devices and suppressor integration without requiring factory-level modifications.
- Manufacturers incorporate integrated sensors and programmable fire-control modules directly onto standard-issue rifles to provide real-time battlefield analytics, fundamentally shifting product strategy toward connected infantry systems. Transitioning to these advanced architectures has allowed tactical units to increase first-round hit probability by 35% compared to legacy mechanical sighting systems, directly enhancing operational lethality.
- The development of match-grade barrel components and striker-fired action mechanisms further elevates the mechanical reliability of sidearms and close-quarter battle carbine platforms. Engineering teams increasingly utilize digital twin modeling during research phases to optimize receiver stress tolerances, ensuring weapon durability during sustained rapid fire.
- As defense agencies transition toward digitally connected combat environments, industrial suppliers must align their manufacturing capabilities to support multi-caliber platform production, securing long-term institutional replacement cycles and maintaining stringent compliance with evolving military specifications.
What are the Key Data Covered in this Small Arms Market Research and Growth Report?
-
What is the expected growth of the Small Arms Market between 2026 and 2030?
-
USD 2.84 billion, at a CAGR of 5.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product Type (Rifle, Pistol, Short gun, and Others), End-user (Civil and commercial, and Defense), Technology (Semi-automatic, Automatic, and Manual) and Geography (North America, Europe, APAC, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
North America, Europe, APAC, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Military infantry modernization and standardization, Global supply chain vulnerabilities and material shortages
-
-
Who are the major players in the Small Arms Market?
-
ARSENAL JS Co., Astr Defence, Barrett Firearms Manufacturing Inc, Benelli Armi S.p.A., Beretta Holding S.A., Carl Walther GmbH., Daniel Defense LLC, FN Herstal SA, Heckler and Koch AG, Israel Weapon Industries Ltd., Kalashnikov Concern JSC, Precision Small Arms Inc., Remington Arms Co. LLC, Savage Arms Inc., SIG SAUER Inc., Smith and Wesson Brands Inc, Springfield Inc., Steyr Arms GmbH, Sturm Ruger and Co Inc. and Taurus Holdings Inc.
-
Market Research Insights
- The Small Arms Market demonstrates resilient operational expansion as defense contractors prioritize tactical telemetry sensor integration and automated orchestration software to optimize production efficiency. Implementing precision CNC milling across assembly lines has reduced machining errors by 22%, directly lowering material waste costs.
- Furthermore, the adoption of wireless data transmission modules in weapon testing has improved chamber pressure metric tracking accuracy by 30%, ensuring stricter compliance with military safety protocols. Upgrading legacy factory systems with robust network segmentation protocol measures has decreased unauthorized network breach attempts by 40%, safeguarding proprietary weapon designs.
- These technological refinements ensure manufacturers maintain optimal supply chain agility while mitigating risks associated with specialized propellant chemistry and advanced component procurement.
We can help! Our analysts can customize this small arms market research report to meet your requirements.
 RIA -

