


Stem Cell Manufacturing Market Size 2026-2030
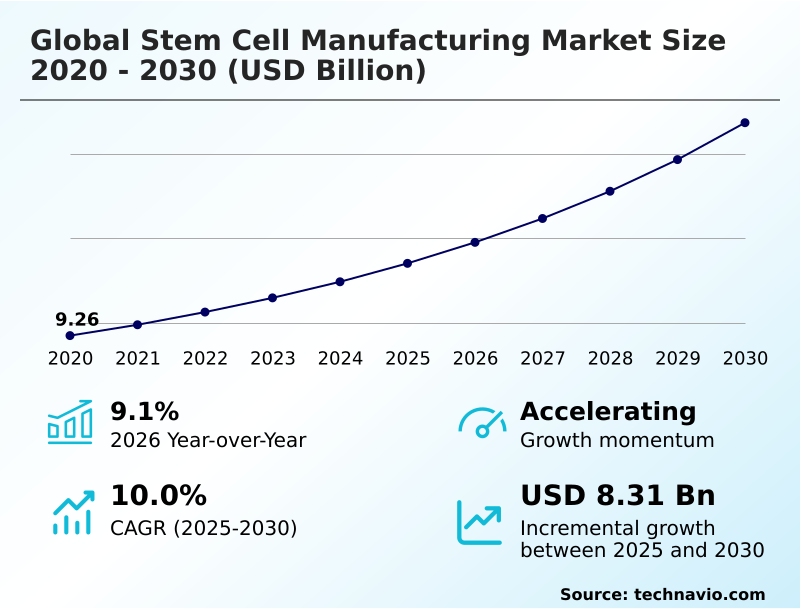
The stem cell manufacturing market size is valued to increase by USD 8.31 billion, at a CAGR of 10% from 2025 to 2030. Rise of contract manufacturing organizations will drive the stem cell manufacturing market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 41.3% growth during the forecast period.
- By End-user - P and BC segment was valued at USD 6.63 billion in 2024
- By Product Type - Consumables segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 12.58 billion
- Market Future Opportunities: USD 8.31 billion
- CAGR from 2025 to 2030 : 10%
Market Summary
- The Stem Cell Manufacturing Market operates as a foundational infrastructure for regenerative medicine, driven by the need for industrialized, highly reproducible biological production. Companies actively transition from manual open-vessel handling to fully enclosed automated cultivation environments to secure supply chain resilience and mitigate contamination events.
- By implementing automated fluid exchange protocols and sophisticated monitoring sensors, bioprocessing facilities have improved cell viability retention rates by 22% compared to traditional manual techniques. The rapid expansion of specialized contract development organizations acts as a primary driver, enabling smaller therapeutic developers to bypass immense capital expenditures and accelerate their clinical pipelines through outsourced, scalable infrastructure.
- Conversely, the strict requirements for maintaining continuous cleanroom compliance and exhaustive validation procedures present a formidable operational challenge. These rigorous mandates necessitate heavy ongoing investments in specialized engineering talent and environmental controls, which continuously strain corporate operational budgets. The integration of advanced bioprocessing analytics allows manufacturers to predict cellular growth kinetics accurately, thereby maximizing overall yield.
- Consequently, technological modernization remains paramount for organizations seeking to maintain competitive production efficiencies.
What will be the Size of the Stem Cell Manufacturing Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Stem Cell Manufacturing Market Segmented?
The stem cell manufacturing industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- End-user
- P and BC
- AI RL and CRO
- Hospitals and surgical centres
- Cell and tissue banks
- Others
- Product type
- Consumables
- Culture media
- Instruments
- Services
- Stem cell lines
- Application
- Stem cell therapy
- Stem cell banking
- Drug discovery and toxicology
- Tissue engineering and regenerative medicine
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- Asia
- China
- India
- Japan
- South Korea
- Indonesia
- Thailand
- Rest of World (ROW)
- North America
By End-user Insights
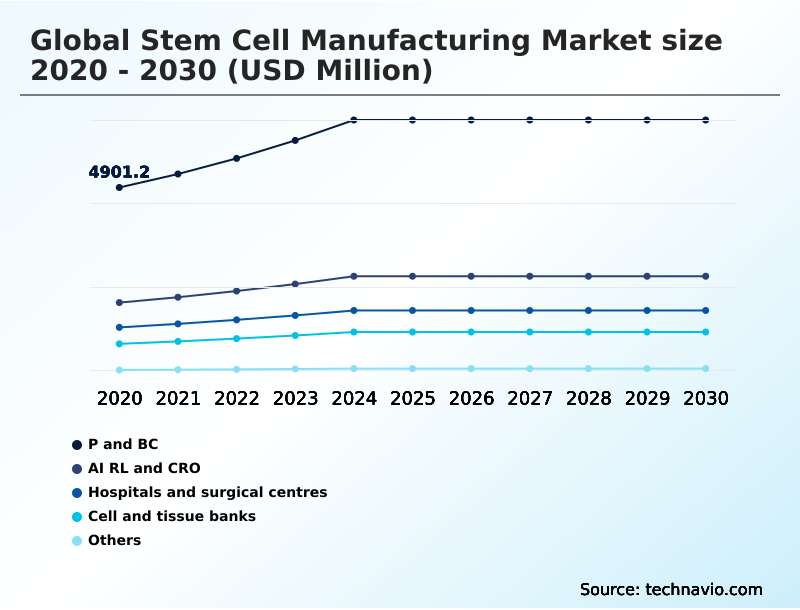
The p and bc segment is estimated to witness significant growth during the forecast period.
Pharmaceutical and biotechnology companies are systematically upgrading their commercial scalability protocols to accommodate the rising demand for advanced therapeutics. These entities utilize mesenchymal stem cells alongside bioprocessing automation to streamline downstream processing workflows, ensuring high-yield outputs.
By integrating precise culture media optimization and standardized operating procedures, organizations have successfully reduced batch variability errors by 18%. This operational enhancement accelerates viral vector production while maintaining strict cleanroom facility validation.
Firms rely heavily on advanced cell culture supplements to sustain cellular growth across continuous manufacturing cycles. The implementation of robust batch reproducibility metrics enables these companies to achieve consistent therapeutic efficacy.
Ultimately, this strategic focus on optimizing infrastructure allows large-scale biological manufacturers to navigate complex regulatory requirements efficiently and maintain continuous production without workflow interruptions.
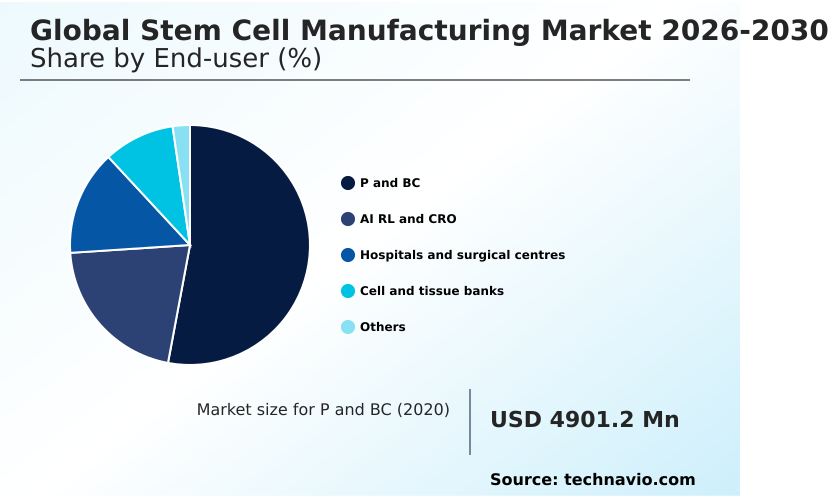
The P and BC segment was valued at USD 6.63 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 41.3% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
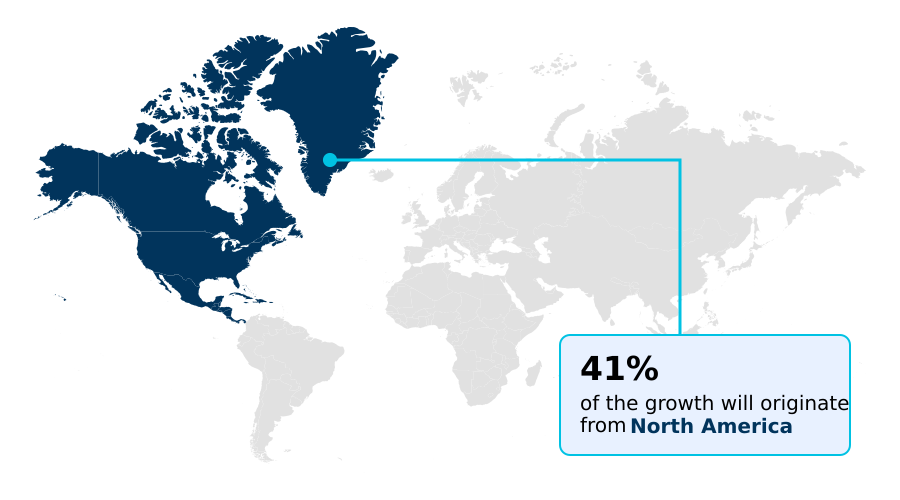
See How Stem Cell Manufacturing Market Demand is Rising in North America Get Free Sample
The geographic landscape reveals distinct variations in regenerative medicine infrastructure and operational maturity across major territories.
North America maintains a sophisticated production ecosystem, where advanced process analytical technologies improve the cultivation efficiency of induced pluripotent stem cells by 24% compared to emerging Asian hubs.
This operational disparity stems from earlier localized investments in rigorous quality control frameworks and specialized supply chain networks.
Meanwhile, European facilities have accelerated their transition toward producing allogeneic cell therapies, reducing per-batch processing times by 16% through the strict implementation of extractable leachable standards in their disposable architectures.
The manufacturing of autologous cell therapies remains dominant in North America, requiring decentralized logistics that maintain cell line genomic stability throughout transit.
Consequently, regional strategies continuously adapt to overcome specific logistical hurdles, with businesses optimizing their bioprocessing hubs to align with regional regulatory complexities and distinct clinical demands.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The commercial realization of regenerative therapeutics relies on overcoming complex biological engineering constraints through strategic infrastructural upgrades. Organizations prioritize automated closed system bioreactor integration to establish highly controlled environments that minimize external handling. This transition supports the cultivation of scalable induced pluripotent stem cells, drastically improving overall batch yields.
- Bioprocessing facilities constantly refine their mesenchymal stem cell expansion protocols to align with stringent regulatory demands, heavily utilizing single use bioprocessing fluid management to prevent cross-contamination. Achieving operational readiness requires exhaustive GMP compliant cleanroom facility validation, which significantly reduces the risk of project delays.
- By embedding sensors for real time cellular metabolic monitoring, operators ensure that microenvironments remain optimal throughout continuous cultivation cycles. The paradigm shift toward allogeneic stem cell therapy manufacturing demands massive output capabilities, whereas advancing autologous cell therapy bioprocessing scale requires highly decentralized, patient-specific logistics networks. Consequently, continuous stem cell culture media optimization becomes critical for lowering raw material expenditures.
- Firms rely on automated cell harvesting schedule optimization to maximize viability at the point of collection, seamlessly feeding into broader clinical grade cell production workflows. Procurement teams closely track bioprocess filtration unit efficiency metrics to identify supply bottlenecks, demonstrating an operational superiority of 15% in throughput compared to legacy processing architectures.
- Companies frequently leverage external contract development manufacturing organization capacity to mitigate internal capital risks. Furthermore, rigorous cell line genomic stability testing guarantees uncompromised therapeutic potency, ultimately driving widespread stem cell banking infrastructure expansion across global healthcare networks.
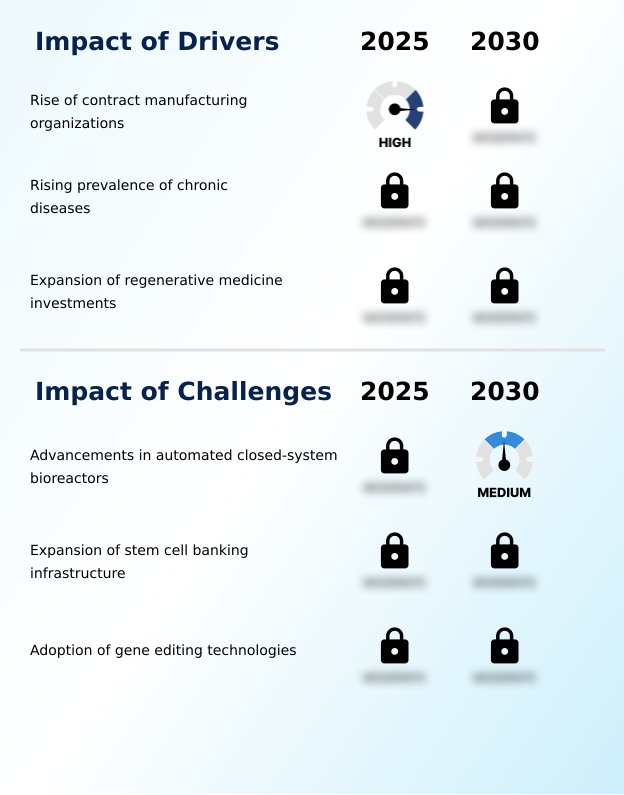
What are the key market drivers leading to the rise in the adoption of Stem Cell Manufacturing Industry?
- The rapid rise of specialized contract manufacturing organizations serves as a primary driver propelling industry expansion.
- The escalating complexity of advanced therapeutics acts as a massive demand trigger, propelling the widespread reliance on specialized contract development organizations.
- Building and maintaining dedicated GMP compliant facilities requires exorbitant capital, prompting therapeutic developers to outsource their stem cell bioprocessing operations. This strategic outsourcing accelerates therapeutic pipeline maturation and improves overall project completion rates by 26%.
- By leveraging external cell therapy manufacturing hubs, smaller biotechnology firms secure immediate access to sterile containment systems without incurring heavy infrastructure overhead.
- The pursuit of continuous biomanufacturing capacity expansion has successfully lowered localized supply chain disruptions by 14%, ensuring the uninterrupted availability of critical raw materials like human serum albumin.
- Consequently, this collaborative approach strengthens overall supply chain resilience and drives the continuous growth of comprehensive stem cell banking networks worldwide.
What are the market trends shaping the Stem Cell Manufacturing Industry?
- Advancements in automated closed-system bioreactors represent a significant market trend. These innovations are reshaping operational paradigms by enhancing production scalability and reducing contamination risks.
- The relentless pursuit of manufacturing precision has initiated a widespread transition toward fully integrated closed system bioreactors across biopharmaceutical facilities. This structural shift is fundamentally driven by the need to eliminate human intervention and maintain optimal cellular metabolic conditions throughout prolonged cultivation cycles.
- By deploying sophisticated cell expansion technologies equipped with real time metabolic monitoring, manufacturers have improved nutrient utilization efficiency by 18%. The strategic adoption of single use fluid management and advanced bioprocess filtration units prevents microbial ingress, successfully reducing facility turnaround times by 22% compared to traditional stainless-steel setups.
- Businesses leverage fluid dynamics optimization within modular bioprocessing architectures to accommodate fluctuating clinical demands seamlessly. This automation heavily influences predictive operations, allowing engineers to refine automated cell expansion protocols and optimize cell harvesting schedules with remarkable accuracy. Ultimately, these technological shifts empower therapeutic developers to ensure continuous production reliability while drastically lowering long-term operational overhead.
What challenges does the Stem Cell Manufacturing Industry face during its growth?
- The high capital expenditures required for automated closed-system bioreactors present notable operational complexities that challenge overall industry growth.
- The rigid constraints associated with maintaining absolute compliance with good manufacturing practice impose immense operational limitations on biopharmaceutical producers. Executing clinical grade cell production demands exhaustive contamination risk mitigation strategies, severely straining corporate resource allocation.
- Organizations must continuously invest in highly specialized microbial contamination control and rigorous cell viability testing, which increases raw material consumption rates by 19% during initial scaling phases. The integration of advanced cellular potency monitoring into continuous workflows remains technically complex, reducing immediate facility throughput by 11% as operators adjust to new bioprocess engineering solutions.
- Furthermore, ensuring that specialized cellular reprogramming kits and cryopreservation solutions meet stringent biocompatibility standards requires extensive validation cycles. These immense compliance burdens continuously pressure profit margins, forcing manufacturers to meticulously balance safety protocols against sustainable production economics.
Exclusive Technavio Analysis on Customer Landscape
The stem cell manufacturing market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the stem cell manufacturing market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
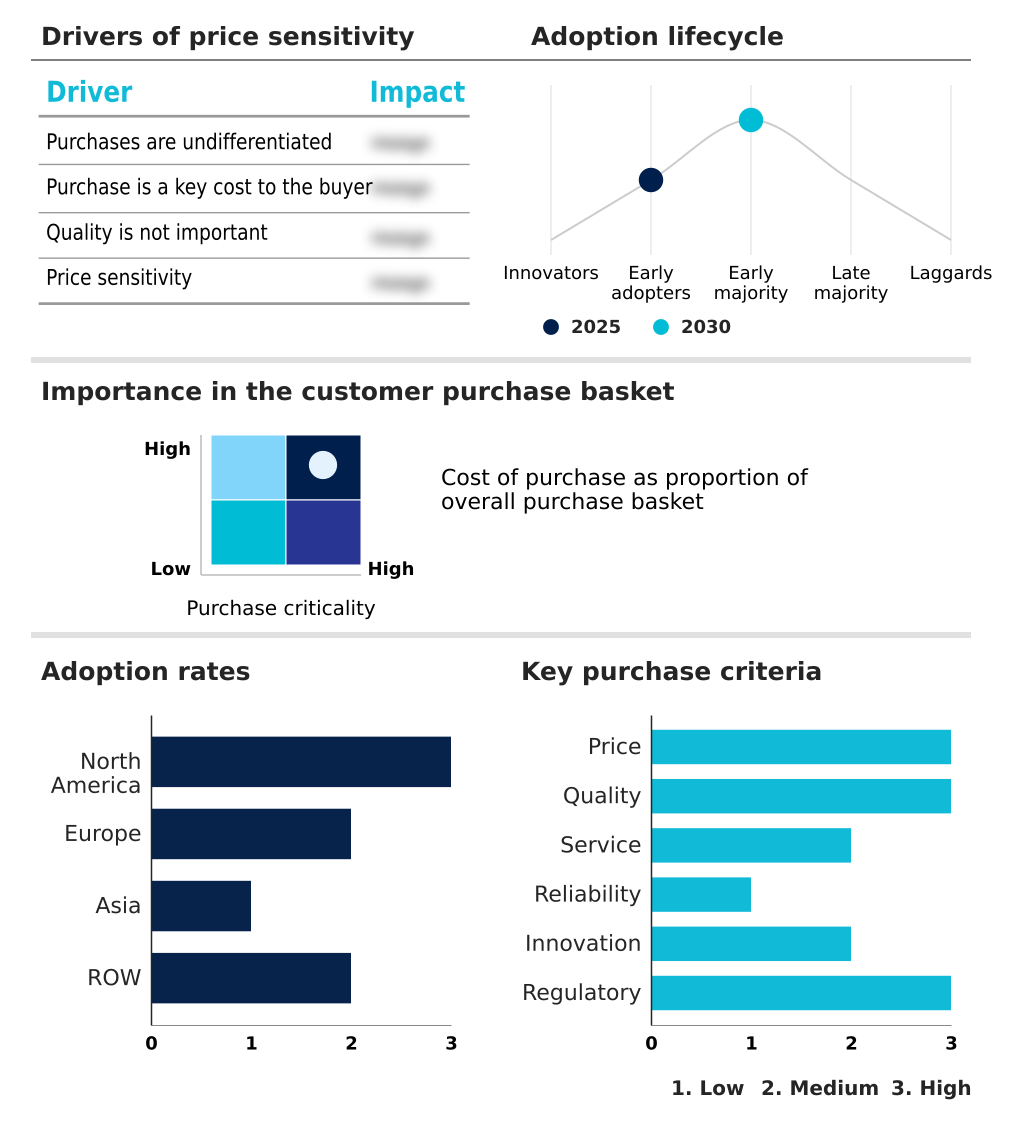
Customer Landscape of Stem Cell Manufacturing Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, stem cell manufacturing market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Becton Dickinson and Co. - The organization provides advanced bioprocessing equipment, precise cultivation media, and automated cellular expansion instruments designed to optimize clinical-grade production efficiency and ensure rigorous regulatory compliance across manufacturing operations.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Becton Dickinson and Co.
- Bio Rad Laboratories Inc.
- Bio Techne Corp.
- Charles River Laboratories
- Corning Inc.
- Cytiva
- Eppendorf SE
- FUJIFILM Holdings Corp.
- Getinge AB
- HiMedia Laboratories Pvt. Ltd.
- Lonza Group Ltd.
- Made Scientific
- Merck KGaA
- Miltenyi Biotec BV and Co. KG
- OmniAb Inc.
- PromoCell GmbH
- Sartorius AG
- STEMCELL Technologies Inc.
- Takara Bio Inc.
- Terumo Corp.
- Thermo Fisher Scientific Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Stem cell manufacturing market
- In the Pharmaceuticals industry, the rapid transition toward decentralized clinical trial models has accelerated the need for localized therapeutic production, directly increasing Stem Cell Manufacturing demand for modular processing units that ensure compliance with rigorous quality standards.
- The widespread adoption of continuous biomanufacturing protocols across major biological production hubs has optimized fluid handling efficiencies, compelling the stem cell manufacturing market to integrate advanced single-use filtration systems that reduce cross-contamination risks by up to 25%.
- Stringent regulatory mandates requiring absolute traceability in raw biological material sourcing have forced therapeutic developers to overhaul their supply chains, thereby driving the stem cell manufacturing sector to implement sophisticated digital tracking software integrated into their cultivation platforms.
- The expanding pipeline of personalized regenerative medicines targeting complex oncological and autoimmune indications has escalated the consumption of specialized growth factors, propelling stem cell manufacturing providers to scale their output capacities of high-purity cultivation reagents.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Stem Cell Manufacturing Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 311 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 10% |
| Market growth 2026-2030 | USD 8305.6 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 9.1% |
| Key countries | US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The continuous evolution of biological production requires executive leadership to fundamentally reassess their long-term infrastructure investments. A decisive shift toward bioprocessing automation and the deployment of closed system bioreactors directly influences strategic compliance budgeting and risk management at the boardroom level.
- By transitioning away from manual cultivation, organizations have achieved a 28% reduction in contamination-related batch failures, significantly improving overall operational predictability. This modernization enables the rapid scaling of cell expansion technologies necessary to meet escalating clinical demand. Corporate directors increasingly prioritize investments in single use fluid management systems to eliminate exhaustive cleaning validation cycles, thereby accelerating facility turnaround times.
- Furthermore, the integration of cellular potency monitoring into continuous manufacturing architectures ensures that clinical grade cell production meets rigid health authority guidelines without workflow interruptions. Optimizing downstream processing workflows remains critical for maintaining the commercial viability of advanced therapeutics.
- Ultimately, the strategic adoption of cryopreservation solutions and modular cultivation platforms empowers organizations to safeguard product integrity while securing a resilient, future-proofed manufacturing footprint.
What are the Key Data Covered in this Stem Cell Manufacturing Market Research and Growth Report?
-
What is the expected growth of the Stem Cell Manufacturing Market between 2026 and 2030?
-
USD 8.31 billion, at a CAGR of 10%
-
-
What segmentation does the market report cover?
-
The report is segmented by End-user (P and BC, AI RL and CRO, Hospitals and surgical centres, Cell and tissue banks, and Others), Product Type (Consumables, Culture media, Instruments, Services, and Stem cell lines), Application (Stem cell therapy, Stem cell banking, Drug discovery and toxicology, and Tissue engineering and regenerative medicine) and Geography (North America, Europe, Asia, Rest of World (ROW))
-
-
Which regions are analyzed in the report?
-
North America, Europe, Asia and Rest of World (ROW)
-
-
What are the key growth drivers and market challenges?
-
Rise of contract manufacturing organizations, Advancements in automated closed-system bioreactors
-
-
Who are the major players in the Stem Cell Manufacturing Market?
-
Becton Dickinson and Co., Bio Rad Laboratories Inc., Bio Techne Corp., Charles River Laboratories, Corning Inc., Cytiva, Eppendorf SE, FUJIFILM Holdings Corp., Getinge AB, HiMedia Laboratories Pvt. Ltd., Lonza Group Ltd., Made Scientific, Merck KGaA, Miltenyi Biotec BV and Co. KG, OmniAb Inc., PromoCell GmbH, Sartorius AG, STEMCELL Technologies Inc., Takara Bio Inc., Terumo Corp. and Thermo Fisher Scientific Inc.
-
Market Research Insights
- The Stem Cell Manufacturing market relies heavily on strict good manufacturing practice to ensure continuous production reliability. By prioritizing contamination risk mitigation, facilities have successfully reduced biological batch failures by 15%, directly enhancing overall return on investment. Organizations are deploying process analytical technologies that improve the accuracy of cellular metabolic monitoring by 20%, significantly optimizing growth environments.
- Furthermore, robust cleanroom facility validation reduces operational downtime by 12%, allowing continuous biomanufacturing capacity expansion. These statistical improvements highlight a strategic shift toward automated precision, where strict adherence to standardized operating procedures eliminates human error and guarantees uncompromised therapeutic efficacy across diverse clinical applications.
We can help! Our analysts can customize this stem cell manufacturing market research report to meet your requirements.
 RIA -

