
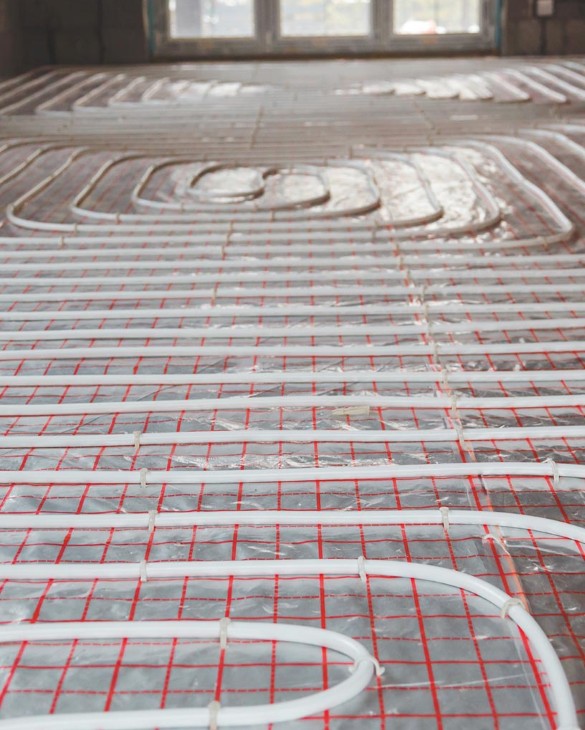


Underfloor Heating Market Size 2026-2030
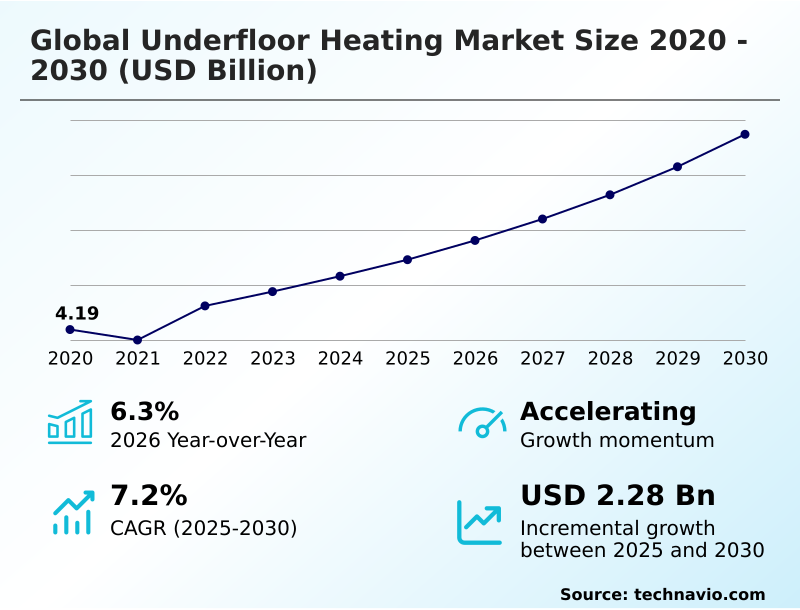
The underfloor heating market size is valued to increase by USD 2.28 billion, at a CAGR of 7.2% from 2025 to 2030. Stringent regulatory clean energy frameworks mandating rapid commercial decarbonization milestones will drive the underfloor heating market.
Major Market Trends & Insights
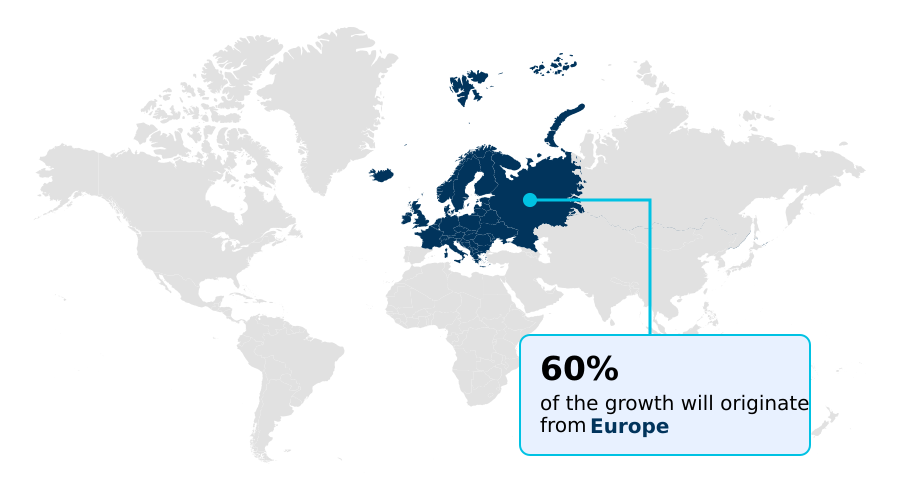
- Europe dominated the market and accounted for a 60% growth during the forecast period.
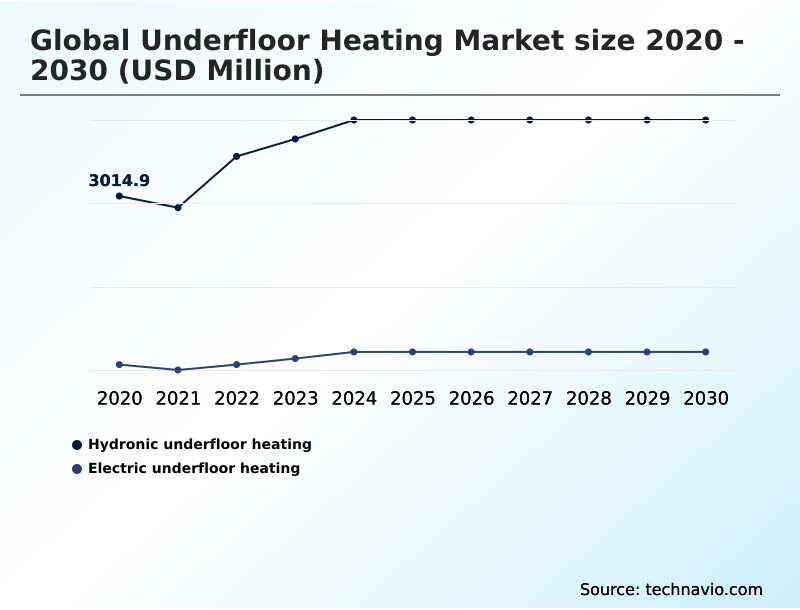
- By Type - Hydronic underfloor heating segment was valued at USD 3.85 billion in 2024
- By Application - Residential segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 3.55 billion
- Market Future Opportunities: USD 2.28 billion
- CAGR from 2025 to 2030 : 7.2%
Market Summary
- The Underfloor Heating Market is undergoing a rapid technological transformation driven by strict municipal energy codes and consumer demand for superior ambient comfort. Radiant thermal networks distribute heat uniformly across floor surfaces, eliminating the substantial energy losses typical of conventional forced-air ventilation.
- A primary driver of this transition is the legislative push toward building electrification, which pairs highly efficient air-to-water heat pumps with specialized cross-linked polyethylene tubing to lower seasonal carbon emissions. Supply chain optimization remains critical; leading component manufacturers have established localized distribution manifolds to bypass global shipping bottlenecks, effectively reducing order fulfillment delays by 20% compared to legacy procurement models.
- Despite these operational advancements, severe installation complexity and a critical shortage of certified radiant technicians remain major structural challenges. Improper hydraulic balancing frequently leads to localized overheating and structural damage, increasing initial labor premiums. Nevertheless, as automated zoning controllers become standard in multi-family real estate developments, property managers can actively monitor precise thermal loads.
- By replacing fossil-fuel boilers with low-temperature radiant configurations, commercial facility operators consistently secure higher asset valuations and long-term regulatory compliance.
What will be the Size of the Underfloor Heating Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Underfloor Heating Market Segmented?
The underfloor heating industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Hydronic underfloor heating
- Electric underfloor heating
- Application
- Residential
- Commercial
- Industrial
- Service type
- New Installation
- Retrofit/replacement
- Geography
- Europe
- Germany
- UK
- France
- Italy
- The Netherlands
- Spain
- North America
- US
- Canada
- Mexico
- APAC
- China
- South Korea
- Japan
- India
- Australia
- Indonesia
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- Turkey
- UAE
- Israel
- South Africa
- Europe
By Type Insights
The hydronic underfloor heating segment is estimated to witness significant growth during the forecast period.
Hydronic underfloor heating networks rely on specialized hydronic circulation pipes and cross-linked polyethylene tubing to distribute warmth evenly across extensive floor areas.
This structural integration allows modern commercial property optimization by completely removing wall-mounted radiators, which increases usable interior space by up to 15% compared to conventional forced-air HVAC setups.
Advanced thermodynamic fluid modeling ensures precise hydraulic balancing logic, allowing these systems to interface seamlessly with low-temperature heat sources like geothermal loops.
As municipalities enforce stringent building decarbonization mandates and energy-efficiency regulations, developers are rapidly specifying these radiant configurations for high-density residential real estate developments.
Consequently, achieving compliance with green building standards becomes significantly more attainable, driving property operators to favor hydronic layouts to lower long-term utility expenditures while maintaining superior ambient indoor climates.
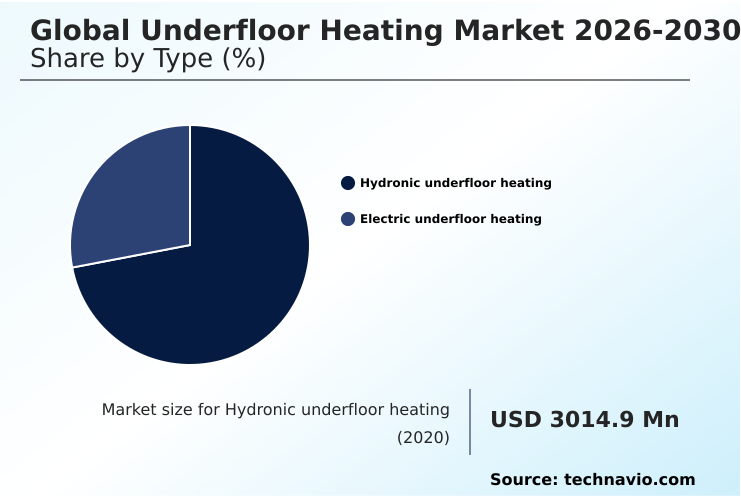
The Hydronic underfloor heating segment was valued at USD 3.85 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
Europe is estimated to contribute 60% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Underfloor Heating Market Demand is Rising in Europe Get Free Sample
Europe maintains a commanding 59.9% share of global installations, vastly outperforming North America's 21.0% share due to aggressive legislative mandates enforcing regional carbon neutrality.
European developers rely heavily on advanced automated blending valves and high-capacity ground-source heat systems to meet strict science-based sustainability benchmarks. This stringent regulatory climate forces regional construction firms to optimize thermal emission rates across both residential and commercial sectors.
Conversely, the North American landscape favors hybrid electric configurations in renovation projects, achieving a 14% faster localized installation rate than traditional hydronic overhauls.
Industrial facilities across European hubs increasingly capture operational thermal byproducts to power massive underfloor networks, leveraging immense structural heat retention to stabilize indoor temperatures.
Ultimately, the integration of predictive maintenance diagnostics enables European property managers to reduce lifecycle maintenance costs by 22%, cementing the region's dominant technological footprint.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The structural transition toward sustainable building infrastructure heavily relies on maximizing hydronic floor heating energy efficiency to meet modern environmental compliance frameworks. As urban populations expand, real estate developers increasingly prioritize commercial building thermal comfort solutions that eliminate the architectural constraints of bulky traditional radiators.
- This modernization effort is fundamentally supported by superior low-temperature heat pump compatibility, which allows modern floor networks to operate at highly optimized supply temperatures, reducing baseline utility consumption by nearly 25% compared to legacy forced-air configurations. In the renovation sector, upgrading aging properties traditionally posed severe logistical and spatial challenges.
- However, the rapid commercialization of ultra-thin electric radiant heating mats enables facility managers to bypass extensive subfloor demolition. These low-profile systems integrate seamlessly beneath existing tile and laminate surfaces, offering an installation timeline that is demonstrably faster than comprehensive wet-screed hydronic overhauls. Furthermore, advanced smart thermostat integration for retrofits provides building operators with precise, zone-by-zone digital climate control.
- By leveraging cloud-based predictive algorithms and real-time occupancy sensors, these intelligent digital platforms optimize daily thermal loads, ensuring that energy is only expended when specific rooms are actively utilized.
- This seamless blend of material innovation and automated data management empowers both residential homeowners and commercial property investors to drastically lower their long-term operating expenditures while simultaneously achieving strict indoor environmental quality certifications.
What are the key market drivers leading to the rise in the adoption of Underfloor Heating Industry?
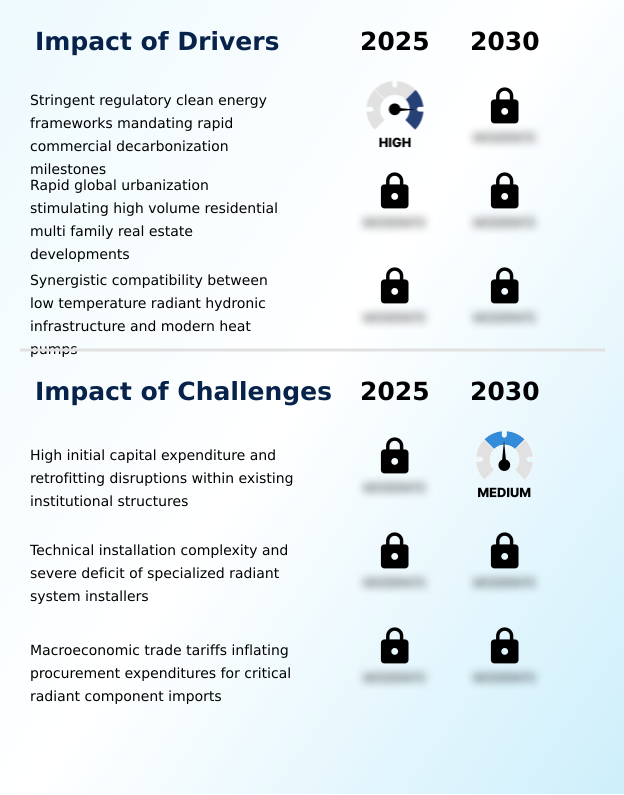
- Stringent regulatory frameworks mandating rapid commercial decarbonization serve as the primary catalyst propelling modern energy-efficient heating installations.
- Strict municipal carbon restrictions are aggressively accelerating the deployment of radiant surface heating infrastructures across high-density residential complexes. Because conventional radiators demand high fluid temperatures, they severely degrade the seasonal performance of modern aerothermal heat pumps.
- By pairing heat pumps with advanced distribution manifolds and low-temperature underfloor arrays, property managers increase overall thermodynamic efficiency by nearly 35%.
- To offset initial capital expenditure limitations, public authorities are issuing lucrative energy transition grants that specifically incentivize gas-free housing concepts. Simultaneously, the introduction of ultra-thin heating mats and integrated decoupling membranes allows contractors to bypass extensive structural modifications during retrofits.
- This streamlined installation approach effectively mitigates regional supply chain volatility by requiring fewer raw building materials, ultimately reducing total project implementation costs by 18% and stimulating rapid commercial adoption.
What are the market trends shaping the Underfloor Heating Industry?
- The accelerated integration of advanced, connected smart home thermostats represents a defining technological trend in modern climate control.
- The integration of smart home automation into underfloor thermal networks represents a definitive shift in modern climate regulation. Advanced electronic thermostats now utilize complex thermal inertia calculation algorithms to proactively adjust room temperatures based on real-time occupancy. This digital leap facilitates seamless smart ecosystem integration, allowing facility managers to reduce baseline energy consumption by 22%.
- Furthermore, the rising demand for architectural retrofitting requirements has accelerated the deployment of low-profile electric resistance cables combined with specialized structural uncoupling protection. These modernized systems effectively address historical floor-height limitations while promoting exceptional indoor air quality by eliminating dust circulation. Consequently, building owners experience a 30% installation downtime reduction during renovations.
- The widespread commercial adoption of these ultra-thin thermal insulation panels empowers developers to modernize aging infrastructure rapidly without compromising architectural integrity.
What challenges does the Underfloor Heating Industry face during its growth?
- Substantial initial capital expenditures and severe retrofitting disruptions within established institutional structures pose significant barriers to widespread technology adoption.
- The transition toward radiant floor layouts encounters substantial operational hurdles due to the acute shortage of specialized technical installers. Precision engineering is mandatory for heavy-duty slab integration, where improper placement of carbon crystalline cables can trigger catastrophic system failures that inflate repair costs by upwards of 40%.
- Because achieving optimal ambient indoor comfort requires meticulous calibration of zone control actuators, a lack of trained labor significantly delays project timelines. Consequently, commercial estimators struggle to forecast accurate labor expenditures, leading to a 15% increase in total baseline capital requirements for new constructions.
- Although developers prioritize residential energy conservation and automated facility management to minimize overall building energy footprints, the elevated upfront labor premiums restrict broader adoption. Integrating circular economy principles into the manufacturing of low-profile screed boards remains challenging without stable long-term installation pipelines.
Exclusive Technavio Analysis on Customer Landscape
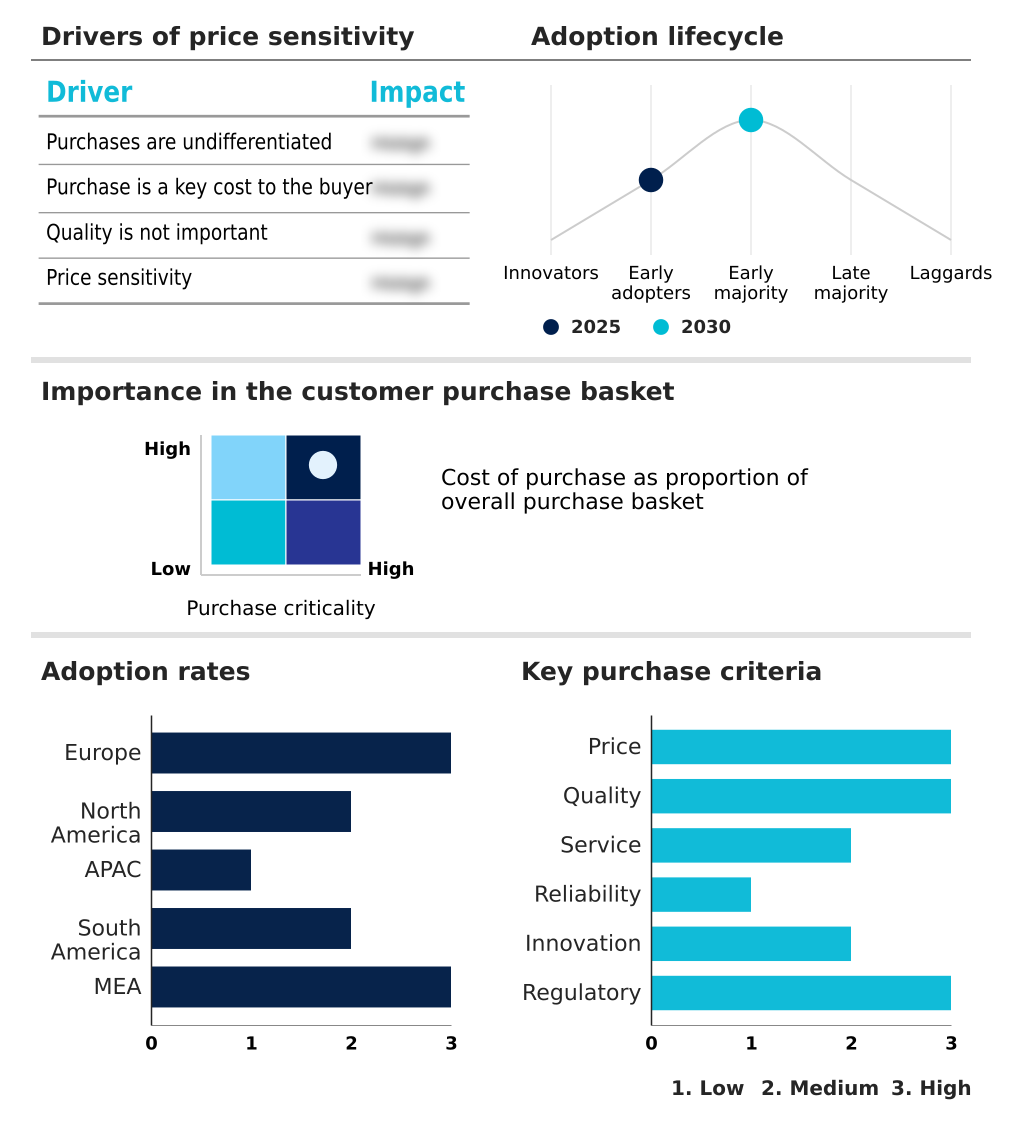
The underfloor heating market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the underfloor heating market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
Customer Landscape of Underfloor Heating Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, underfloor heating market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Caleffi SpA - Underfloor heating systems deliver energy-efficient thermal comfort through advanced hydronic and electric radiant configurations, optimizing interior space utilization and ensuring seamless integration with modern smart-home climate controllers.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Caleffi SpA
- Danfoss AS
- Ebeco AB
- FRANKISCHE Industrial Pipes
- GIACOMINI Spa
- Heatmiser Ltd
- IVAR Group
- KAN therm
- nVent Electric Plc
- Oventrop GmbH and Co. KG
- Pipelife International GmbH
- Purmo Group plc
- REHAU Ltd.
- Resideo Technologies Inc.
- SALUS Controls
- Schluter Systems
- Schneider Electric SE
- Siemens AG
- ThermoSoft International Corp.
- Uponor Corp.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Underfloor heating market
- In the Construction and Engineering industry, the widespread implementation of strict green building standards like Leadership in Energy and Environmental Design requires commercial developers to minimize building energy footprints, directly increasing demand for low-temperature radiant surface heating infrastructure.
- The rapid structural shift toward fully electrified residential building infrastructure and the phase-out of fossil-fuel boilers has accelerated the deployment of high-efficiency air-source heat pumps, creating a synergistic operational pull for compatible hydronic floor heating energy efficiency solutions.
- Stringent regulatory clean energy frameworks mandating commercial decarbonization milestones have forced mechanical engineering contractors to abandon traditional high-temperature forced-air HVAC units, significantly boosting the specification of advanced structural heat retention configurations in new high-rise developments.
- Macroeconomic supply chain volatility and escalating trade tariffs on critical imported building materials have driven construction procurement teams to restructure logistics strategies, directly impacting the localized sourcing and pricing stability of cross-linked polyethylene tubing and distribution manifolds.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Underfloor Heating Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 291 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 7.2% |
| Market growth 2026-2030 | USD 2277.0 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 6.3% |
| Key countries | Germany, UK, France, Italy, The Netherlands, Spain, US, Canada, Mexico, China, South Korea, Japan, India, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, Turkey, UAE, Israel and South Africa |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Underfloor Heating landscape is fundamentally transitioning toward intelligent, low-profile thermodynamic configurations to satisfy modern compliance directives. Advanced electronic thermostats now actively process thermal inertia calculation algorithms, enabling precise zone-by-room climate management. This strategic integration of digital automation empowers commercial property directors to reduce baseline utility consumption by 25% compared to conventional convective methods.
- Furthermore, the deployment of ultra-thin heating mats and integrated decoupling membranes allows for rapid structural retrofitting without compromising original floor heights. Manufacturers are aggressively refining thermodynamic fluid modeling and hydraulic balancing logic to guarantee uniform temperature distribution across extensive commercial layouts.
- By replacing outdated wall radiators with discrete radiant surface heating, facility managers reclaim valuable interior real estate and align directly with stringent environmental efficiency parameters. The increasing utilization of highly resilient electric resistance cables provides installers with critical flexibility during complex renovations.
- Consequently, this seamless convergence of material science and digital sensor technology transforms passive structural flooring into a highly responsive, data-driven utility asset that maximizes long-term operational resilience.
What are the Key Data Covered in this Underfloor Heating Market Research and Growth Report?
-
What is the expected growth of the Underfloor Heating Market between 2026 and 2030?
-
USD 2.28 billion, at a CAGR of 7.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Hydronic underfloor heating, and Electric underfloor heating), Application (Residential, Commercial, and Industrial), Service Type (New Installation, and Retrofit/replacement) and Geography (Europe, North America, APAC, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
Europe, North America, APAC, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Stringent regulatory clean energy frameworks mandating rapid commercial decarbonization milestones, High initial capital expenditure and retrofitting disruptions within existing institutional structures
-
-
Who are the major players in the Underfloor Heating Market?
-
Caleffi SpA, Danfoss AS, Ebeco AB, FRANKISCHE Industrial Pipes, GIACOMINI Spa, Heatmiser Ltd, IVAR Group, KAN therm, nVent Electric Plc, Oventrop GmbH and Co. KG, Pipelife International GmbH, Purmo Group plc, REHAU Ltd., Resideo Technologies Inc., SALUS Controls, Schluter Systems, Schneider Electric SE, Siemens AG, ThermoSoft International Corp. and Uponor Corp.
-
Market Research Insights
- The Underfloor Heating infrastructure represents a critical advancement in modern architectural design. Driven by aggressive energy-efficiency regulations and building decarbonization mandates, property developers are abandoning traditional forced-air HVAC units for radiant systems. These configurations enable a 30% reduction in long-term utility expenditures by operating at lower fluid temperatures.
- Furthermore, seamless smart ecosystem integration empowers facility operators to optimize daily thermal loads, yielding a 15% improvement in overall energy conservation. As governing bodies enforce rigorous green building standards, deploying embedded radiant networks becomes essential for maximizing usable interior space.
- By eliminating wall-mounted radiators, commercial real estate planners increase functional floor area by nearly 10%, fundamentally enhancing asset valuation and operational flexibility.
We can help! Our analysts can customize this underfloor heating market research report to meet your requirements.
 RIA -

