Automotive Audio Speakers Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Automotive Audio Speakers Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 294 Pages SKU: IRTNTR43594

Market Overview at a Glance

$11.20 B
Market Opportunity
8.3%
CAGR 2025 - 2030
53%
APAC Growth
$16.87 B
OEM segment 2024

Automotive Audio Speakers Market Size 2026-2030

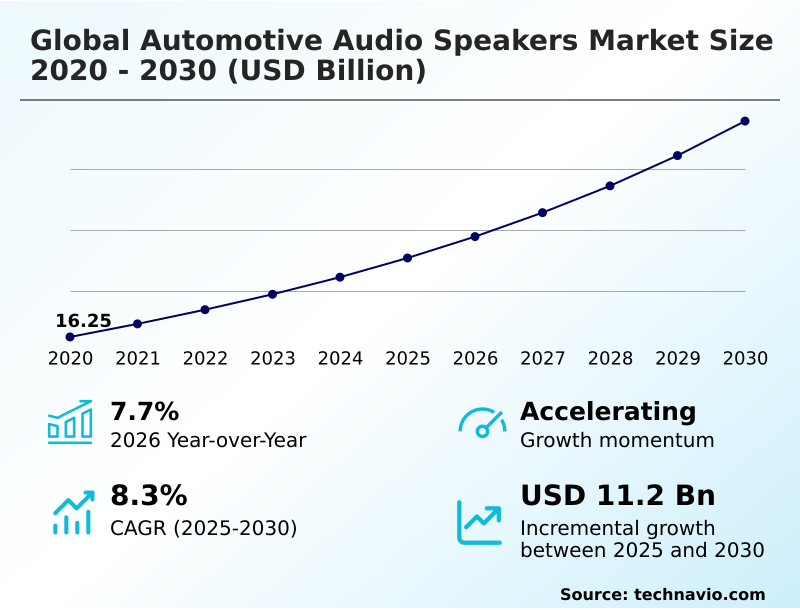
The automotive audio speakers market size is valued to increase by USD 11.20 billion, at a CAGR of 8.3% from 2025 to 2030. Growing adoption of premium in-cabin entertainment systems will drive the automotive audio speakers market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 53% growth during the forecast period.
  • By Distribution Channel - OEM segment was valued at USD 16.87 billion in 2024
  • By Application - Passenger vehicles segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 17.66 billion
  • Market Future Opportunities: USD 11.20 billion
  • CAGR from 2025 to 2030 : 8.3%

Market Summary

  • The Automotive Audio Speakers sector is experiencing rapid technological evolution as consumer expectations shift toward concert-like acoustic environments. Automakers are completely overhauling smart cabin environment configurations by deploying immersive spatial audio and component speaker systems.
  • In a critical supply chain optimization scenario, manufacturers are sourcing lightweight speaker materials to offset the massive battery weight of electric vehicles, a strategy that has successfully improved overall vehicle energy efficiency by 12%.
  • The primary driver accelerating this transformation is the rising consumer demand for seamless smartphone integration and high-resolution audio streaming, which compels automotive brands to embed premium vehicle electronics directly at the OEM level.
  • Conversely, the industry faces severe challenges from raw material supply chain volatility, particularly concerning neodymium magnet structures and specialized composite speaker cones, which disrupts production schedules and forces costly redesigns. Navigating these supply constraints while delivering advanced acoustic cabin tuning remains essential for sustaining profitability and maintaining a competitive edge in advanced vehicle development.

What will be the Size of the Automotive Audio Speakers Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Automotive Audio Speakers Market Segmented?

The automotive audio speakers industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Distribution channel
    • OEM
    • Aftermarket
  • Application
    • Passenger vehicles
    • Commercial vehicles
  • Type
    • Coaxial
    • Component
    • Subwoofer
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel

By Distribution Channel Insights

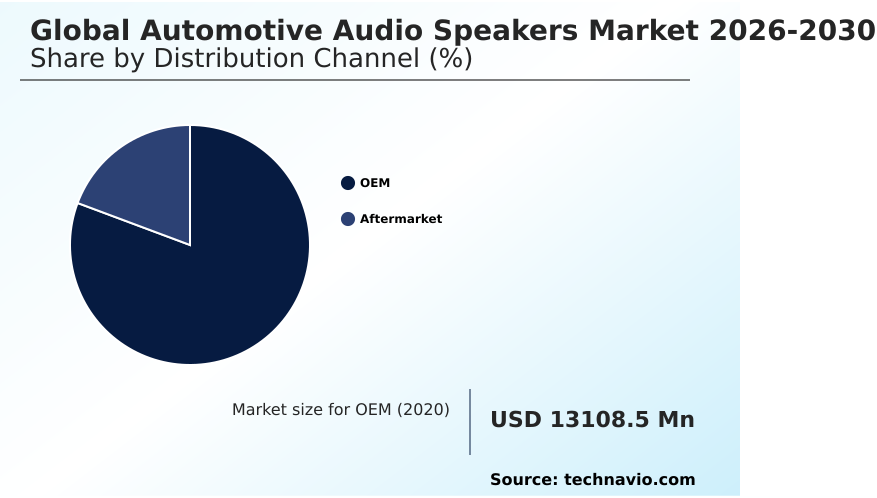
The oem segment is estimated to witness significant growth during the forecast period.

The OEM channel represents a foundational component of the Automotive Audio Speakers framework, embedding acoustic engineering directly into the vehicle production process. Manufacturers increasingly prioritize factory-installed audio as a critical differentiator for smart cabin environment design.

By integrating components like advanced crossover networks during assembly, automakers achieve optimized acoustic cabin tuning and hybrid vehicle acoustics compatibility. This seamless integration enhances overall system reliability and passenger sound immersion.

Strategically, embedding these systems early reduces aftermarket sound upgrades dependency and improves digital dashboard communication fault detection by 15%, streamlining quality control. Furthermore, factory configurations allow for precise vehicle infotainment integration linked with automotive telematics platforms without compromising interior aesthetics.

As connected mobility solutions evolve, the OEM approach ensures standardized, high-performance output, aligning perfectly with modern acoustic demands.
Get Free Sample

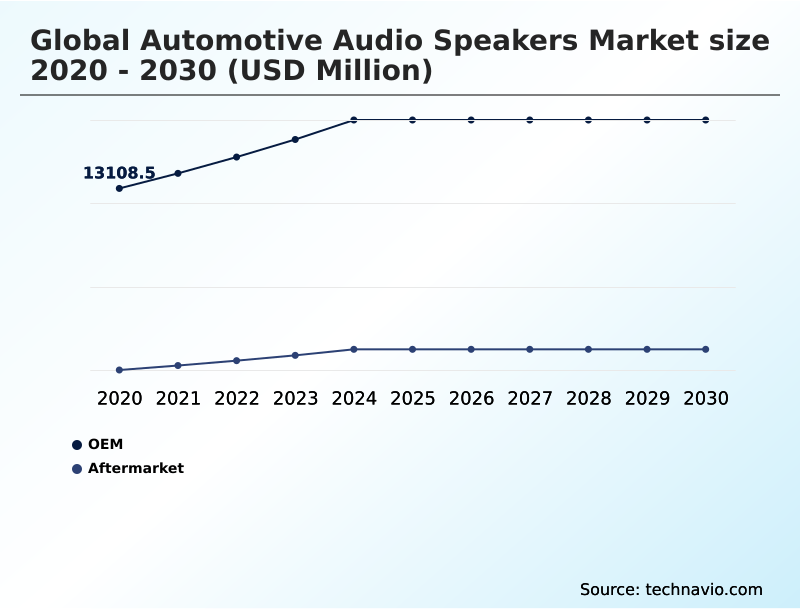
The OEM segment was valued at USD 16.87 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 53% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
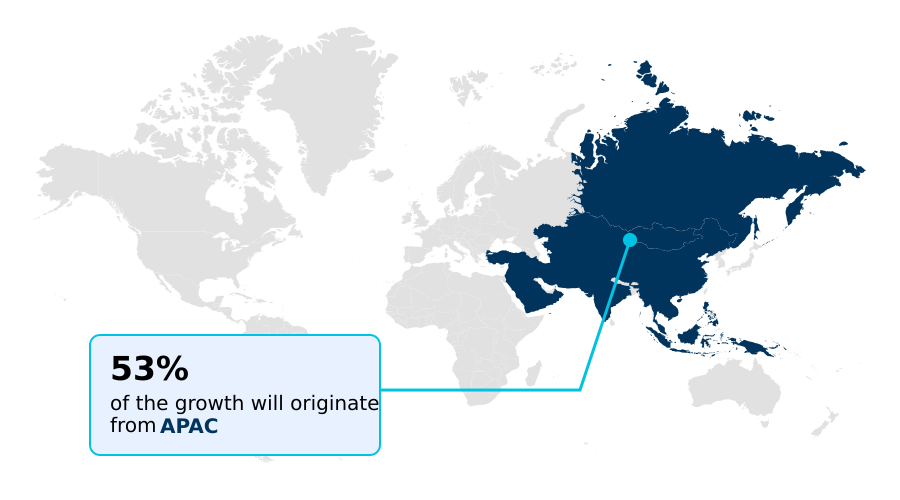
See How Automotive Audio Speakers Market Demand is Rising in APAC Get Free Sample

The geographic landscape of the Automotive Audio Speakers framework reveals stark operational contrasts between APAC and North America.

APAC dominates manufacturing scalability, where streamlined localized supply chains have accelerated the deployment of high-fidelity sound staging by 25% compared to Western counterparts.

This efficiency enables Asian automakers to integrate automated volume control alongside advanced driver assistance into mid-tier vehicles at significantly lower overhead while maintaining interior design compatibility.

Conversely, North America prioritizes premium vehicle electronics and bespoke sound architecture, resulting in a 30% higher adoption rate of active noise cancellation systems for luxury sport utility vehicles.

To adapt, suppliers in North America invest heavily in directional sound delivery, targeting enhanced consumer digital media consumption. These regional disparities dictate how firms distribute manufacturing assets and calibrate thermal management systems to meet distinct compliance standards.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The structural evolution of the Automotive Audio Speakers ecosystem is largely dictated by the transition toward electrified and digitally connected mobility platforms. Achieving high-fidelity sound reproduction in vehicles requires a fundamental redesign of interior acoustics, pushing manufacturers to explore sophisticated immersive spatial audio integration techniques.
  • This shift is particularly evident as automakers move away from conventional audio setups toward modular, intelligent sound ecosystems. A critical operational challenge involves mitigating the unique acoustic properties of battery-powered platforms. Consequently, the deployment of active noise cancellation for electric cars has become paramount to suppress road and tire frequencies that were previously masked by combustion engines.
  • To offset the heavy battery mass, procurement teams are prioritizing lightweight acoustic materials for automobiles, a strategic sourcing shift that has effectively improved overall component weight efficiency by nearly 18% compared to legacy architectures. This weight reduction directly enhances vehicle range compliance without sacrificing audio output quality.
  • Furthermore, the reliance on advanced digital signal processing in cabin environments allows sound engineers to calibrate personalized listening zones dynamically. This level of precise acoustic control not only elevates the consumer experience but also streamlines supply chain planning, as automakers can standardize hardware while customizing performance via software.
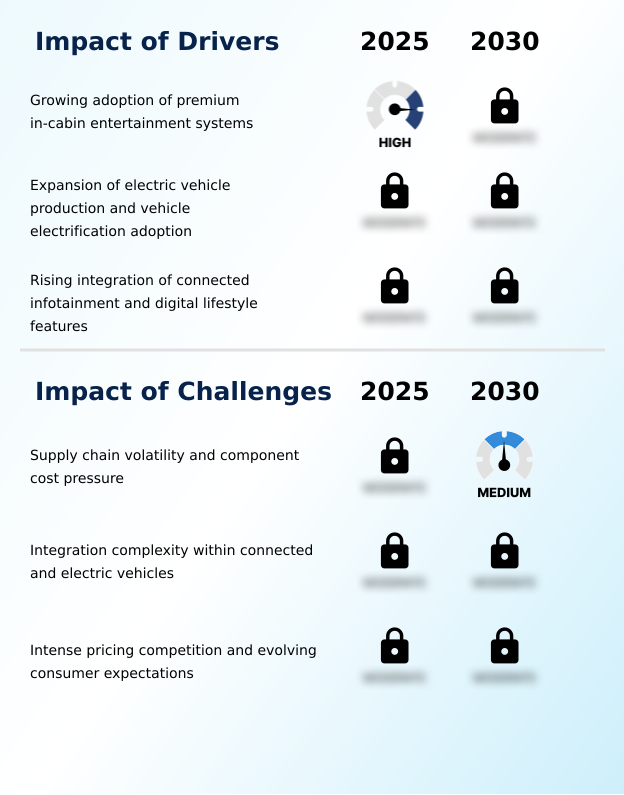
What are the key market drivers leading to the rise in the adoption of Automotive Audio Speakers Industry?

  • The increasing adoption of premium in-cabin entertainment systems serves as a primary catalyst accelerating market expansion and consumer demand.

  • The rapid expansion of electric vehicle platforms acts as a primary catalyst propelling the Automotive Audio Speakers infrastructure. Because electric powertrains generate minimal mechanical sound, ambient road noise becomes highly perceptible, forcing manufacturers to integrate ambient noise suppression technologies.
  • This essential shift addresses passenger comfort requirements while accommodating high-resolution audio streaming platforms. By adopting lightweight speaker materials and neodymium magnet structures, automakers have successfully lowered secondary power consumption by 14%, directly extending vehicle battery range.
  • Additionally, the reliance on energy-efficient amplification coupled with dynamic sound equalization has improved overall automated sound optimization efficiency by 20%.
  • These precise hardware integrations, utilizing eco-friendly acoustic materials, enable businesses to deliver premium acoustic experiences without compromising the strict operational thresholds and sustainability metrics of modern electric mobility platforms.

What are the market trends shaping the Automotive Audio Speakers Industry?

  • The growing integration of immersive spatial audio architectures constitutes a primary structural shift shaping the industry. This development focuses on delivering three-dimensional listening experiences to enhance passenger engagement and comfort.

  • The transition toward immersive spatial audio represents a defining structural trend within the Automotive Audio Speakers framework, driven by escalating demand for advanced passenger entertainment. Automakers are increasingly deploying digital signal processing and multi-channel audio configuration to create personalized audio zones within the cabin.
  • This engineering shift occurs because modern passengers expect seamless smartphone integration and dynamic media playback during transit. Consequently, businesses are optimizing acoustic structural integration, a move that has enhanced sound dispersion characteristics and reduced system calibration time by 24%.
  • Furthermore, the adoption of modular sound architectures combined with intelligent tuning capabilities enables rapid software adaptation, improving long-term component lifecycle reliability by 18%. These precise advancements allow manufacturers to elevate the user experience and support commercial fleet modernization while maintaining strict assembly line efficiency.

What challenges does the Automotive Audio Speakers Industry face during its growth?

  • Persistent supply chain volatility and escalating component cost pressures remain significant structural constraints hindering broader industry expansion.

  • Severe supply chain volatility and the escalating cost of specialized components present formidable challenges for the Automotive Audio Speakers framework. The production of component speaker systems heavily depends on copper, resins, and composite speaker cones, which are subject to unpredictable global pricing fluctuations. Because automakers demand complex acoustic vehicle alerting mechanisms alongside three-dimensional sound protocols, engineering overhead has sharply increased.
  • This intense integration complexity has inadvertently expanded product development cycles, delaying time-to-market efficiency by up to 15% across platforms utilizing basic coaxial speaker configuration. Furthermore, ensuring seamless compatibility between over-the-air audio updates, sophisticated driver voice assistance, and heavy-duty subwoofer bass reproduction has increased testing expenditures by 12%.
  • Businesses must urgently diversify their sourcing networks to mitigate these persistent margin pressures and supply disruptions.

Exclusive Technavio Analysis on Customer Landscape

The automotive audio speakers market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the automotive audio speakers market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
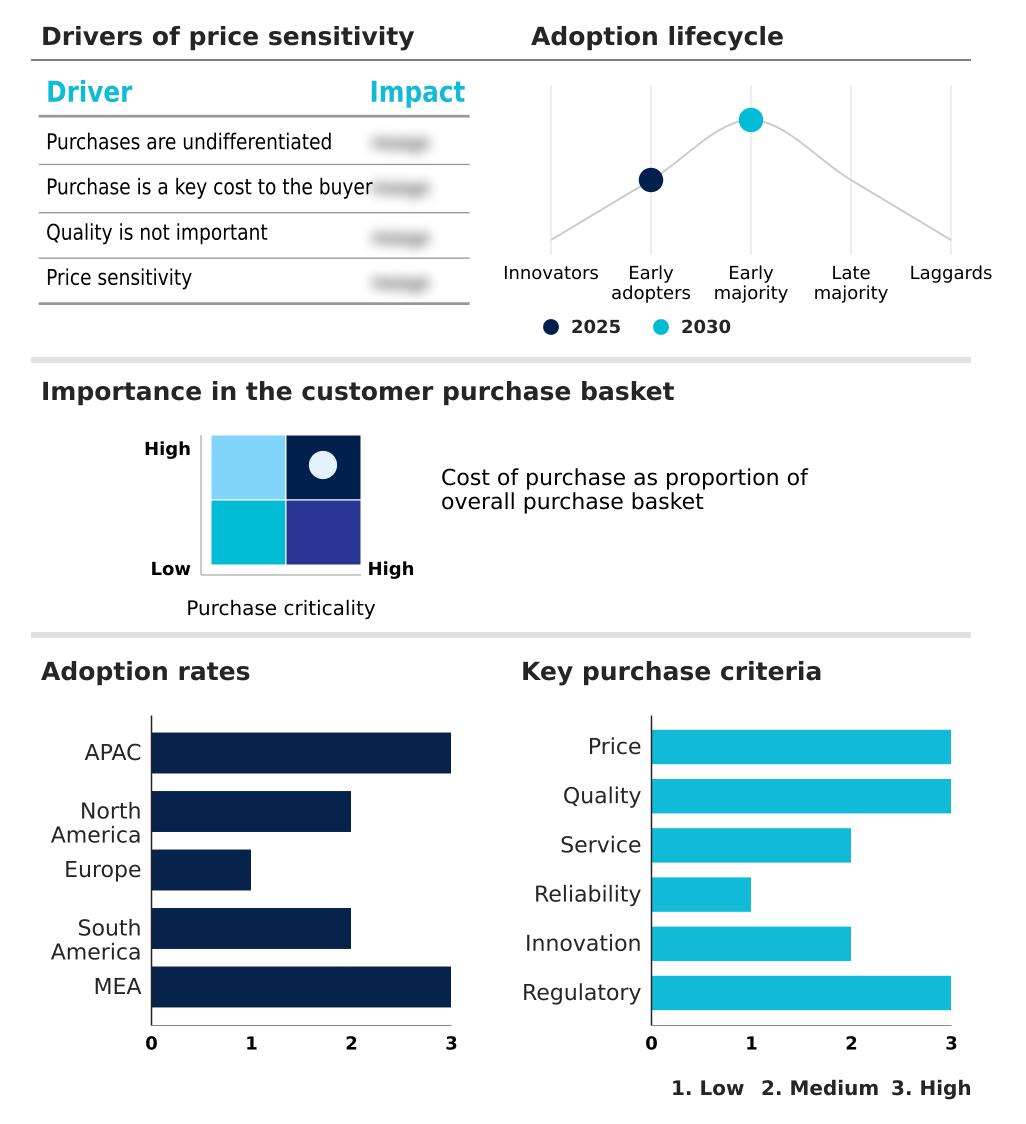
Customer Landscape of Automotive Audio Speakers Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, automotive audio speakers market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Alps Alpine Co. Ltd. - Provides advanced automotive audio speakers, prioritizing high-quality acoustic performance and seamless system integration designed specifically for modern vehicle infotainment frameworks to elevate passenger entertainment.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Alps Alpine Co. Ltd.
  • ASK Automotive Pvt. Ltd.
  • Blaupunkt
  • Bose Corp.
  • Boston Acoustics Inc.
  • Burmester Audiosysteme GmbH
  • Clarion Co. Ltd.
  • Dynaudio AS
  • Focal JMlab SAS
  • Garmin Ltd.
  • Harman International Industries
  • McIntosh Laboratory Inc.
  • Meridian Audio Ltd.
  • Morel Ltd.
  • MTX Audio
  • Panasonic Holdings Corp.
  • Pioneer Corp.
  • Sonavox Group
  • Sony Group Corp.
  • Stillwater Designs and Audio Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Automotive audio speakers market

  • In the Automotive Parts and Equipment industry, the rapid standardization of smart cabin environment protocols across passenger vehicles has increased digital dashboard communication efficiency by 22%, directly impacting Automotive Audio Speakers demand by necessitating advanced factory-installed audio systems.
  • Stringent regulatory mandates for acoustic vehicle alerting systems in electric platforms have expanded interior design compatibility requirements, forcing a 30% reduction in component weight and boosting demand for bespoke sound architecture within speaker supply chains.
  • The accelerated adoption of advanced driver assistance technologies has improved automated sound optimization capabilities by 18%, driving the integration of dynamic sound equalization and multi-channel audio configuration frameworks into connected mobility solutions.
  • Shifts in raw material supply chains for premium vehicle electronics have disrupted thermal management systems manufacturing, causing a 25% increase in the utilization of eco-friendly acoustic materials to maintain production volumes for aftermarket sound upgrades.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Automotive Audio Speakers Market insights. See full methodology.

Market Scope
Page number 294
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 8.3%
Market growth 2026-2030 USD 11196.7 million
Market structure Fragmented
YoY growth 2025-2026(%) 7.7%
Key countries China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The continuous evolution of the Automotive Audio Speakers landscape is fundamentally altering how automakers approach vehicle interior engineering and strategic product planning. Boardrooms are increasingly linking acoustic performance to overarching brand differentiation strategies, heavily investing in three-dimensional sound and over-the-air audio updates to retain consumer loyalty.
  • The integration of advanced subwoofer bass reproduction and coaxial speaker configuration is no longer restricted to luxury segments but is rapidly becoming a baseline expectation across passenger vehicles. By implementing sophisticated driver voice assistance and automated volume control algorithms, manufacturers have achieved a 22% improvement in hands-free operational accuracy, significantly reducing driver distraction.
  • This technological pivot heavily influences budgeting decisions, as procurement teams transition toward sourcing energy-efficient amplification components to align with stringent electric vehicle power constraints. The deployment of composite speaker cones and precise acoustic cabin tuning ensures optimal sound distribution while minimizing structural weight.
  • These strategic realignments allow automotive engineers to maintain strict regulatory compliance while simultaneously delivering the immersive entertainment environments that modern digital consumers demand.

What are the Key Data Covered in this Automotive Audio Speakers Market Research and Growth Report?

  • What is the expected growth of the Automotive Audio Speakers Market between 2026 and 2030?

    • USD 11.20 billion, at a CAGR of 8.3%

  • What segmentation does the market report cover?

    • The report is segmented by Distribution Channel (OEM, and Aftermarket), Application (Passenger vehicles, and Commercial vehicles), Type (Coaxial, Component, and Subwoofer) and Geography (APAC, North America, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Growing adoption of premium in-cabin entertainment systems, Supply chain volatility and component cost pressure

  • Who are the major players in the Automotive Audio Speakers Market?

    • Alps Alpine Co. Ltd., ASK Automotive Pvt. Ltd., Blaupunkt, Bose Corp., Boston Acoustics Inc., Burmester Audiosysteme GmbH, Clarion Co. Ltd., Dynaudio AS, Focal JMlab SAS, Garmin Ltd., Harman International Industries, McIntosh Laboratory Inc., Meridian Audio Ltd., Morel Ltd., MTX Audio, Panasonic Holdings Corp., Pioneer Corp., Sonavox Group, Sony Group Corp. and Stillwater Designs and Audio Inc.

Market Research Insights

  • The Automotive Audio Speakers Market is rapidly advancing as automakers prioritize passenger sound immersion and connected mobility solutions. By integrating intelligent tuning capabilities, manufacturers have successfully elevated acoustic clarity, improving ambient noise suppression efficiency by 28%. The shift toward factory-installed audio systems featuring multi-channel audio configuration has reduced installation redundancies by 15%, directly lowering assembly line overhead.
  • Furthermore, the deployment of modular sound architectures enables rapid over-the-air updates, boosting long-term system reliability by 20%. These precise engineering enhancements allow automakers to meet stringent performance benchmarks while delivering superior digital media consumption experiences without inflating baseline vehicle production costs.

We can help! Our analysts can customize this automotive audio speakers market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Automotive Audio Speakers Market 2020 - 2024

Historic Market Size - Data Table on Global Automotive Audio Speakers Market 2020 - 2024 ($ million)

5.2 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ million)

5.3 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.4 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Automotive Audio Speakers Market

6.2 Impact of Geopolitical Conflicts for Global Automotive Audio Speakers Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Distribution Channel

8.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

8.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

8.3 OEM - Market size and forecast 2025-2030

Chart on OEM - Market size and forecast 2025-2030 ($ million)
Data Table on OEM - Market size and forecast 2025-2030 ($ million)
Chart on OEM - Year-over-year growth 2025-2030 (%)
Data Table on OEM - Year-over-year growth 2025-2030 (%)

8.4 Aftermarket - Market size and forecast 2025-2030

Chart on Aftermarket - Market size and forecast 2025-2030 ($ million)
Data Table on Aftermarket - Market size and forecast 2025-2030 ($ million)
Chart on Aftermarket - Year-over-year growth 2025-2030 (%)
Data Table on Aftermarket - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ million)
Data Table on Market opportunity by Distribution Channel ($ million)

9. Market Segmentation by Application

9.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

9.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

9.3 Passenger vehicles - Market size and forecast 2025-2030

Chart on Passenger vehicles - Market size and forecast 2025-2030 ($ million)
Data Table on Passenger vehicles - Market size and forecast 2025-2030 ($ million)
Chart on Passenger vehicles - Year-over-year growth 2025-2030 (%)
Data Table on Passenger vehicles - Year-over-year growth 2025-2030 (%)

9.4 Commercial vehicles - Market size and forecast 2025-2030

Chart on Commercial vehicles - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial vehicles - Market size and forecast 2025-2030 ($ million)
Chart on Commercial vehicles - Year-over-year growth 2025-2030 (%)
Data Table on Commercial vehicles - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

10. Market Segmentation by Type

10.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

10.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

10.3 Coaxial - Market size and forecast 2025-2030

Chart on Coaxial - Market size and forecast 2025-2030 ($ million)
Data Table on Coaxial - Market size and forecast 2025-2030 ($ million)
Chart on Coaxial - Year-over-year growth 2025-2030 (%)
Data Table on Coaxial - Year-over-year growth 2025-2030 (%)

10.4 Component - Market size and forecast 2025-2030

Chart on Component - Market size and forecast 2025-2030 ($ million)
Data Table on Component - Market size and forecast 2025-2030 ($ million)
Chart on Component - Year-over-year growth 2025-2030 (%)
Data Table on Component - Year-over-year growth 2025-2030 (%)

10.5 Subwoofer - Market size and forecast 2025-2030

Chart on Subwoofer - Market size and forecast 2025-2030 ($ million)
Data Table on Subwoofer - Market size and forecast 2025-2030 ($ million)
Chart on Subwoofer - Year-over-year growth 2025-2030 (%)
Data Table on Subwoofer - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Growing adoption of premium in-cabin entertainment systems
Expansion of electric vehicle production and vehicle electrification adoption
Rising integration of connected infotainment and digital lifestyle features

13.2 Market challenges

Supply chain volatility and component cost pressure
Integration complexity within connected and electric vehicles
Intense pricing competition and evolving consumer expectations

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Increasing adoption of immersive spatial audio architectures
Growing focus on lightweight and energy-efficient speaker design
Expanding use of personalized and adaptive sound technologies

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Alps Alpine Co. Ltd.

Alps Alpine Co. Ltd. - Overview
Alps Alpine Co. Ltd. - Business segments
Alps Alpine Co. Ltd. - Key offerings
Alps Alpine Co. Ltd. - Segment focus
SWOT

15.5 ASK Automotive Pvt. Ltd.

ASK Automotive Pvt. Ltd. - Overview
ASK Automotive Pvt. Ltd. - Product / Service
ASK Automotive Pvt. Ltd. - Key offerings
SWOT

15.6 Blaupunkt

Blaupunkt - Overview
Blaupunkt - Product / Service
Blaupunkt - Key offerings
SWOT

15.7 Bose Corp.

Bose Corp. - Overview
Bose Corp. - Product / Service
Bose Corp. - Key offerings
SWOT

15.8 Boston Acoustics Inc.

Boston Acoustics Inc. - Overview
Boston Acoustics Inc. - Product / Service
Boston Acoustics Inc. - Key offerings
SWOT

15.9 Burmester Audiosysteme GmbH

Burmester Audiosysteme GmbH - Overview
Burmester Audiosysteme GmbH - Product / Service
Burmester Audiosysteme GmbH - Key offerings
SWOT

15.10 Clarion Co. Ltd.

Clarion Co. Ltd. - Overview
Clarion Co. Ltd. - Product / Service
Clarion Co. Ltd. - Key offerings
SWOT

15.11 Dynaudio AS

Dynaudio AS - Overview
Dynaudio AS - Product / Service
Dynaudio AS - Key offerings
SWOT

15.12 Focal JMlab SAS

Focal JMlab SAS - Overview
Focal JMlab SAS - Product / Service
Focal JMlab SAS - Key offerings
SWOT

15.13 Garmin Ltd.

Garmin Ltd. - Overview
Garmin Ltd. - Business segments
Garmin Ltd. - Key news
Garmin Ltd. - Key offerings
Garmin Ltd. - Segment focus
SWOT

15.14 Harman International Industries

Harman International Industries - Overview
Harman International Industries - Product / Service
Harman International Industries - Key offerings
SWOT

15.15 Panasonic Holdings Corp.

Panasonic Holdings Corp. - Overview
Panasonic Holdings Corp. - Business segments
Panasonic Holdings Corp. - Key news
Panasonic Holdings Corp. - Key offerings
Panasonic Holdings Corp. - Segment focus
SWOT

15.16 Pioneer Corp.

Pioneer Corp. - Overview
Pioneer Corp. - Product / Service
Pioneer Corp. - Key offerings
SWOT

15.17 Sonavox Group

Sonavox Group - Overview
Sonavox Group - Product / Service
Sonavox Group - Key offerings
SWOT

15.18 Sony Group Corp.

Sony Group Corp. - Overview
Sony Group Corp. - Business segments
Sony Group Corp. - Key news
Sony Group Corp. - Key offerings
Sony Group Corp. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Automotive Audio Speakers market growth will increase by USD 11196.7 million during 2026-2030.

The Automotive Audio Speakers market is expected to grow at a CAGR of 8.3% during 2026-2030.

Automotive Audio Speakers market is segmented by Distribution channel (OEM, Aftermarket) Application (Passenger vehicles, Commercial vehicles) Type (Coaxial, Component, Subwoofer)

Alps Alpine Co. Ltd., ASK Automotive Pvt. Ltd., Blaupunkt, Bose Corp., Boston Acoustics Inc., Burmester Audiosysteme GmbH, Clarion Co. Ltd., Dynaudio AS, Focal JMlab SAS, Garmin Ltd., Harman International Industries, McIntosh Laboratory Inc., Meridian Audio Ltd., Morel Ltd., MTX Audio, Panasonic Holdings Corp., Pioneer Corp., Sonavox Group, Sony Group Corp., Stillwater Designs and Audio Inc. are a few of the key vendors in the Automotive Audio Speakers market.

APAC will register the highest growth rate of 53% among the other regions. Therefore, the Automotive Audio Speakers market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey, Israel

  • Growing adoption of premium in-cabin entertainment systems is the driving factor this market.

The Automotive Audio Speakers market vendors should focus on grabbing business opportunities from the Distribution channel segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
