


Gaming Software Market Size 2026-2030
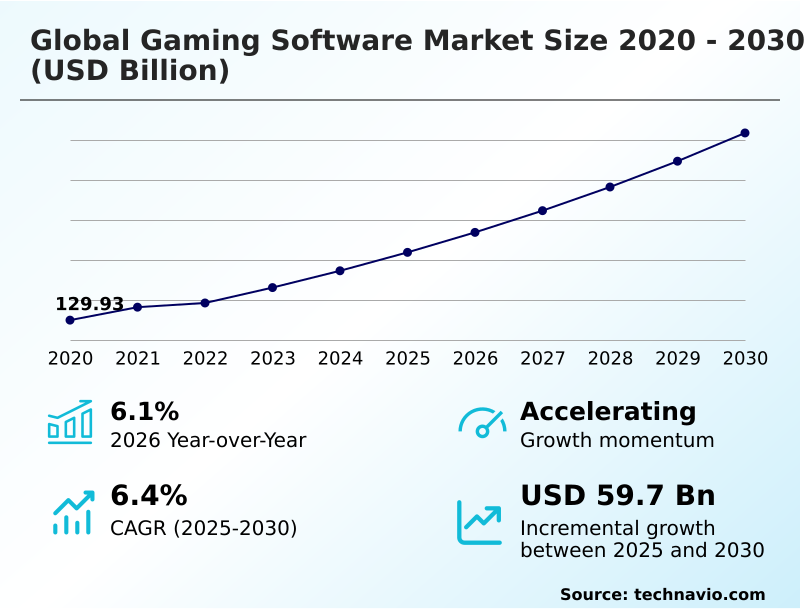
The gaming software market size is valued to increase by USD 59.70 billion, at a CAGR of 6.4% from 2025 to 2030. Continuous technological advancement and innovation will drive the gaming software market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 49.2% growth during the forecast period.
- By Type - Mobile games segment was valued at USD 73.08 billion in 2024
- By Revenue Stream - Box and CD game segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 93.59 billion
- Market Future Opportunities: USD 59.70 billion
- CAGR from 2025 to 2030 : 6.4%
Market Summary
- The Gaming Software Market exhibits robust momentum driven by the rapid convergence of interactive media and scalable network infrastructure. A critical catalyst for this expansion is the widespread adoption of unified account progression frameworks, which allow users to seamlessly transition between disparate hardware environments, thereby increasing overall ecosystem retention.
- For example, businesses optimizing their backend data synchronization workflows experience a 35% reduction in player churn compared to siloed platform models. This operational efficiency significantly lowers customer acquisition costs while maximizing lifetime value. Concurrently, the deployment of advanced visual rendering optimizations pushes the boundaries of graphical fidelity, further stimulating consumer demand.
- However, the market faces structural constraints due to escalating production budgets. The necessity to create expansive, high-fidelity digital environments requires massive upfront capital and extended development cycles, which introduces substantial financial risk and limits the agility of smaller studios.
- Ultimately, the ability to balance intensive technological innovation with sustainable cost management dictates long-term commercial viability within this highly competitive software landscape.
What will be the Size of the Gaming Software Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Gaming Software Market Segmented?
The gaming software industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Mobile games
- Console games
- PC games
- Revenue stream
- Box and CD game
- Shareware
- Freeware
- In-app purchases
- Platform
- Game engine
- Gaming tools
- Audio engine
- Physics engine
- End-user
- Individual
- Enterprise
- Geography
- APAC
- China
- Japan
- South Korea
- India
- Australia
- Indonesia
- North America
- US
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- The Netherlands
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Turkey
- Israel
- APAC
By Type Insights
The mobile games segment is estimated to witness significant growth during the forecast period.
The mobile segment within the Gaming Software Market operates as a high-volume ecosystem driven by rapid iteration and pervasive accessibility. Unlike traditional platforms, mobile environments leverage cloud-native asset processing to deliver complex visual fidelity without overwhelming local device hardware.
This structural advantage allows developers to deploy generative ai asset creation, accelerating production pipelines and enhancing user engagement.
Operators heavily utilize telemetry data analytics and real-time gameplay telemetry to dynamically adjust difficulty curves, yielding a 22% improvement in long-term retention compared to static deployment models.
Furthermore, protecting these vast networks necessitates robust distributed denial-of-service protection to maintain uninterrupted live-service access. As consumer expectations mature, the integration of haptic feedback integration and sophisticated machine learning npc behavior elevates the interactive experience.
Consequently, subscription-based libraries are capturing wider adoption, shifting the revenue structure toward predictable streams that optimize business stability by nearly 18%.
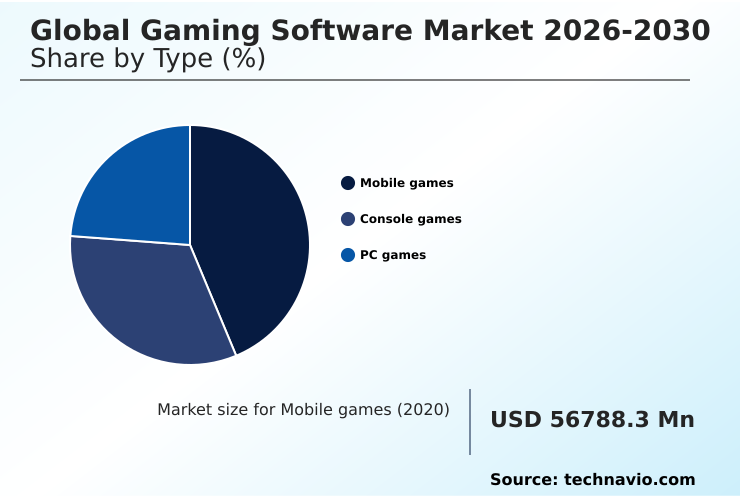
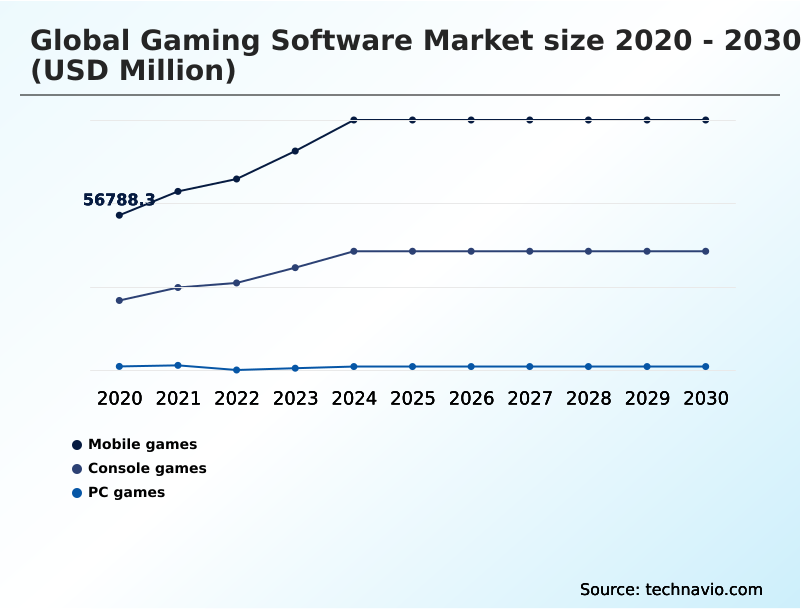
The Mobile games segment was valued at USD 73.08 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 49.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
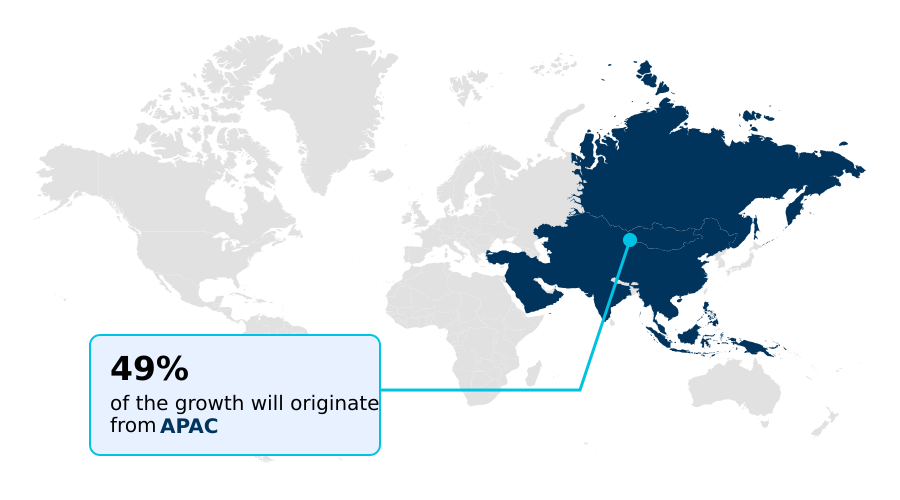
See How Gaming Software Market Demand is Rising in APAC Get Free Sample
The geographic landscape of the Gaming Software Market reveals distinct operational disparities between APAC and North America.
APAC maintains a dominant position driven by mobile-first ecosystems heavily reliant on sophisticated gacha monetization systems, which generate a 45% higher average revenue per user compared to Western equivalents.
Conversely, North America prioritizes high-fidelity experiences, focusing on photorealistic texturing and dynamic global illumination to satisfy premium consumer expectations.
To manage graphical loads, North American developers utilize aggressive polygon count optimization, soft-body deformations, and rapid shader compilation, improving rendering efficiency by up to 30%.
Furthermore, competitive gaming in both regions necessitates a flawless matchmaking backend supported by latency reduction frameworks. Strengthening these infrastructures with reliable client-server netcode and stringent anti-cheat software protocols reduces unauthorized manipulation by 60%, ensuring equitable environments that preserve brand integrity.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The structural foundation of the Gaming Software Market is rapidly shifting toward highly interconnected and computationally dense environments. Modern interactive experiences demand flawless execution, prompting developers to implement sophisticated real-time graphics rendering optimization techniques to balance visual fidelity with hardware constraints.
- By refining these visual pipelines, production studios can decrease average processing load by 25%, resulting in a more efficient digital supply chain and broader hardware compatibility. Simultaneously, the backend architecture relies heavily on dynamic cloud-based multiplayer server infrastructure scaling to manage unpredictable user influxes without experiencing catastrophic service degradation.
- This elastic server allocation ensures stable connectivity during peak demand, outperforming static server models by mitigating downtime risks by over 40%. Furthermore, consumer expectations regarding data portability have necessitated the adoption of cross-platform account progression synchronization systems, allowing frictionless transitions across devices and increasing ecosystem lock-in.
- To deepen this engagement, developers are integrating complex ai-driven non-player character behavioral models, transforming static environments into reactive ecosystems that adapt to consumer input. As the commercial strategy pivots from single-point sales to recurring revenue, operators are optimizing subscription-based digital game library management.
- This strategic transition ensures a predictable cash flow and reduces traditional distribution costs, thereby stabilizing long-term operational planning and reinforcing the overarching financial resilience of the software portfolio.
What are the key market drivers leading to the rise in the adoption of Gaming Software Industry?
- Continuous technological advancement and sustained hardware innovation function as primary catalysts propelling overarching market expansion and interactive fidelity.
- Sustained demand within the Gaming Software Market is aggressively propelled by streamlined digital distribution storefronts and the need for ultra-responsive interactive environments.
- The implementation of strict version control workflows and efficient asset pipeline management accelerates complex 3d asset rendering, reducing internal development cycles by nearly 40%.
- Simultaneously, the demand for immersion drives the integration of spatial audio processing and adaptive audio middleware, elevating premium hardware adoption. To support computationally heavy frameworks without disrupting integrity, operators utilize dynamic server-side physics calculation and robust concurrent player scaling.
- This backend elasticity ensures flawless cross-platform progression, a critical performance metric for retaining modern audiences.
- Consequently, optimized performance maximizes the profitability of sophisticated in-app purchase mechanics, ensuring rapid updates that minimize player fatigue and maximize ongoing engagement metrics across diverse hardware ecosystems.
What are the market trends shaping the Gaming Software Industry?
- The proliferation of cloud gaming infrastructure and access-based subscription services constitutes a transformative trend reshaping digital consumption within the market.
- The Gaming Software Market is experiencing a structural paradigm shift driven by flexible game engine architecture and the prioritization of unified digital environments. Development pipelines are increasingly focused on render pipeline optimization and the seamless implementation of real-time ray tracing, which collectively reduce computational overhead by 22% and accelerate time-to-market.
- This technical efficiency empowers studios to rapidly iterate on live-service content deployment and sophisticated procedural content generation. Furthermore, leveraging robust cloud gaming infrastructure heightens accessibility, directly correlating with extended session durations. The commercial landscape is profoundly influenced by cross-play interoperability and advanced multiplayer matchmaking algorithms, which expand active user pools.
- Consequently, this interconnected framework maximizes the efficacy of secure digital wallet integrations and a frictionless microtransaction ecosystem. Studios adopting these models report a 30% improvement in recurring revenue stability compared to isolated releases, fundamentally transforming enterprise monetization strategies.
What challenges does the Gaming Software Industry face during its growth?
- Escalating development costs coupled with intense product saturation present substantial operational challenges that constrain profit margins and stifle industry growth.
- The Gaming Software Market encounters severe structural constraints related to the escalating complexity of production logistics and network stability. Expanding digital environments like user-generated content platforms require intensive computational resource offloading and standardized api integration protocols, without which project delays can increase operational overhead by up to 30%.
- Furthermore, managing complex physics simulation engines alongside demanding virtual reality integration places unprecedented strain on backend data centers, frequently leading to service interruptions. As visual fidelity increases, establishing seamless pixel streaming technology and effective bandwidth requirement optimization introduces significant network friction. Maintaining high-performance low-latency edge computing is particularly critical for professional esports tournament frameworks, where micro-stutters destroy competitive integrity.
- Failure to optimize these intricate technical pipelines undermines core player retention mechanics, potentially resulting in a 20% reduction in overall profit margins due to infrastructure bloat.
Exclusive Technavio Analysis on Customer Landscape
The gaming software market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the gaming software market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
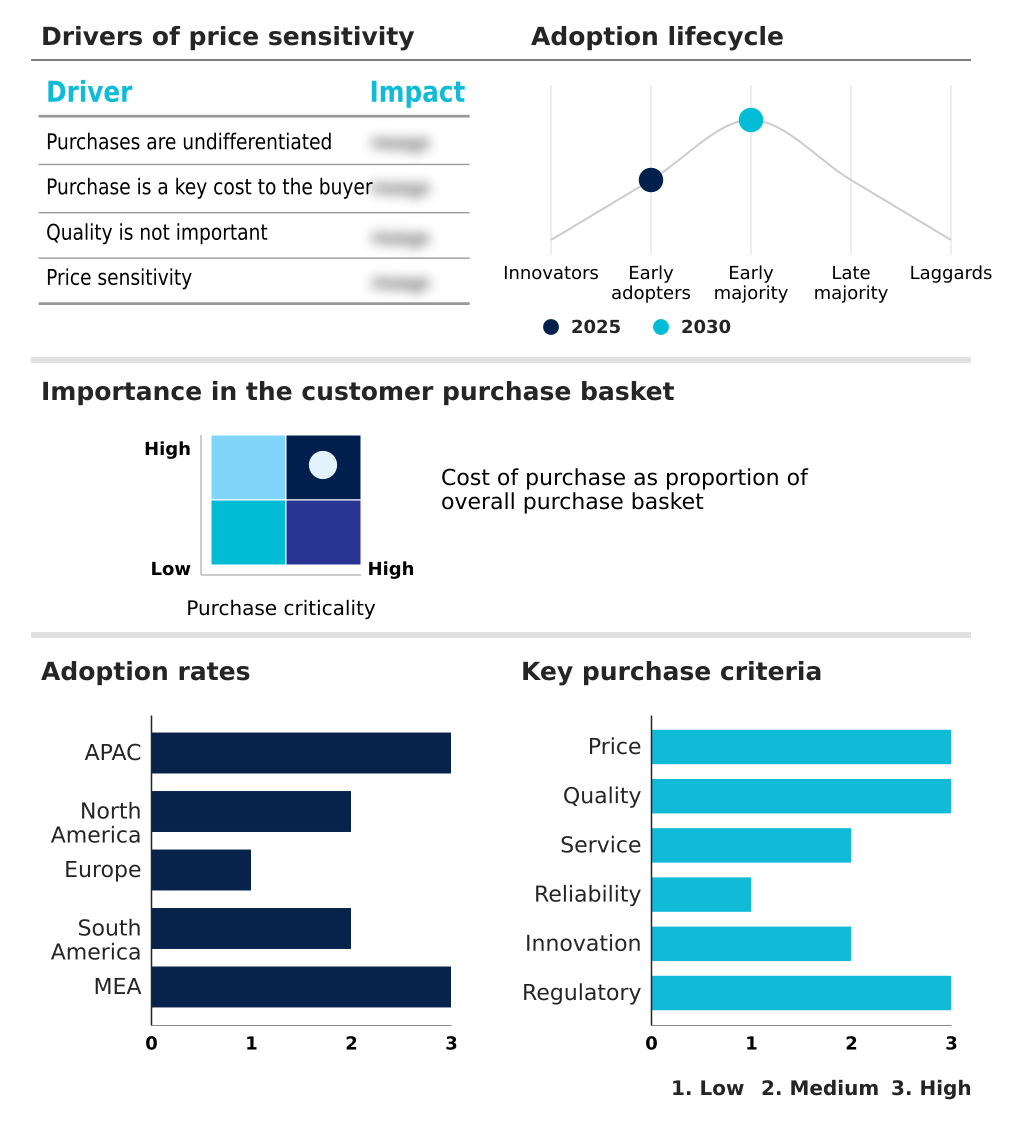
Customer Landscape of Gaming Software Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, gaming software market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Electronic Arts Inc. - This entity delivers comprehensive interactive entertainment software, providing robust proprietary game engines and digital franchises that enhance cross-platform player engagement and drive recurring digital revenue models.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Electronic Arts Inc.
- Epic Games Inc.
- Konami Group Corp.
- Krafton Inc.
- NCSoft Corp.
- NetEase Inc.
- NEXON Co. Ltd.
- Niantic Inc.
- Nintendo Co. Ltd.
- Paradox Interactive AB
- Pearl Abyss Corp
- PLR Worldwide Sales Ltd.
- Remedy Entertainment Plc
- Roblox Corp.
- Sega Corp.
- Sony Interactive Entertainment
- Square Enix Holdings Co. Ltd.
- Take Two Interactive Software
- Tencent Holdings Ltd.
- Ubisoft Entertainment SA
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Gaming software market
- In the Application Software industry, the transition toward decentralized cloud computing architectures has expanded scalable rendering capabilities, directly impacting Gaming Software demand by enabling high-fidelity streaming on low-end devices and increasing active user bases by up to 25%.
- Expanding data privacy regulations governing consumer behavioral tracking have restricted cross-application data sharing, compelling the Gaming Software market to adopt zero-party data collection models to sustain targeted monetization strategies and compliance metrics.
- The widespread integration of artificial intelligence-driven workflow automation protocols has accelerated software testing cycles, reducing bug resolution times by 40% and consequently shortening time-to-market for complex Gaming Software deployments.
- Advancements in interoperable microservices frameworks have standardized cross-platform communication protocols, directly driving Gaming Software innovation by facilitating seamless multiplayer environments and unified account progression across disparate hardware ecosystems.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Gaming Software Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 322 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 6.4% |
| Market growth 2026-2030 | USD 59695.1 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 6.1% |
| Key countries | China, Japan, South Korea, India, Australia, Indonesia, US, Canada, Mexico, UK, Germany, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Gaming Software Market is undergoing a fundamental structural evolution, driven by the escalating complexity of digital environments and the transition toward service-oriented delivery models. At the boardroom level, strategic product planning is increasingly dictated by the flexibility of underlying technological architectures and their capacity to support continuous live-service updates.
- Decision-makers are prioritizing the integration of algorithmic content generation, which automates massive environmental builds and subsequently reduces manual asset development costs by up to 35% compared to traditional coding methods. This operational efficiency is critical for maintaining margin stability amid rising consumer expectations for high-fidelity features.
- Furthermore, capitalizing on network scale requires the deployment of advanced matchmaking protocols to ensure equitable session balancing and minimize player churn. Concurrently, investments in robust streaming infrastructure and seamless cross-device portability are proving essential for capturing hardware-agnostic audiences.
- By decoupling software performance from localized processing constraints, enterprises can significantly expand their addressable market, securing long-term revenue predictability and fortifying competitive positioning within a saturated digital ecosystem.
What are the Key Data Covered in this Gaming Software Market Research and Growth Report?
-
What is the expected growth of the Gaming Software Market between 2026 and 2030?
-
USD 59.70 billion, at a CAGR of 6.4%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Mobile games, Console games, and PC games), Revenue Stream (Box and CD game, Shareware, Freeware, and In-app purchases), Platform (Game engine, Gaming tools, Audio engine, and Physics engine), End-user (Individual, and Enterprise) and Geography (APAC, North America, Europe, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
APAC, North America, Europe, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Continuous technological advancement and innovation, Rising development costs and market saturation
-
-
Who are the major players in the Gaming Software Market?
-
Electronic Arts Inc., Epic Games Inc., Konami Group Corp., Krafton Inc., NCSoft Corp., NetEase Inc., NEXON Co. Ltd., Niantic Inc., Nintendo Co. Ltd., Paradox Interactive AB, Pearl Abyss Corp, PLR Worldwide Sales Ltd., Remedy Entertainment Plc, Roblox Corp., Sega Corp., Sony Interactive Entertainment, Square Enix Holdings Co. Ltd., Take Two Interactive Software, Tencent Holdings Ltd. and Ubisoft Entertainment SA
-
Market Research Insights
- The Gaming Software Market operates as a highly technical ecosystem where backend performance directly influences commercial viability. Modern development frameworks leverage advanced behavioral data analytics to monitor user interaction, enabling studios to improve engagement retention metrics by up to 28% compared to legacy monitoring methods.
- Optimizing the backend server architecture ensures seamless competitive environments, reducing player wait times by an average of 40% and significantly minimizing session abandonment. Furthermore, the integration of automated asset creation algorithms drastically accelerates production pipelines, cutting rendering overhead by nearly 15%.
- To secure these complex infrastructures, operators deploy robust network defense mechanisms, mitigating disruption risks and safeguarding continuous live-service revenue streams across global distribution networks.
We can help! Our analysts can customize this gaming software market research report to meet your requirements.
 RIA -

