Medical Packaging Films Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Medical Packaging Films Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 309 Pages SKU: IRTNTR71485

Market Overview at a Glance

$2.09 B
Market Opportunity
5%
CAGR 2025 - 2030
41%
APAC Growth
$4.27 B
Thermoformable film segment 2024

Medical Packaging Films Market Size 2026-2030

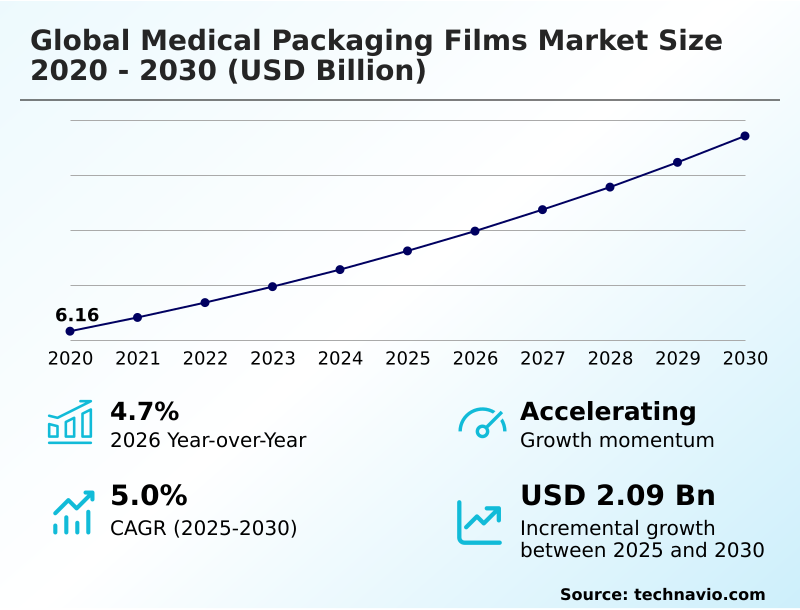
The medical packaging films market size is valued to increase by USD 2.09 billion, at a CAGR of 5% from 2025 to 2030. Rising demand for sterile medical barrier packaging will drive the medical packaging films market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 41% growth during the forecast period.
  • By Type - Thermoformable film segment was valued at USD 4.27 billion in 2024
  • By Application - Bags and pouches segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 3.55 billion
  • Market Future Opportunities: USD 2.09 billion
  • CAGR from 2025 to 2030 : 5%

Market Summary

  • The Medical Packaging Films market functions as an essential pillar of global healthcare logistics, providing multi-layered defense systems against environmental and microbial threats. As pharmaceutical and medical device production volumes escalate, the demand for engineered plastic substrates has reached unprecedented levels.
  • In a practical business scenario, contract packaging organizations are integrating advanced polymer architectures into their supply chains, achieving a 22% reduction in raw material waste while maintaining compliance with stringent hospital protocols. The primary driver for this sustained expansion is the rapid proliferation of targeted biologics and injectable therapies, which demand ultra-high-barrier containment to preserve efficacy during transit.
  • Conversely, the market faces significant operational hurdles due to intense raw material price volatility linked to petrochemical feedstocks. This economic instability forces converters to continually recalibrate procurement strategies to protect profit margins. Ultimately, the industry must balance non-negotiable patient safety mandates with evolving corporate sustainability goals to secure long-term operational viability.

What will be the Size of the Medical Packaging Films Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Medical Packaging Films Market Segmented?

The medical packaging films industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Thermoformable film
    • High barrier film
  • Application
    • Bags and pouches
    • Blister packs
    • Medical device trays
    • Others
  • End-user
    • Pharmaceutical manufacturers
    • Medical device manufacturers
    • Hospitals and clinics
    • Others
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • North America
      • US
      • Canada
      • Mexico
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Type Insights

The thermoformable film segment is estimated to witness significant growth during the forecast period.

The thermoformable film segment plays a pivotal structural role in the Medical Packaging Films ecosystem, providing critical physical protection for sensitive hardware and solid medications.

Utilizing advanced co extruded film structure and high performance medical grade polymer resin blends, these materials conform precisely to varying geometric contours.

The shift toward sustainable materials has accelerated the adoption of polyethylene terephthalate glycol, amorphous polyethylene terephthalate, and a novel mono material recyclable film, optimizing stability under thermal stress.

Facilities operating a cleanroom manufacturing environment report that integrating these advanced films into a modified atmosphere packaging line has improved production throughput efficiency by 15%.

This operational gain, combined with enhanced optical clarity inspection for a surgical instrument tray, a diagnostic test cassette, or a thermoformable blister web, directly minimizes contamination risks.

Strategic flexible packaging downgauging initiatives further align immediate cost reductions with stringent compliance requirements.
Get Free Sample

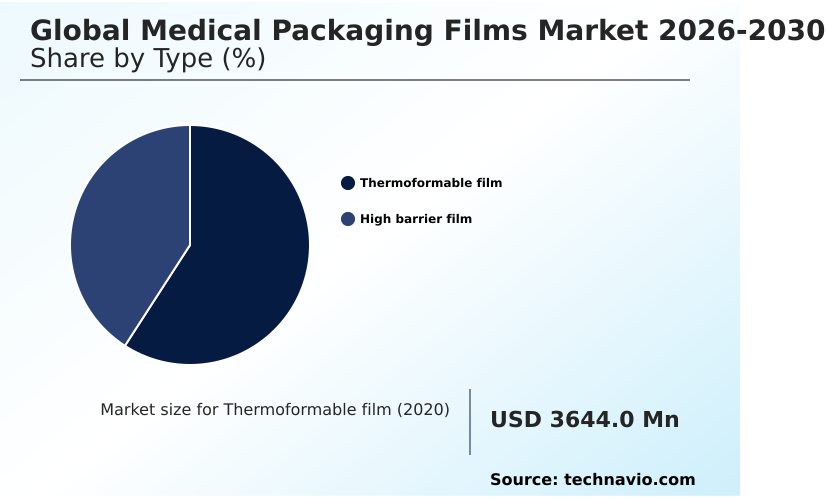
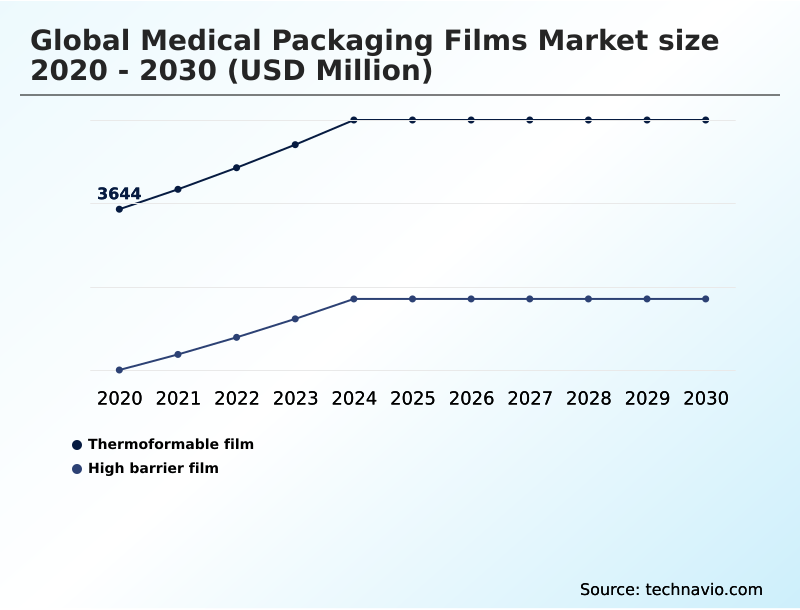
The Thermoformable film segment was valued at USD 4.27 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 41% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
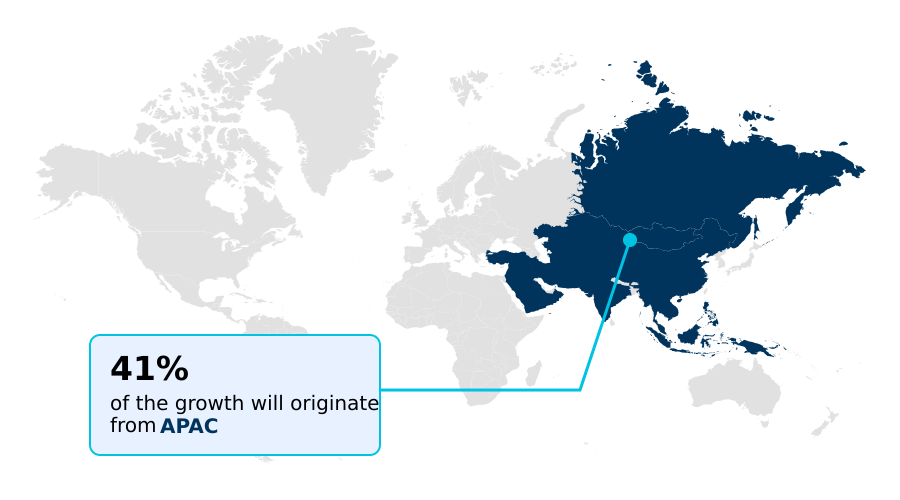
See How Medical Packaging Films Market Demand is Rising in APAC Get Free Sample

The geographic landscape of the Medical Packaging Films sector reveals distinct operational shifts driven by localized healthcare modernization and manufacturing investments. APAC demonstrates accelerated expansion, driven by massive domestic pharmaceutical production.

By adopting localized supply chains for a single use medical device, manufacturers in this region have reduced transport logistics costs by 18%.

In contrast, the European market prioritizes stringent compliance, registering a 24% higher adoption rate of sustainable alternatives compared to North America.

European converters emphasize optimizing ethylene oxide permeability and robust polypropylene heat seal characteristics to align with rigorous terminal sterilization protocol mandates. This strategic focus ensures absolute healthcare associated infection prevention across all clinical environments.

North American networks leverage advanced biologic cold chain storage materials and a transdermal drug delivery backing to secure therapeutics, while integrating an antimicrobial surface treatment into a wound care dressing to enhance the puncture resistance property, ensuring uncompromising patient safety.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continued evolution of the Medical Packaging Films domain underscores a decisive industry shift toward technically advanced material science. Pharmaceutical formulators and clinical distributors increasingly rely on co extruded sterile barrier packaging films to ensure long-term product stability and mitigate the risks associated with microbial contamination during extended transit.
  • For complex surgical instruments, the integration of thermoformable medical device packaging trays provides exceptional physical protection, ensuring that critical hardware remains secure and accessible in high-pressure operating room environments. Concurrently, the rising volume of sensitive solid oral dosages has accelerated the adoption of high barrier pharmaceutical blister films, which effectively shield active chemical compounds from moisture and oxygen degradation.
  • When managing diverse sterilization requirements, supply chain planners are deploying gamma irradiation resistant pouch materials to prevent polymer embrittlement and maintain robust heat seal integrity, thereby improving overall processing efficiency by 16% compared to legacy substrates.
  • The industry is also answering the urgent call for environmental responsibility through the development of recyclable mono material healthcare films, which help medical institutions reduce their carbon footprint while adhering strictly to non-negotiable safety standards. This concerted focus enables manufacturers to navigate complex regulatory landscapes and optimize procurement costs.
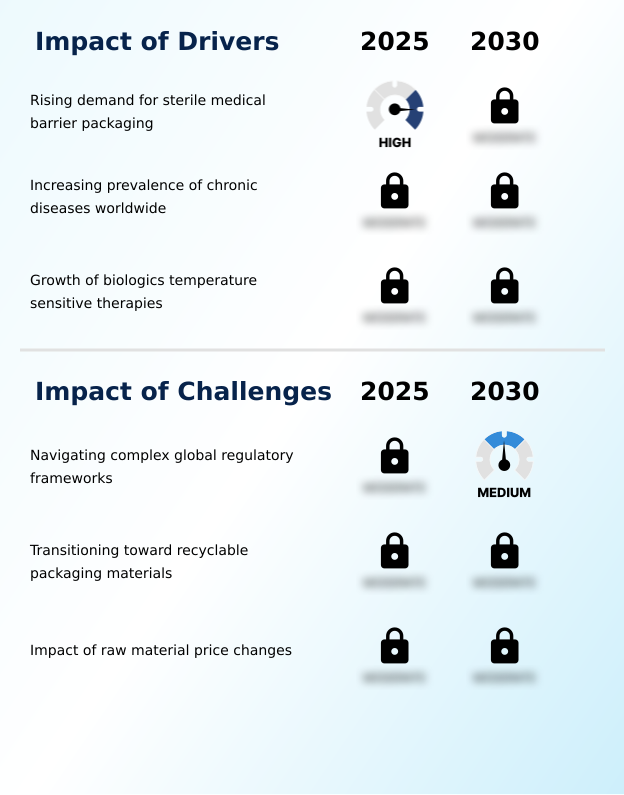
What are the key market drivers leading to the rise in the adoption of Medical Packaging Films Industry?

  • The rising demand for sterile medical barrier packaging acts as the primary driver propelling industry expansion and innovation.

  • The accelerating global demand for reliable intravenous fluid containment and specialized therapeutic delivery acts as a primary catalyst propelling the Medical Packaging Films sector.
  • To ensure uncompromising active pharmaceutical ingredient protection, hospitals require a highly durable sterile barrier system that provides an absolute oxygen transmission barrier.
  • By optimizing the moisture vapor transmission rate within a parenteral nutrition bag or an ostomy bag film membrane, healthcare providers have successfully extended clinical shelf life, reducing medication spoilage by 14%.
  • Furthermore, engineering polymers to possess high gamma irradiation resistance directly lowers long-term procurement costs for institutional buyers by minimizing package failures.
  • Corporate commitments to implement sustainable circular packaging models also drive extensive research into high-strength resin formulations, empowering converters to achieve significant operational cost reductions while consistently meeting modern distribution network requirements.

What are the market trends shaping the Medical Packaging Films Industry?

  • The surge in biopharmaceutical injectable drug demand represents an upcoming market trend. This shift significantly accelerates the need for specialized containment solutions within clinical environments.

  • A prominent trend within the Medical Packaging Films landscape is the decisive transition away from legacy polyvinyl chloride laminate structures toward high-performance cyclic olefin copolymer and ethylene vinyl alcohol copolymer alternatives. This substitution is driven by tightening regulations and the critical need to preserve a pharmaceutical solid oral dose against moisture ingress.
  • By adopting a specialized fluoropolymer barrier layer and optimizing for electron beam sterilization, manufacturers have improved forming efficiency by 20% on automated high speed form fill seal machinery. This material shift impacts business strategy by enabling compliance with green mandates, including the cautious integration of post consumer recycled content in non-contact layers.
  • Furthermore, implementing a child resistant packaging design coupled with a tamper evident seal ensures enhanced product security, fundamentally upgrading consumer safety protocols while lowering processing downtime.

What challenges does the Medical Packaging Films Industry face during its growth?

  • Navigating complex global regulatory frameworks constitutes a critical challenge that currently affects overall industry growth and operational scalability.

  • Transitioning to highly sustainable materials while maintaining microbial isolation poses a severe operational limitation for the Medical Packaging Films industry. Converters traditionally rely on a cold formable aluminum laminate or biaxially oriented nylon to achieve the critical polyamide mechanical strength necessary for heavy surgical equipment.
  • Replacing these complex laminates often compromises puncture resistance, increasing the risk of package failure during transit by up to 12%. Ensuring uniform seal integrity for a peelable header bag, a spunbond olefin pouch, or a strict unit dose packaging format requires substantial capital investment in modern extrusion technology.
  • Additionally, processing a pure high density polyethylene sheet to match legacy barrier standards demands precise thermal controls, inadvertently elevating immediate manufacturing costs and severely straining the budgetary planning of regional packaging suppliers attempting to scale production.

Exclusive Technavio Analysis on Customer Landscape

The medical packaging films market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the medical packaging films market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
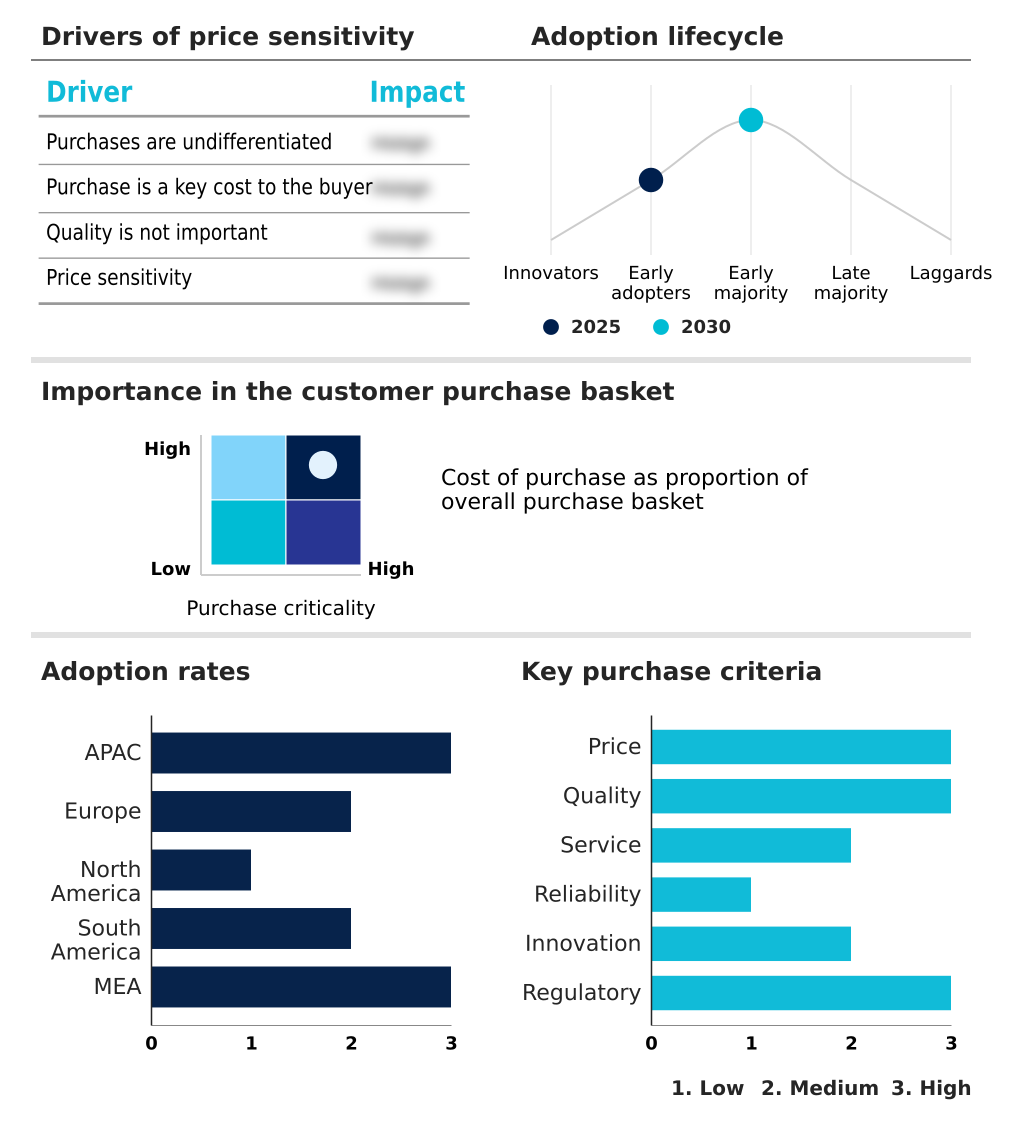
Customer Landscape of Medical Packaging Films Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, medical packaging films market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

3M Co. - The portfolio includes high performance transparent film dressings, closure systems, and sterile barrier solutions designed to maintain microbial isolation and structural integrity for advanced healthcare and infection prevention applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • 3M Co.
  • Amcor Plc
  • Berry Global Inc.
  • CCL Label
  • Constantia Flexibles GmbH
  • Coveris Management GmbH
  • DuPont de Nemours Inc.
  • Glenroy Inc.
  • Huhtamaki Oyj
  • Jindal Poly Films Ltd.
  • KP Holding GmbH and Co. KG
  • Mondi Plc
  • RENOLIT SE
  • Sealed Air Corp.
  • Sonoco Products Co.
  • Tekni Plex Inc.
  • Toppan Inc.
  • Toray Industries Inc.
  • UFlex Ltd.
  • Winpak Ltd.
  • Wipak Group

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Medical packaging films market

  • In the Metal, Glass and Plastic Containers industry, the transition toward non-fossil resins has restructured procurement pipelines, directly impacting Medical Packaging Films demand by prioritizing circular alternatives that reduce carbon footprints by up to 25% without compromising barrier integrity.
  • Stringent global health directives mandating halogen-free polymer utilization have compelled resin extruders to phase out traditional materials, directly driving Medical Packaging Films demand for advanced copolymer alternatives that offer comparable oxygen barrier performance for pharmaceutical applications.
  • The rapid expansion of automated high-speed machinery across regional manufacturing hubs has necessitated the development of highly uniform polymer substrates, directly boosting Medical Packaging Films demand as healthcare providers require optimized materials to minimize product waste by 12%.
  • Advancements in advanced sterilization techniques have shifted processing preferences away from thermal methods, directly impacting Medical Packaging Films demand by requiring specialized irradiation resistance to ensure secure terminal processing for single-use medical devices.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Medical Packaging Films Market insights. See full methodology.

Market Scope
Page number 309
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5%
Market growth 2026-2030 USD 2089.4 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.7%
Key countries China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Medical Packaging Films arena represents a highly technical convergence of advanced polymer science and rigorous healthcare compliance. Manufacturers are actively engineering multi-layered protective structures to shield complex therapeutics from environmental degradation and microbial ingress. The strategic integration of high-performance materials delivers an exceptional oxygen transmission barrier, ensuring that sensitive biological formulations retain their efficacy over extended shelf lives.
  • In a notable operational shift, companies deploying automated defect-detection systems across their film extrusion lines have achieved a 30% reduction in processing time and significantly lowered material scrap rates. This technological advancement directly supports board-level objectives to optimize manufacturing budgets while adhering strictly to global safety mandates.
  • Furthermore, specialized applications demand absolute chemical inertness and precise flexibility to maintain therapeutic integrity during patient administration. The continuous refinement of these high-performance substrates allows clinical supply chains to achieve superior contamination control and secure reliable product distribution across diverse healthcare settings.

What are the Key Data Covered in this Medical Packaging Films Market Research and Growth Report?

  • What is the expected growth of the Medical Packaging Films Market between 2026 and 2030?

    • USD 2.09 billion, at a CAGR of 5%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Thermoformable film, and High barrier film), Application (Bags and pouches, Blister packs, Medical device trays, and Others), End-user (Pharmaceutical manufacturers, Medical device manufacturers, Hospitals and clinics, and Others) and Geography (APAC, Europe, North America, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Rising demand for sterile medical barrier packaging, Navigating complex global regulatory frameworks

  • Who are the major players in the Medical Packaging Films Market?

    • 3M Co., Amcor Plc, Berry Global Inc., CCL Label, Constantia Flexibles GmbH, Coveris Management GmbH, DuPont de Nemours Inc., Glenroy Inc., Huhtamaki Oyj, Jindal Poly Films Ltd., KP Holding GmbH and Co. KG, Mondi Plc, RENOLIT SE, Sealed Air Corp., Sonoco Products Co., Tekni Plex Inc., Toppan Inc., Toray Industries Inc., UFlex Ltd., Winpak Ltd. and Wipak Group

Market Research Insights

  • The Medical Packaging Films landscape is fundamentally driven by the critical need to preserve product efficacy and safety across diverse clinical environments. Rapid adoption of advanced cold chain storage solutions has compelled manufacturers to engineer robust barrier structures, elevating overall supply chain reliability by 18%.
  • Furthermore, transitioning toward sustainable substrates within secondary layers has allowed healthcare networks to improve operational sustainability metrics by 14% without compromising primary microbial isolation. This intersection of specialized material science and strict infection prevention protocols ensures that patient safety remains paramount. The ongoing evolution of secure sealing technologies directly supports enhanced patient compliance and operational transparency across global distribution networks.

We can help! Our analysts can customize this medical packaging films market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Medical Packaging Films Market 2020 - 2024

Historic Market Size - Data Table on Global Medical Packaging Films Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Medical Packaging Films Market

6.2 Impact of geopolitical conflicts on Global Medical Packaging Films Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Thermoformable film - Market size and forecast 2025-2030

Chart on Thermoformable film - Market size and forecast 2025-2030 ($ million)
Data Table on Thermoformable film - Market size and forecast 2025-2030 ($ million)
Chart on Thermoformable film - Year-over-year growth 2025-2030 (%)
Data Table on Thermoformable film - Year-over-year growth 2025-2030 (%)

8.4 High barrier film - Market size and forecast 2025-2030

Chart on High barrier film - Market size and forecast 2025-2030 ($ million)
Data Table on High barrier film - Market size and forecast 2025-2030 ($ million)
Chart on High barrier film - Year-over-year growth 2025-2030 (%)
Data Table on High barrier film - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Application

9.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

9.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

9.3 Bags and pouches - Market size and forecast 2025-2030

Chart on Bags and pouches - Market size and forecast 2025-2030 ($ million)
Data Table on Bags and pouches - Market size and forecast 2025-2030 ($ million)
Chart on Bags and pouches - Year-over-year growth 2025-2030 (%)
Data Table on Bags and pouches - Year-over-year growth 2025-2030 (%)

9.4 Blister packs - Market size and forecast 2025-2030

Chart on Blister packs - Market size and forecast 2025-2030 ($ million)
Data Table on Blister packs - Market size and forecast 2025-2030 ($ million)
Chart on Blister packs - Year-over-year growth 2025-2030 (%)
Data Table on Blister packs - Year-over-year growth 2025-2030 (%)

9.5 Medical device trays - Market size and forecast 2025-2030

Chart on Medical device trays - Market size and forecast 2025-2030 ($ million)
Data Table on Medical device trays - Market size and forecast 2025-2030 ($ million)
Chart on Medical device trays - Year-over-year growth 2025-2030 (%)
Data Table on Medical device trays - Year-over-year growth 2025-2030 (%)

9.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Pharmaceutical manufacturers - Market size and forecast 2025-2030

Chart on Pharmaceutical manufacturers - Market size and forecast 2025-2030 ($ million)
Data Table on Pharmaceutical manufacturers - Market size and forecast 2025-2030 ($ million)
Chart on Pharmaceutical manufacturers - Year-over-year growth 2025-2030 (%)
Data Table on Pharmaceutical manufacturers - Year-over-year growth 2025-2030 (%)

10.4 Medical device manufacturers - Market size and forecast 2025-2030

Chart on Medical device manufacturers - Market size and forecast 2025-2030 ($ million)
Data Table on Medical device manufacturers - Market size and forecast 2025-2030 ($ million)
Chart on Medical device manufacturers - Year-over-year growth 2025-2030 (%)
Data Table on Medical device manufacturers - Year-over-year growth 2025-2030 (%)

10.5 Hospitals and clinics - Market size and forecast 2025-2030

Chart on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals and clinics - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals and clinics - Year-over-year growth 2025-2030 (%)

10.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising demand for sterile medical barrier packaging
Increasing prevalence of chronic diseases worldwide
Growth of biologics temperature sensitive therapies

13.2 Market challenges

Navigating complex global regulatory frameworks
Transitioning toward recyclable packaging materials
Impact of raw material price changes

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Surge in biopharmaceutical injectable drug demand
Expansion of home healthcare diagnostic testing
Advancement of high barrier coextrusion technologies

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 3M Co.

3M Co. - Overview
3M Co. - Business segments
3M Co. - Key news
3M Co. - Key offerings
3M Co. - Segment focus
SWOT

15.5 Amcor Plc

Amcor Plc - Overview
Amcor Plc - Business segments
Amcor Plc - Key news
Amcor Plc - Key offerings
Amcor Plc - Segment focus
SWOT

15.6 Berry Global Inc.

Berry Global Inc. - Overview
Berry Global Inc. - Product / Service
Berry Global Inc. - Key offerings
SWOT

15.7 CCL Label

CCL Label - Overview
CCL Label - Product / Service
CCL Label - Key offerings
SWOT

15.8 Coveris Management GmbH

Coveris Management GmbH - Overview
Coveris Management GmbH - Product / Service
Coveris Management GmbH - Key offerings
SWOT

15.9 DuPont de Nemours Inc.

DuPont de Nemours Inc. - Overview
DuPont de Nemours Inc. - Business segments
DuPont de Nemours Inc. - Key news
DuPont de Nemours Inc. - Key offerings
DuPont de Nemours Inc. - Segment focus
SWOT

15.10 Huhtamaki Oyj

Huhtamaki Oyj - Overview
Huhtamaki Oyj - Business segments
Huhtamaki Oyj - Key offerings
Huhtamaki Oyj - Segment focus
SWOT

15.11 Jindal Poly Films Ltd.

Jindal Poly Films Ltd. - Overview
Jindal Poly Films Ltd. - Business segments
Jindal Poly Films Ltd. - Key offerings
Jindal Poly Films Ltd. - Segment focus
SWOT

15.12 Mondi Plc

Mondi Plc - Overview
Mondi Plc - Business segments
Mondi Plc - Key news
Mondi Plc - Key offerings
Mondi Plc - Segment focus
SWOT

15.13 RENOLIT SE

RENOLIT SE - Overview
RENOLIT SE - Product / Service
RENOLIT SE - Key offerings
SWOT

15.14 Sealed Air Corp.

Sealed Air Corp. - Overview
Sealed Air Corp. - Business segments
Sealed Air Corp. - Key offerings
Sealed Air Corp. - Segment focus
SWOT

15.15 Sonoco Products Co.

Sonoco Products Co. - Overview
Sonoco Products Co. - Business segments
Sonoco Products Co. - Key news
Sonoco Products Co. - Key offerings
Sonoco Products Co. - Segment focus
SWOT

15.16 Toray Industries Inc.

Toray Industries Inc. - Overview
Toray Industries Inc. - Business segments
Toray Industries Inc. - Key news
Toray Industries Inc. - Key offerings
Toray Industries Inc. - Segment focus
SWOT

15.17 UFlex Ltd.

UFlex Ltd. - Overview
UFlex Ltd. - Business segments
UFlex Ltd. - Key offerings
UFlex Ltd. - Segment focus
SWOT

15.18 Winpak Ltd.

Winpak Ltd. - Overview
Winpak Ltd. - Business segments
Winpak Ltd. - Key offerings
Winpak Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Medical Packaging Films market growth will increase by USD 2089.4 million during 2026-2030.

The Medical Packaging Films market is expected to grow at a CAGR of 5% during 2026-2030.

Medical Packaging Films market is segmented by Type (Thermoformable film, High barrier film) Application (Bags and pouches, Blister packs, Medical device trays, Others) End-user (Pharmaceutical manufacturers, Medical device manufacturers, Hospitals and clinics, Others)

3M Co., Amcor Plc, Berry Global Inc., CCL Label, Constantia Flexibles GmbH, Coveris Management GmbH, DuPont de Nemours Inc., Glenroy Inc., Huhtamaki Oyj, Jindal Poly Films Ltd., KP Holding GmbH and Co. KG, Mondi Plc, RENOLIT SE, Sealed Air Corp., Sonoco Products Co., Tekni Plex Inc., Toppan Inc., Toray Industries Inc., UFlex Ltd., Winpak Ltd., Wipak Group are a few of the key vendors in the Medical Packaging Films market.

APAC will register the highest growth rate of 41% among the other regions. Therefore, the Medical Packaging Films market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Rising demand for sterile medical barrier packaging is the driving factor this market.

The Medical Packaging Films market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
