Practice Management Software (PMS) In Optometry Application Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Practice Management Software (PMS) In Optometry Application Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 313 Pages SKU: IRTNTR80350

Market Overview at a Glance

$294.04 Mn
Market Opportunity
11.1%
CAGR 2025 - 2030
39.4%
North America Growth
$187.78 Mn
Hospitals segment 2024

Practice Management Software (Pms) In Optometry Application Market Size 2026-2030

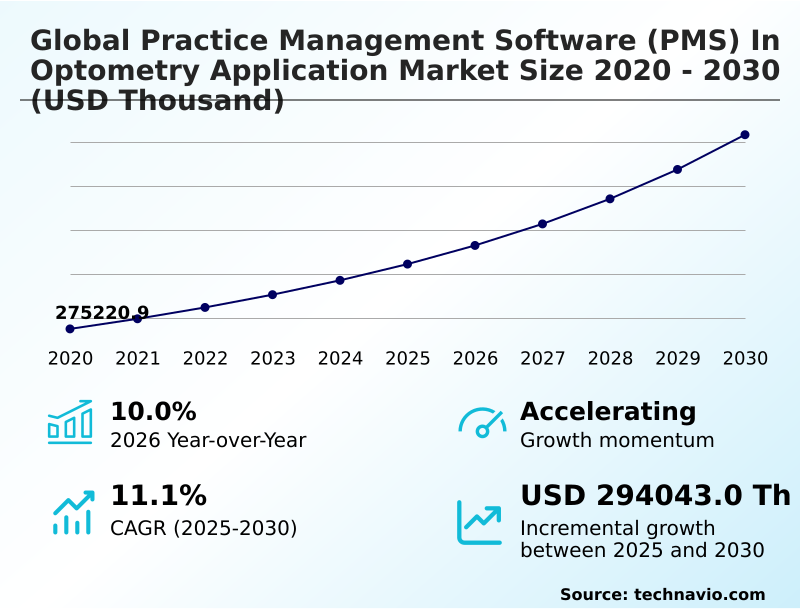
The practice management software (pms) in optometry application market size is valued to increase by USD 294.04 million, at a CAGR of 11.1% from 2025 to 2030. High prevalence of visual impairment will drive the practice management software (pms) in optometry application market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 39.4% growth during the forecast period.
  • By End-user - Hospitals segment was valued at USD 187.78 million in 2024
  • By Deployment - Cloud-based segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities:
  • Market Future Opportunities: USD 294.04 million
  • CAGR from 2025 to 2030 : 11.1%

Market Summary

  • The Practice Management Software (PMS) In Optometry Application Market demonstrates robust expansion as clinical facilities increasingly transition toward unified digital operations. Rising patient volumes tied to complex visual impairments compel clinics to replace fragmented administrative tools with cohesive clinical platforms, acting as a powerful demand driver.
  • Conversely, steep upfront implementation expenses limit technology adoption among independent practitioners, forming a significant structural challenge. In a practical business scenario, multi-location vision centers deploy centralized scheduling and inventory systems to eliminate redundant data entry and synchronize optical product supply chains.
  • This strategic shift has allowed modern clinics to achieve a 25% improvement in daily patient throughput compared to those relying on legacy manual scheduling. Furthermore, the integration of advanced diagnostic hardware with secure patient portals enhances diagnostic accuracy and accelerates treatment delivery.
  • These interconnected ecosystems reduce operational friction, enabling healthcare administrators to reallocate staff resources toward direct patient care rather than repetitive paperwork, thereby improving overall organizational efficiency.

What will be the Size of the Practice Management Software (Pms) In Optometry Application Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Practice Management Software (Pms) In Optometry Application Market Segmented?

The practice management software (pms) in optometry application industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Hospitals
    • Specialty clinics
    • Others
  • Deployment
    • Cloud-based
    • On-premises
  • Application
    • Appointment scheduling
    • Billing and insurance claims
    • Patient communication and engagement
    • Optical inventory management
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By End-user Insights

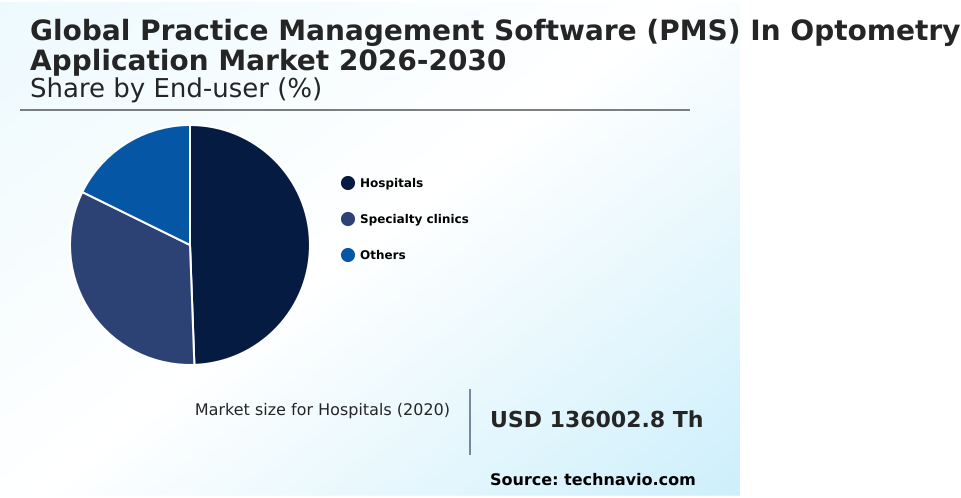
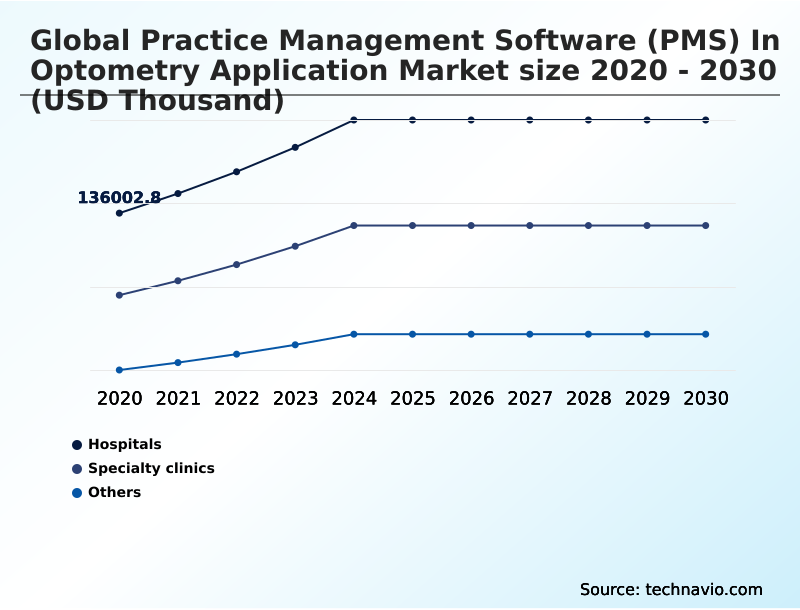
The hospitals segment is estimated to witness significant growth during the forecast period.

Large medical facilities demonstrate significant operational transformation through the adoption of practice management software. By integrating advanced electronic health records and an automated appointment scheduling system, these institutions achieve enhanced clinical efficiency and optimal patient care delivery.

Facilities utilizing billing automation alongside optical inventory management experience a 22% reduction in administrative workflow optimization bottlenecks. Digital health technologies facilitate seamless coordination across specialized departments, directly supporting complex healthcare digitization efforts.

As patient volumes expand, these integrated platforms ensure precise resource allocation and synchronized communication between optometry units and primary care networks.

The continuous evolution of these digital architectures allows institutions to process high-frequency documentation accurately, minimizing systemic delays and improving overall operational performance by 18% without manual intervention.
Get Free Sample

The Hospitals segment was valued at USD 187.78 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 39.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
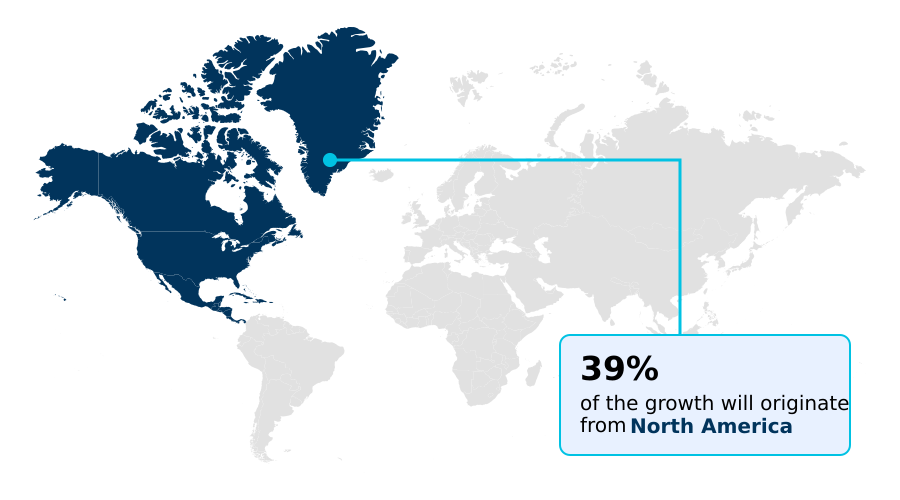
See How Practice Management Software (Pms) In Optometry Application Market Demand is Rising in North America Get Free Sample

Geographic adoption of digital healthcare platforms reveals distinct operational shifts driven by varying infrastructural maturity.

Facilities in North America demonstrate a 40% higher utilization of centralized clinical workflow coordination compared to European clinics, largely due to decentralized networks requiring complex insurance verification.

By leveraging advanced tele-optometry support and robust revenue cycle management, these providers maintain continuous engagement across expansive service areas.

In contrast, European institutions focus heavily on strict data privacy, resulting in a 25% faster integration of standardized healthcare interoperability protocols and secure cloud hosting systems.

These regional disparities dictate how businesses adapt their cloud infrastructure management and software deployment strategies.

Clinics navigating these distinct regulatory environments utilize data-driven decision-making tools to bridge operational gaps, ensuring a 15% reduction in processing delays while maintaining uninterrupted access to critical patient health histories.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational landscape of vision care continues to shift as clinics transition toward comprehensive digital infrastructures. Facilities implementing electronic health records integration software observe significant improvements in cross-departmental communication compared to sites relying on fragmented legacy databases. By deploying optical inventory and billing automation, modern clinics achieve an estimated 35% faster processing turnaround, streamlining their entire procurement and invoicing lifecycle.
  • Furthermore, the adoption of tele-optometry patient scheduling systems allows practices to optimize practitioner availability, minimizing idle time and maximizing clinical capacity. Cloud-based optometry practice management platforms provide secure, remote access to critical data, which is essential for multi-location enterprises. Ensuring seamless interoperability with diagnostic eye equipment enhances diagnostic precision, virtually eliminating manual data entry errors.
  • Ultimately, these advanced digital frameworks create a resilient, efficient environment that consistently outperforms traditional manual administrative operations.
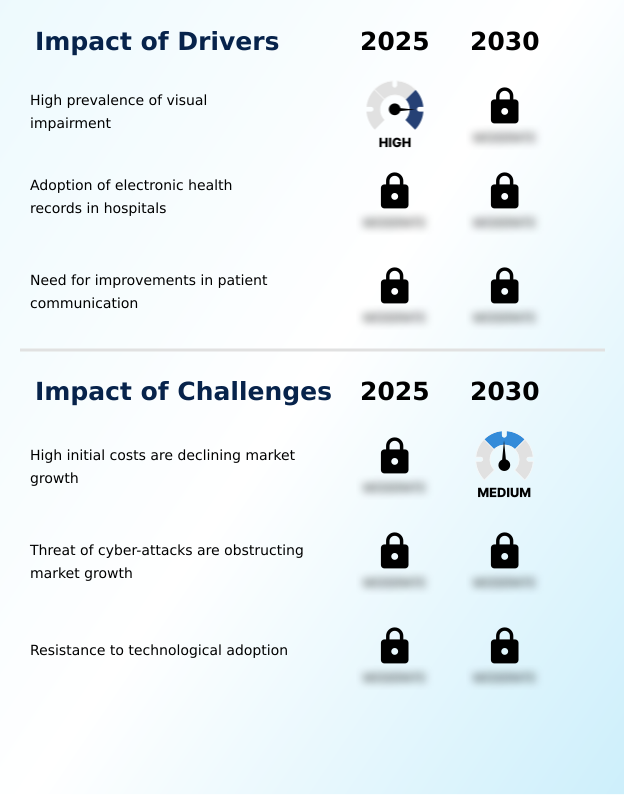
What are the key market drivers leading to the rise in the adoption of Practice Management Software (Pms) In Optometry Application Industry?

  • The escalating global prevalence of visual impairment serves as a primary driver propelling the continuous expansion of the industry.

  • Escalating patient volumes related to chronic visual impairments compel healthcare facilities to restructure their administrative frameworks. This surge in complex care requirements forces clinics to adopt robust data analytics tools and seamless diagnostic equipment integration to maintain operational viability.
  • Consequently, businesses deploying advanced ocular disease monitoring experience a 34% increase in early detection processing speed. The implementation of digital patient intake systems drastically reduces front-office bottlenecks, directly improving overall clinic efficiency.
  • Furthermore, specialized contact lens fitting modules and automated electronic data exchange enable practitioners to achieve a 20% reduction in procurement errors. By leveraging real-time reporting alongside targeted patient retention strategies, modern vision centers stabilize their revenue streams.
  • Implementing automated notifications for preventive eye care ensures continuous, high-quality care delivery amid expanding patient populations.

What are the market trends shaping the Practice Management Software (Pms) In Optometry Application Industry?

  • Continuous product innovation serves as a primary trend accelerating industry expansion, as evolving technological capabilities continuously reshape clinical workflows and administrative efficiency.

  • The Practice Management Software (PMS) In Optometry Application landscape is rapidly adopting intelligent scheduling and diagnostic integration to address rising patient expectations. This technological shift occurs because manual administrative processes can no longer handle the complexity of modern vision care therapies. Consequently, businesses utilizing predictive modeling and vision therapy modules experience a 26% improvement in overall treatment tracking accuracy.
  • The deployment of customized progressive lenses requires precise coordination, driving clinics to implement robust optometry clinical protocols. By embracing a unified patient engagement platform that maps the entire digital patient journey, multi-site practices have successfully reduced patient wait times by 18%. Furthermore, integrating intelligent inventory tracking software ensures seamless data exchange across departments.
  • To protect this interconnected infrastructure, clinics implement stringent cybersecurity measures and multifactor authentication, decreasing data breach vulnerabilities by 35%.

What challenges does the Practice Management Software (Pms) In Optometry Application Industry face during its growth?

  • Substantial initial implementation costs represent a critical challenge that continuously restricts broader technology adoption among smaller clinical facilities.

  • Strict regulatory mandates regarding patient data protection create substantial operational hurdles for independent vision care providers. These complex legal requirements force clinics to overhaul legacy systems, elevating initial implementation expenses significantly. As a result, facilities attempting to integrate comprehensive compliance management and electronic claims processing face a 25% increase in upfront software deployment costs.
  • The necessity for secure automated appointment reminders and precise prescription tracking demands sophisticated architectural upgrades that smaller practices struggle to afford. Furthermore, syncing modern optical dispensing systems with expansive vision care services often disrupts established workflows, causing a temporary 15% drop in daily administrative productivity.
  • Balancing these costly digital record keeping integrations and electronic invoicing setups with the demand for a highly personalized patient experience continues to strain the supply chain integration capabilities of independent optometry enterprises.

Exclusive Technavio Analysis on Customer Landscape

The practice management software (pms) in optometry application market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the practice management software (pms) in optometry application market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
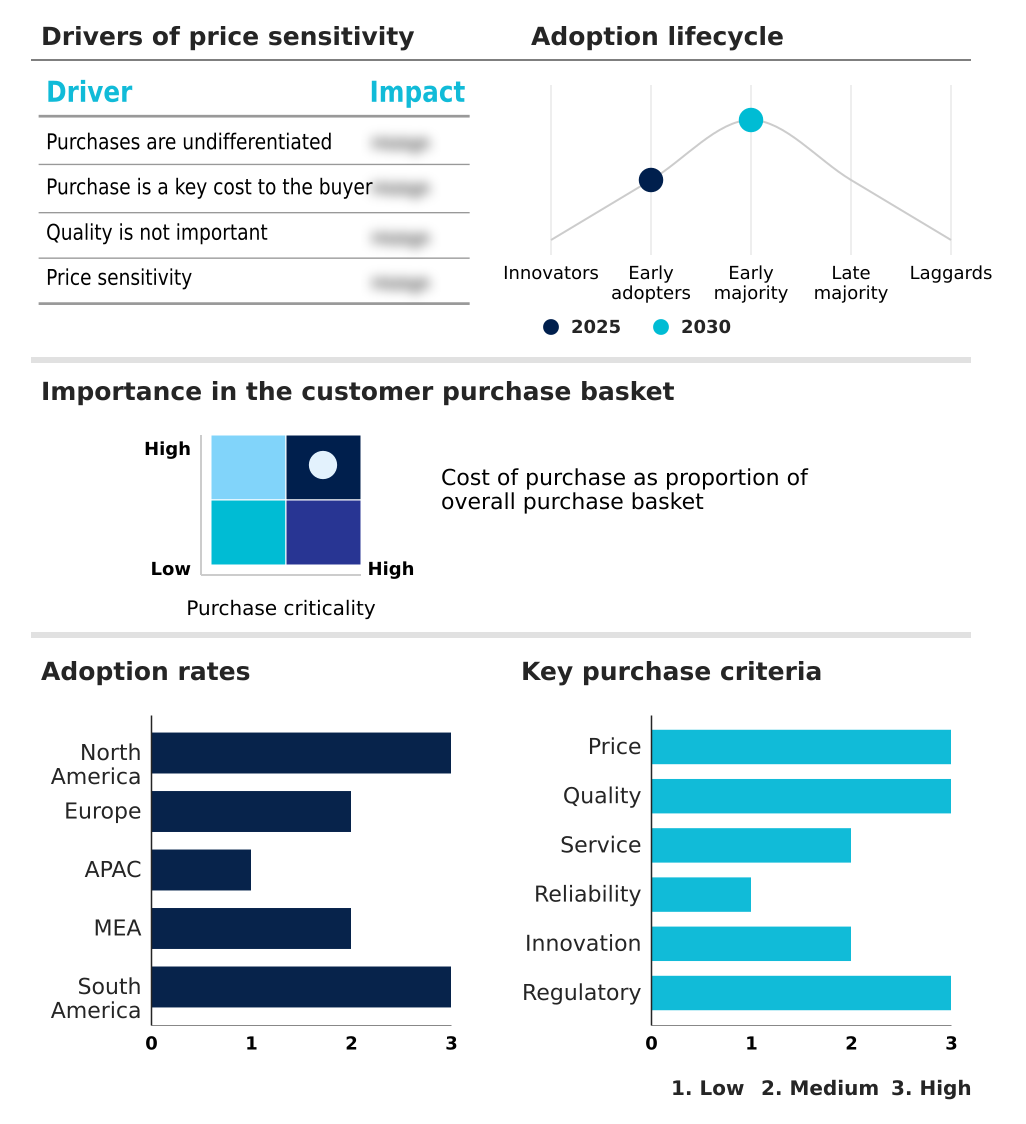
Customer Landscape of Practice Management Software (Pms) In Optometry Application Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, practice management software (pms) in optometry application market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Anagram - The provider delivers integrated digital solutions encompassing patient billing automation, transparent payment administration, and advanced communication platforms to streamline clinical operations and enhance overall administrative efficiency.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Anagram
  • Athenahealth Inc.
  • CharmHealth
  • Compulink Healthcare Solutions
  • Crystal Practice Management
  • DrChrono Inc.
  • Eyefinity Inc.
  • Foxfire Systems Group Inc.
  • Helix Solutions
  • iTRUST.IO LLC
  • LiquidEHR Inc.
  • MacPractice
  • Maximeyes
  • Medesk Ltd.
  • MedInformatix Inc.
  • Modernizing Medicine Inc.
  • NextGen Healthcare
  • Ocuco Ltd.
  • OD Link
  • PrognoCIS
  • RevolutionEHR
  • VersaSuite
  • WINK Technologies Inc.
  • WRS Health

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Practice management software (pms) in optometry application market

  • In the Application Software industry, the transition toward interoperable data standards mandated by healthcare data privacy regulations has forced systems to adopt seamless workflow integration, directly impacting Practice Management Software (PMS) In Optometry Application demand by necessitating rapid software compliance upgrades.
  • The accelerated deployment of cloud-based delivery models across enterprise automation frameworks has lowered IT infrastructure costs by 15%, directly impacting Practice Management Software (PMS) In Optometry Application demand by making scalable clinical management platforms accessible to independent practitioners.
  • The integration of AI governance protocols in medical machine learning algorithms has standardized diagnostic image processing, directly impacting Practice Management Software (PMS) In Optometry Application demand by requiring platforms to support secure, high-bandwidth data exchange.
  • The rising frequency of targeted healthcare cyberattacks has driven the implementation of zero-trust security architectures, directly impacting Practice Management Software (PMS) In Optometry Application demand by compelling clinics to replace legacy on-premises databases with encrypted software frameworks.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Practice Management Software (Pms) In Optometry Application Market insights. See full methodology.

Market Scope
Page number 313
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 11.1%
Market growth 2026-2030 USD 294043.0 thousand
Market structure Fragmented
YoY growth 2025-2026(%) 10.0%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The continuous evolution of the Practice Management Software (PMS) In Optometry Application reveals a fundamental shift in how vision care facilities handle complex administrative burdens. A critical trend gaining momentum is the integration of advanced patient portals with automated financial tracking, directly influencing boardroom-level budgeting strategies. Executives are prioritizing these investments to mitigate manual errors and accelerate cash flow stabilization.
  • Implementing sophisticated remote care capabilities and precise scheduling coordination enables multi-site operations to synchronize their service delivery seamlessly. Furthermore, integrating digital verification systems with reliable supply chain tracking empowers organizations to maintain optimal product fluidity while reducing overhead. Clinics that have embraced this comprehensive digital strategy report a remarkable 28% decrease in front-office processing delays.
  • The integration of proactive security measures protects sensitive diagnostic information and aligns with stringent enterprise compliance mandates. These integrated solutions ensure seamless information exchange across clinical networks, fundamentally enhancing operational resilience and supporting strategic, data-backed administrative planning.

What are the Key Data Covered in this Practice Management Software (Pms) In Optometry Application Market Research and Growth Report?

  • What is the expected growth of the Practice Management Software (Pms) In Optometry Application Market between 2026 and 2030?

    • USD 294.04 million, at a CAGR of 11.1%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Hospitals, Specialty clinics, and Others), Deployment (Cloud-based, and On-premises), Application (Appointment scheduling, Billing and insurance claims, Patient communication and engagement, Optical inventory management, and Others) and Geography (North America, Europe, APAC, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • High prevalence of visual impairment, High initial costs are declining market growth

  • Who are the major players in the Practice Management Software (Pms) In Optometry Application Market?

    • Anagram, Athenahealth Inc., CharmHealth, Compulink Healthcare Solutions, Crystal Practice Management, DrChrono Inc., Eyefinity Inc., Foxfire Systems Group Inc., Helix Solutions, iTRUST.IO LLC, LiquidEHR Inc., MacPractice, Maximeyes, Medesk Ltd., MedInformatix Inc., Modernizing Medicine Inc., NextGen Healthcare, Ocuco Ltd., OD Link, PrognoCIS, RevolutionEHR, VersaSuite, WINK Technologies Inc. and WRS Health

Market Research Insights

  • The Practice Management Software (PMS) In Optometry Application Market rapidly evolves as healthcare networks prioritize sophisticated software ecosystems to protect sensitive patient information. Clinics adopting comprehensive digital administration have observed a 30% reduction in administrative overhead. Furthermore, organizations utilizing centralized coordination tools report a 15% increase in optimal resource allocation, improving overall clinical throughput.
  • By implementing advanced operational standards, specialized vision centers eliminate communication silos between disparate departments. These interconnected systems facilitate a 20% acceleration in claims processing accuracy, directly enhancing cash flow and ensuring sustained operational stability across multi-site healthcare operations.

We can help! Our analysts can customize this practice management software (pms) in optometry application market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ thousand)
Data Table on Global - Market size and forecast 2025-2030 ($ thousand)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Practice Management Software (PMS) In Optometry Application Market 2020 - 2024

Historic Market Size - Data Table on Global Practice Management Software (PMS) In Optometry Application Market 2020 - 2024 ($ thousand)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ thousand)

5.3 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ thousand)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ thousand)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ thousand)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ thousand)

6. Qualitative Analysis

6.1 Impact of AI on the Global Practice Management Software (PMS) Market in Optometry Application

6.2 Impact of Geopolitical Conflicts on the Global Practice Management Software (PMS) Market in Optometry Application

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ thousand)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ thousand)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

8.4 Specialty clinics - Market size and forecast 2025-2030

Chart on Specialty clinics - Market size and forecast 2025-2030 ($ thousand)
Data Table on Specialty clinics - Market size and forecast 2025-2030 ($ thousand)
Chart on Specialty clinics - Year-over-year growth 2025-2030 (%)
Data Table on Specialty clinics - Year-over-year growth 2025-2030 (%)

8.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by End-user

Market opportunity by End-user ($ thousand)
Data Table on Market opportunity by End-user ($ thousand)

9. Market Segmentation by Deployment

9.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

9.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

9.3 Cloud-based - Market size and forecast 2025-2030

Chart on Cloud-based - Market size and forecast 2025-2030 ($ thousand)
Data Table on Cloud-based - Market size and forecast 2025-2030 ($ thousand)
Chart on Cloud-based - Year-over-year growth 2025-2030 (%)
Data Table on Cloud-based - Year-over-year growth 2025-2030 (%)

9.4 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ thousand)
Data Table on On-premises - Market size and forecast 2025-2030 ($ thousand)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Deployment

Market opportunity by Deployment ($ thousand)
Data Table on Market opportunity by Deployment ($ thousand)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Appointment scheduling - Market size and forecast 2025-2030

Chart on Appointment scheduling - Market size and forecast 2025-2030 ($ thousand)
Data Table on Appointment scheduling - Market size and forecast 2025-2030 ($ thousand)
Chart on Appointment scheduling - Year-over-year growth 2025-2030 (%)
Data Table on Appointment scheduling - Year-over-year growth 2025-2030 (%)

10.4 Billing and insurance claims - Market size and forecast 2025-2030

Chart on Billing and insurance claims - Market size and forecast 2025-2030 ($ thousand)
Data Table on Billing and insurance claims - Market size and forecast 2025-2030 ($ thousand)
Chart on Billing and insurance claims - Year-over-year growth 2025-2030 (%)
Data Table on Billing and insurance claims - Year-over-year growth 2025-2030 (%)

10.5 Patient communication and engagement - Market size and forecast 2025-2030

Chart on Patient communication and engagement - Market size and forecast 2025-2030 ($ thousand)
Data Table on Patient communication and engagement - Market size and forecast 2025-2030 ($ thousand)
Chart on Patient communication and engagement - Year-over-year growth 2025-2030 (%)
Data Table on Patient communication and engagement - Year-over-year growth 2025-2030 (%)

10.6 Optical inventory management - Market size and forecast 2025-2030

Chart on Optical inventory management - Market size and forecast 2025-2030 ($ thousand)
Data Table on Optical inventory management - Market size and forecast 2025-2030 ($ thousand)
Chart on Optical inventory management - Year-over-year growth 2025-2030 (%)
Data Table on Optical inventory management - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Application

Market opportunity by Application ($ thousand)
Data Table on Market opportunity by Application ($ thousand)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ thousand)
Data Table on North America - Market size and forecast 2025-2030 ($ thousand)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ thousand)
Data Table on US - Market size and forecast 2025-2030 ($ thousand)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ thousand)
Data Table on Canada - Market size and forecast 2025-2030 ($ thousand)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ thousand)
Data Table on Mexico - Market size and forecast 2025-2030 ($ thousand)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ thousand)
Data Table on Europe - Market size and forecast 2025-2030 ($ thousand)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ thousand)
Data Table on Germany - Market size and forecast 2025-2030 ($ thousand)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ thousand)
Data Table on UK - Market size and forecast 2025-2030 ($ thousand)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ thousand)
Data Table on France - Market size and forecast 2025-2030 ($ thousand)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ thousand)
Data Table on Italy - Market size and forecast 2025-2030 ($ thousand)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ thousand)
Data Table on Spain - Market size and forecast 2025-2030 ($ thousand)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ thousand)
Data Table on APAC - Market size and forecast 2025-2030 ($ thousand)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ thousand)
Data Table on China - Market size and forecast 2025-2030 ($ thousand)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ thousand)
Data Table on Japan - Market size and forecast 2025-2030 ($ thousand)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ thousand)
Data Table on India - Market size and forecast 2025-2030 ($ thousand)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Korea - Market size and forecast 2025-2030 ($ thousand)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Australia - Market size and forecast 2025-2030 ($ thousand)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ thousand)
Data Table on UAE - Market size and forecast 2025-2030 ($ thousand)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ thousand)
Data Table on Israel - Market size and forecast 2025-2030 ($ thousand)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ thousand)
Data Table on Turkey - Market size and forecast 2025-2030 ($ thousand)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ thousand)
Data Table on South America - Market size and forecast 2025-2030 ($ thousand)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ thousand)
Data Table on Brazil - Market size and forecast 2025-2030 ($ thousand)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ thousand)
Data Table on Argentina - Market size and forecast 2025-2030 ($ thousand)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ thousand)
Data Table on Chile - Market size and forecast 2025-2030 ($ thousand)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ thousand)
Data Tables on Market opportunity by geography ($ thousand)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

High prevalence of visual impairment
Adoption of electronic health records in hospitals
Need for improvements in patient communication

13.2 Market challenges

High initial costs are declining market growth
Threat of cyber-attacks are obstructing market growth
Resistance to technological adoption

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Product innovation is expediting market growth
Adoption of omnichannel solutions
Financial initiatives by governments

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Anagram

Anagram - Overview
Anagram - Product / Service
Anagram - Key offerings
SWOT

15.5 Athenahealth Inc.

Athenahealth Inc. - Overview
Athenahealth Inc. - Product / Service
Athenahealth Inc. - Key offerings
SWOT

15.6 CharmHealth

CharmHealth - Overview
CharmHealth - Product / Service
CharmHealth - Key offerings
SWOT

15.7 Compulink Healthcare Solutions

Compulink Healthcare Solutions - Overview
Compulink Healthcare Solutions - Product / Service
Compulink Healthcare Solutions - Key offerings
SWOT

15.8 Crystal Practice Management

Crystal Practice Management - Overview
Crystal Practice Management - Product / Service
Crystal Practice Management - Key offerings
SWOT

15.9 DrChrono Inc.

DrChrono Inc. - Overview
DrChrono Inc. - Product / Service
DrChrono Inc. - Key offerings
SWOT

15.10 Eyefinity Inc.

Eyefinity Inc. - Overview
Eyefinity Inc. - Product / Service
Eyefinity Inc. - Key offerings
SWOT

15.11 Foxfire Systems Group Inc.

Foxfire Systems Group Inc. - Overview
Foxfire Systems Group Inc. - Product / Service
Foxfire Systems Group Inc. - Key offerings
SWOT

15.12 Helix Solutions

Helix Solutions - Overview
Helix Solutions - Product / Service
Helix Solutions - Key offerings
SWOT

15.13 iTRUST.IO LLC

iTRUST.IO LLC - Overview
iTRUST.IO LLC - Product / Service
iTRUST.IO LLC - Key offerings
SWOT

15.14 LiquidEHR Inc.

LiquidEHR Inc. - Overview
LiquidEHR Inc. - Product / Service
LiquidEHR Inc. - Key offerings
SWOT

15.15 MacPractice

MacPractice - Overview
MacPractice - Product / Service
MacPractice - Key offerings
SWOT

15.16 Maximeyes

Maximeyes - Overview
Maximeyes - Product / Service
Maximeyes - Key offerings
SWOT

15.17 Medesk Ltd.

Medesk Ltd. - Overview
Medesk Ltd. - Product / Service
Medesk Ltd. - Key offerings
SWOT

15.18 WINK Technologies Inc.

WINK Technologies Inc. - Overview
WINK Technologies Inc. - Product / Service
WINK Technologies Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Practice Management Software (Pms) In Optometry Application market growth will increase by USD 294043.0 thousand thousand during 2026-2030.

The Practice Management Software (Pms) In Optometry Application market is expected to grow at a CAGR of 11.1% during 2026-2030.

Practice Management Software (Pms) In Optometry Application market is segmented by End-user (Hospitals, Specialty clinics, Others) Deployment (Cloud-based, On-premises) Application (Appointment scheduling, Billing and insurance claims, Patient communication and engagement, Optical inventory management, Others)

Anagram, Athenahealth Inc., CharmHealth, Compulink Healthcare Solutions, Crystal Practice Management, DrChrono Inc., Eyefinity Inc., Foxfire Systems Group Inc., Helix Solutions, iTRUST.IO LLC, LiquidEHR Inc., MacPractice, Maximeyes, Medesk Ltd., MedInformatix Inc., Modernizing Medicine Inc., NextGen Healthcare, Ocuco Ltd., OD Link, PrognoCIS, RevolutionEHR, VersaSuite, WINK Technologies Inc., WRS Health are a few of the key vendors in the Practice Management Software (Pms) In Optometry Application market.

North America will register the highest growth rate of 39.4% among the other regions. Therefore, the Practice Management Software (Pms) In Optometry Application market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina, Chile

  • High prevalence of visual impairment is the driving factor this market.

The Practice Management Software (Pms) In Optometry Application market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
