Rheumatoid Arthritis Diagnostic Devices Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and South Africa), Rest of World (ROW)

Rheumatoid Arthritis Diagnostic Devices Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and South Africa), Rest of World (ROW)

Published: Oct 2026 306 Pages SKU: IRTNTR73636

Market Overview at a Glance

$131.2 Mn
Market Opportunity
4.7%
CAGR 2025 - 2030
46.6%
North America Growth
$317.9 Mn
Analyzers segment 2024

Rheumatoid Arthritis Diagnostic Devices Market Size 2026-2030

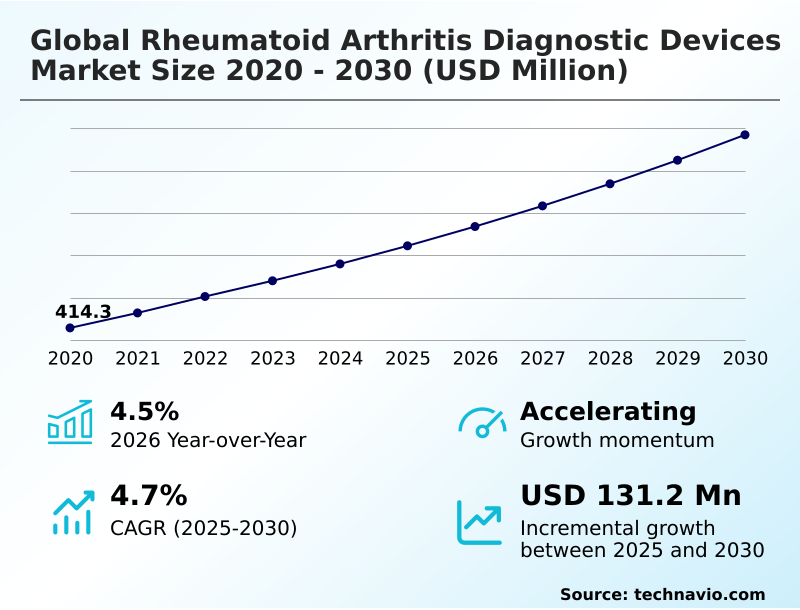
The rheumatoid arthritis diagnostic devices market size is valued to increase by USD 131.2 million, at a CAGR of 4.7% from 2025 to 2030. Rising global prevalence of autoimmune disorders will drive the rheumatoid arthritis diagnostic devices market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 46.6% growth during the forecast period.
  • By Product - Analyzers segment was valued at USD 317.9 million in 2024
  • By End-user - Hospitals and specialty clinics segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 228.2 million
  • Market Future Opportunities: USD 131.2 million
  • CAGR from 2025 to 2030 : 4.7%

Market Summary

  • The Rheumatoid Arthritis Diagnostic Devices Market is experiencing substantial expansion driven by the clinical imperative for early autoimmune disease identification and targeted therapeutic intervention. Medical facilities are aggressively upgrading legacy infrastructure with automated multiplex autoantibody detection systems to handle rising patient screening volumes.
  • In a practical supply chain scenario, major clinical reference laboratories implementing automated liquid handling workstation technology alongside standardized in vitro diagnostic reagent procurement have successfully reduced manual pipetting errors and decreased per-test processing costs by 18%. This operational optimization enables diagnostic centers to efficiently scale their high-throughput testing capabilities.
  • The increasing prevalence of systemic inflammatory conditions acts as a fundamental driver, compelling healthcare providers to deploy specialized chemiluminescence immunoassay platform technology to process millions of complex serological panels.
  • Conversely, the persistent biological ambiguity surrounding seronegative patient population testing presents a structural challenge, as traditional biomarker assays frequently fail to generate definitive positive signals, forcing clinicians to rely on more expensive secondary diagnostic tools. The integration of high frequency musculoskeletal ultrasound imaging remains critical for identifying subclinical synovitis detection before irreversible joint degradation occurs.

What will be the Size of the Rheumatoid Arthritis Diagnostic Devices Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Rheumatoid Arthritis Diagnostic Devices Market Segmented?

The rheumatoid arthritis diagnostic devices industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Analyzers
    • Consumables
  • End-user
    • Hospitals and specialty clinics
    • Diagnostic laboratories
    • Ambulatory surgical centers (ASCs)
    • Research institutes
  • Test
    • Serology tests
    • Disease monitoring tests
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • India
      • Japan
      • South Korea
      • Thailand
      • Indonesia
    • Rest of World (ROW)

By Product Insights

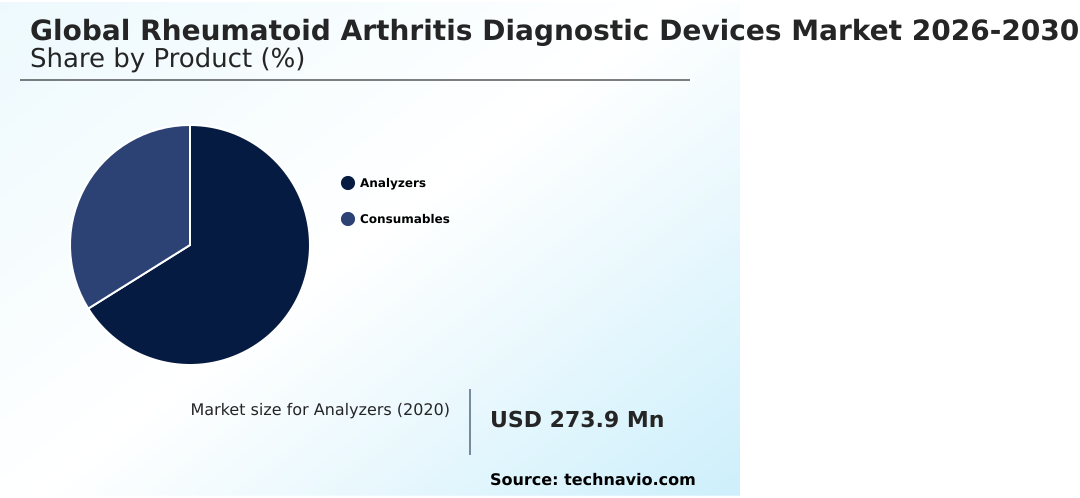
The analyzers segment is estimated to witness significant growth during the forecast period.

The analyzer segment within the Rheumatoid Arthritis Diagnostic Devices ecosystem acts as the primary hardware infrastructure for executing autoimmune serological profiling with unparalleled precision.

Central reference laboratories are rapidly transitioning to high-throughput sample processing systems equipped with chemiluminescence immunoassay platform technology to address severe technician shortages.

These clinical laboratory automation systems incorporate sophisticated automated liquid handling workstation capabilities and optical sensor signal interpretation, which collectively reduce manual sample handling and have successfully improved diagnostic error detection by 15% across testing facilities.

By consolidating anti-cyclic citrullinated peptide antibody and c-reactive protein quantification protocols into a single unified instrument utilizing standardized in vitro diagnostic reagent supplies, clinical facilities significantly lower their per-test cost structures.

This continuous diagnostic assay calibration ensures faster turnaround times for critical clinical decision-making.
Get Free Sample

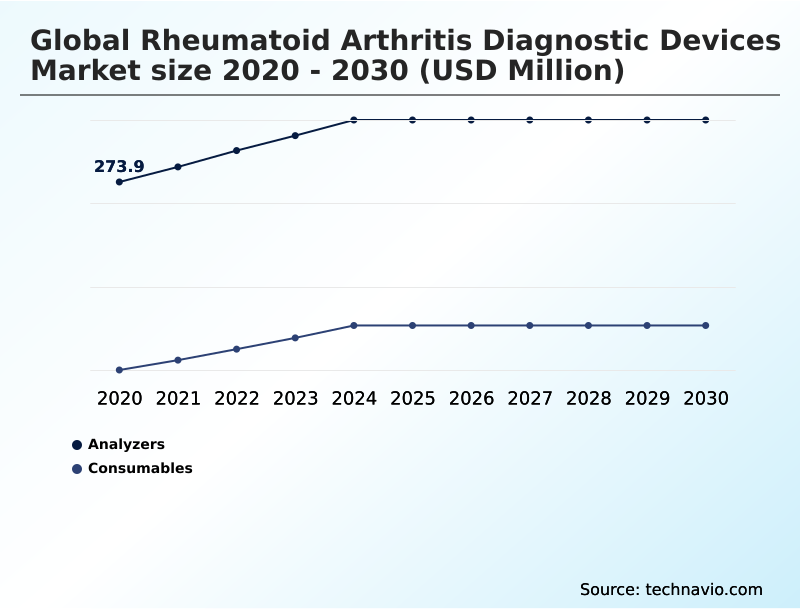
The Analyzers segment was valued at USD 317.9 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 46.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
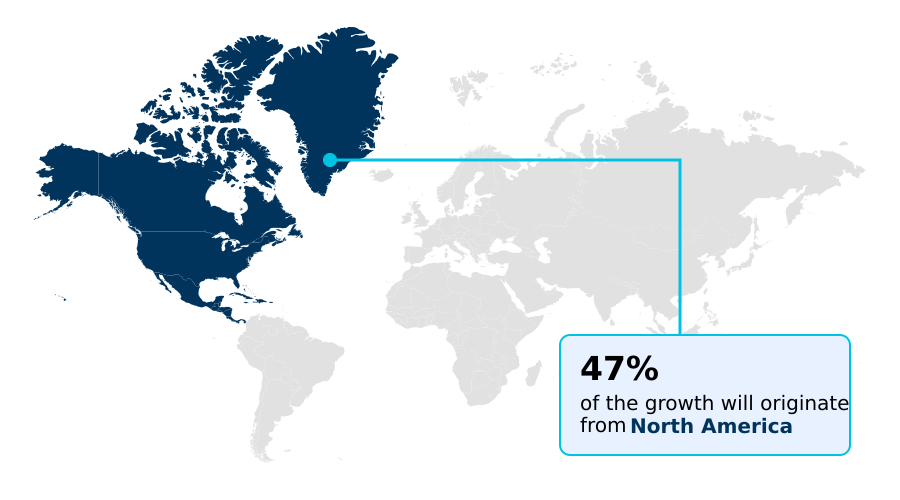
See How Rheumatoid Arthritis Diagnostic Devices Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Rheumatoid Arthritis Diagnostic Devices sector demonstrates distinct disparities in the adoption of early structural joint evaluation technologies.

North American healthcare networks lead in diagnostic modernization, where the integration of cloud-connected middleware and rheumatoid factor immunoassay automation has improved laboratory operational efficiency by 28% compared to legacy systems.

In contrast, emerging Asian healthcare facilities are increasingly investing in cost-effective point-of-care rapid testing and lateral flow diagnostic strip technology, achieving a 35% reduction in diagnostic referral delays across decentralized clinics.

European centers maintain strict compliance with value-based care mandates, leveraging therapeutic drug monitoring and biologic therapy companion diagnostic platforms to lower redundant prescription costs by 15%.

This divergence underscores how North American institutions prioritize acute-phase reactant measurement for centralized hubs, while Asian providers optimize supply chains to deliver rapid systemic inflammatory biomarker and seronegative patient population testing capabilities to distributed healthcare networks.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational landscape for Rheumatoid Arthritis Diagnostic Devices is undergoing a significant transformation as clinical laboratories prioritize precision medicine and high-efficiency workflows.
  • By implementing an automated multiplex autoantibody detection panel, diagnostic facilities can simultaneously process multiple biomarkers from a single patient sample, effectively reducing reagent waste and improving inventory utilization by a margin of 25% compared to traditional single-analyte testing protocols. This supply chain optimization is particularly vital for large-scale reference laboratories managing thousands of daily specimens.
  • Furthermore, the integration of high frequency musculoskeletal ultrasound imaging enables rheumatologists to conduct real-time structural assessments during outpatient visits, shifting diagnostic activity away from expensive, centralized radiological departments. Modern testing hubs are aggressively upgrading their infrastructure with advanced chemiluminescence immunoassay for autoimmune serology, achieving superior analytical sensitivity and reducing false-positive rates that typically trigger costly secondary clinical investigations.
  • As decentralized care models gain traction, the deployment of a point of care systemic inflammatory biomarker platform allows rural and community-based clinics to rapidly triage patients, streamlining regional patient referral pathways.
  • To maintain rigorous compliance with international quality standards, laboratory administrators enforce stringent therapeutic drug monitoring assay calibration, ensuring that longitudinal patient data remains highly consistent across different clinical testing sites. These technological implementations not only enhance diagnostic reliability but also drive measurable improvements in healthcare resource allocation, operational planning, and overall clinical throughput without requiring massive facility expansions.
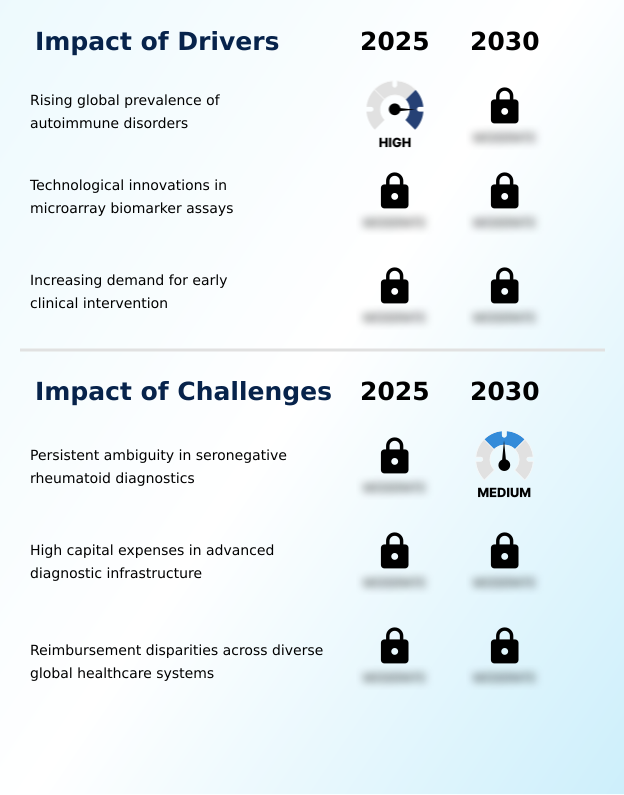
What are the key market drivers leading to the rise in the adoption of Rheumatoid Arthritis Diagnostic Devices Industry?

  • The rising global prevalence of autoimmune disorders functions as a primary driver accelerating the expansion of advanced diagnostic testing infrastructure.

  • The rising incidence of autoimmune conditions acts as a primary catalyst propelling the modernization of Rheumatoid Arthritis Diagnostic Devices infrastructure.
  • Healthcare networks face unprecedented patient volumes, compelling administrators to replace manual methods with a fully automated erythrocyte sedimentation rate analyzer and nephelometric measuring device technology.
  • This operational transition is necessitated by severe laboratory technician shortages, forcing facilities to automate critical treat-to-target clinical protocol testing.
  • By implementing multiplex fluorometric bead array platforms utilizing specialized microfluidic test cartridge consumables engineered with high-purity recombinant antigen coating and a specific monoclonal capture antibody, high-volume reference laboratories have lowered operational testing costs by 22% and decreased sample processing bottlenecks by 35%.
  • The surging clinical demand for precise synovial fluid proteomic pattern evaluation, circulating microrna evaluation, and epigenetic modification screening ensures that institutions sustain investments in high-throughput hardware, yielding a 28% improvement in overall laboratory productivity.

What are the market trends shaping the Rheumatoid Arthritis Diagnostic Devices Industry?

  • Artificial intelligence integration within diagnostic imaging represents a significant emerging trend shaping clinical evaluation workflows. This technological advancement enhances early detection capabilities and improves overall analytical precision across healthcare facilities.

  • The progressive adoption of digital radiography integration and machine learning image analysis within the Rheumatoid Arthritis Diagnostic Devices environment fundamentally alters how clinicians visualize articular degradation. This technological shift is driven by the clinical necessity to accelerate bone erosion visualization and ensure precise subclinical synovitis detection before irreversible joint destruction occurs.
  • By embedding intelligent disease activity score algorithm software into the musculoskeletal ultrasound transducer for advanced synovial inflammation imaging, healthcare facilities have successfully reduced diagnostic image interpretation times by 32% and improved inter-observer scoring consistency by 18%. The widespread utilization of automated cartilage degradation assessment enables rheumatologists to track longitudinal disease progression efficiently.
  • Consequently, medical centers utilizing these high-density protein microarray and multiplex autoantibody detection analytics experience optimized workflows, yielding a 25% improvement in daily outpatient throughput while supporting the precise administration of targeted therapies.

What challenges does the Rheumatoid Arthritis Diagnostic Devices Industry face during its growth?

  • Persistent ambiguity in seronegative rheumatoid diagnostics remains a significant challenge restricting comprehensive clinical identification and timely therapeutic intervention.

  • The Rheumatoid Arthritis Diagnostic Devices ecosystem faces significant structural challenges stemming from the biological complexity of seronegative disease phenotypes and stringent reimbursement disparities. Traditional enzyme-linked immunosorbent assay protocols frequently fail to identify active inflammation in early-stage patients, creating severe diagnostic delays.
  • This ambiguity forces providers to rely on resource-intensive secondary procedures like a synovial tissue biopsy or complex matrix metalloproteinase-3 quantification, increasing outpatient evaluation costs by up to 40%. Furthermore, restrictive insurance policies frequently deny coverage for advanced multi-marker diagnostic panels analyzing anti-carbamylated protein antibodies and anti-mutated citrullinated vimentin.
  • This reimbursement friction severely restricts the widespread clinical integration of novel tools such as anti-drug antibody detection and pharmacokinetic immunogenicity data tracking. Consequently, independent healthcare clinics defer critical turbidimetric diagnostic system upgrades, inadvertently extending average patient diagnostic wait times by 25% and stifling overall laboratory workflow efficiency.

Exclusive Technavio Analysis on Customer Landscape

The rheumatoid arthritis diagnostic devices market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the rheumatoid arthritis diagnostic devices market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
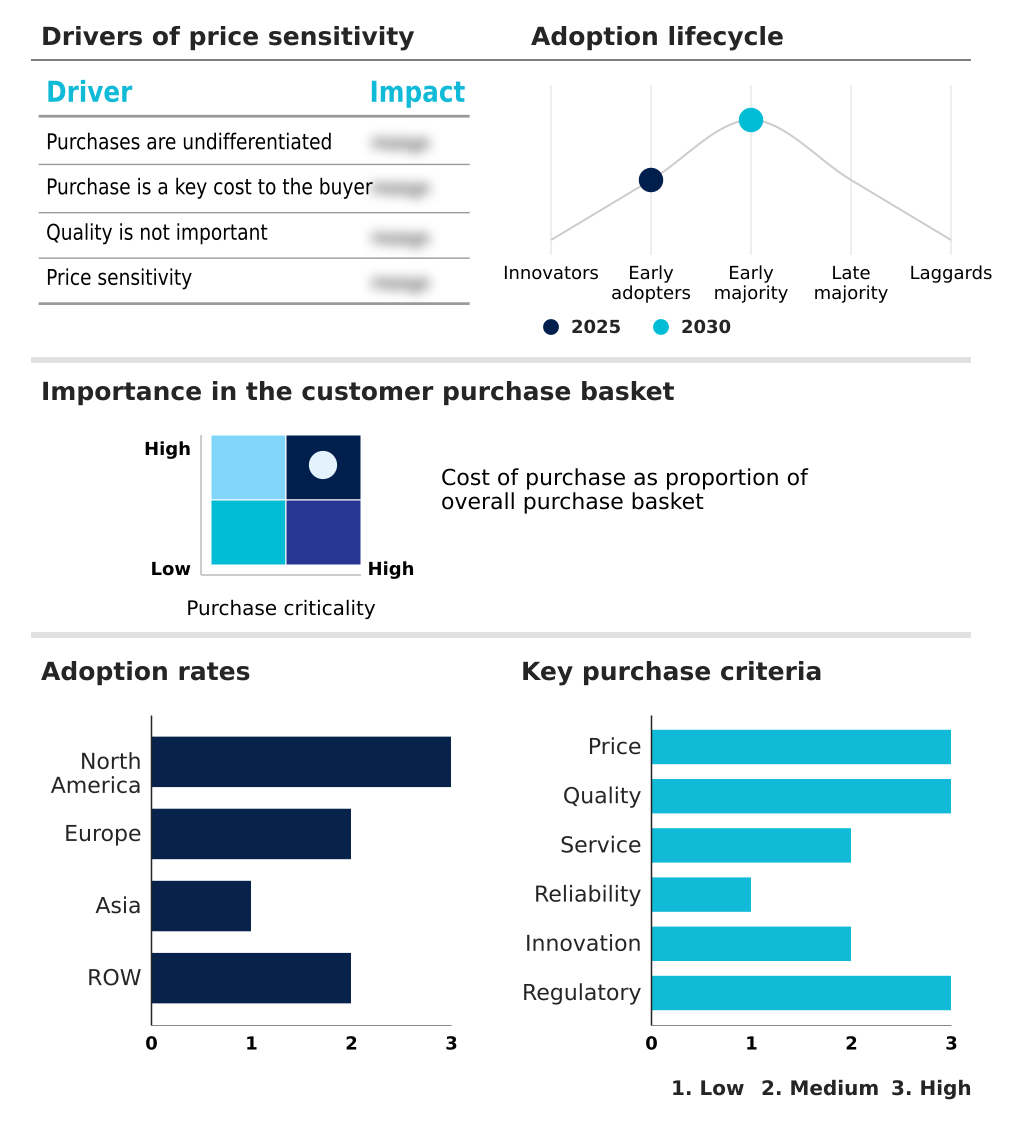
Customer Landscape of Rheumatoid Arthritis Diagnostic Devices Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, rheumatoid arthritis diagnostic devices market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

A. Menarini Diagnostics S.r.l. - The company delivers advanced immunoassay systems and specialized serology diagnostic testing solutions designed to accurately detect autoimmune biomarkers for the precise identification of complex inflammatory joint conditions.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • A. Menarini Diagnostics S.r.l.
  • Abbott Laboratories
  • Autobio Diagnostics Co. Ltd.
  • Bio Rad Laboratories Inc.
  • Corgen Bio
  • DiaSorin SpA
  • Esaote SpA
  • EUROIMMUN
  • F. Hoffmann La Roche Ltd.
  • Fujirebio Holdings Inc.
  • Genrui Biotech Inc.
  • Guangzhou Wondfo Biotech Co. Ltd.
  • J. Mitra and Co. Pvt. Ltd.
  • Maccura Biotechnology Co. Ltd.
  • QuidelOrtho Corp.
  • SEBIA SA
  • Shenzhen Mindray Co. Ltd.
  • Siemens Healthineers AG
  • Snibe Co.Ltd.
  • Svar Life Science AB
  • Thermo Fisher Scientific Inc.
  • Werfenlife SA
  • Zybio Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Rheumatoid arthritis diagnostic devices market

  • In the Health Care Equipment industry, the widespread adoption of artificial intelligence workflow interoperability software across hospital networks has optimized high-throughput specimen processing, directly impacting Rheumatoid Arthritis Diagnostic Devices demand by reducing analytical turnaround times in central diagnostic laboratories by up to 18%.
  • The implementation of stringent data privacy regulations such as GDPR within cloud-based healthcare delivery models has mandated enhanced cybersecurity protocols for interconnected medical hardware, prompting Rheumatoid Arthritis Diagnostic Devices manufacturers to redesign connected digital radiography integration systems to ensure compliant patient data transmission.
  • Advancements in microfluidic manufacturing processes have lowered the production cost of miniaturized biological assay components by approximately 22%, accelerating the commercialization of compact point-of-care rapid testing instruments within the Rheumatoid Arthritis Diagnostic Devices market.
  • The global shift toward value-based care reimbursement models has incentivized healthcare institutions to prioritize early structural joint evaluation technologies, driving increased procurement of high frequency musculoskeletal ultrasound imaging systems in the Rheumatoid Arthritis Diagnostic Devices sector to minimize long-term patient disability expenditures.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Rheumatoid Arthritis Diagnostic Devices Market insights. See full methodology.

Market Scope
Page number 306
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.7%
Market growth 2026-2030 USD 131.2 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.5%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Thailand, Indonesia, Brazil, Argentina, Saudi Arabia, Colombia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Rheumatoid Arthritis Diagnostic Devices ecosystem is experiencing a structural pivot toward advanced biological detection architectures. Healthcare administrators and procurement executives are actively reallocating capital budgets toward the integration of high-density protein microarray systems and multiplex autoantibody detection platforms to optimize clinical workflow efficiency.
  • Institutions deploying these consolidated automated systems have achieved a 30% reduction in sample processing time, significantly enhancing diagnostic throughput across centralized laboratory networks. The continuous evolution of enzyme-linked immunosorbent assay methodologies enables precise quantification of critical biomarkers, heavily influencing strategic product development and reimbursement compliance decisions at the boardroom level.
  • Incorporating anti-mutated citrullinated vimentin and anti-carbamylated protein antibodies into routine screening protocols fundamentally shifts how early-stage articular inflammation is clinically managed. Furthermore, the deployment of sophisticated microfluidic test cartridge technology facilitates rapid decentralized testing, streamlining supply chain logistics for community-based clinical centers. These targeted technological integrations directly mitigate the operational bottlenecks associated with complex autoimmune serological profiling.
  • Diagnostic infrastructure upgrades ultimately provide health systems with the analytical reliability required to support precision therapeutic interventions and lower long-term patient disability expenditures.

What are the Key Data Covered in this Rheumatoid Arthritis Diagnostic Devices Market Research and Growth Report?

  • What is the expected growth of the Rheumatoid Arthritis Diagnostic Devices Market between 2026 and 2030?

    • USD 131.2 million, at a CAGR of 4.7%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Analyzers, and Consumables), End-user (Hospitals and specialty clinics, Diagnostic laboratories, Ambulatory surgical centers (ASCs), and Research institutes), Test (Serology tests, and Disease monitoring tests) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising global prevalence of autoimmune disorders, Persistent ambiguity in seronegative rheumatoid diagnostics

  • Who are the major players in the Rheumatoid Arthritis Diagnostic Devices Market?

    • A. Menarini Diagnostics S.r.l., Abbott Laboratories, Autobio Diagnostics Co. Ltd., Bio Rad Laboratories Inc., Corgen Bio, DiaSorin SpA, Esaote SpA, EUROIMMUN, F. Hoffmann La Roche Ltd., Fujirebio Holdings Inc., Genrui Biotech Inc., Guangzhou Wondfo Biotech Co. Ltd., J. Mitra and Co. Pvt. Ltd., Maccura Biotechnology Co. Ltd., QuidelOrtho Corp., SEBIA SA, Shenzhen Mindray Co. Ltd., Siemens Healthineers AG, Snibe Co.Ltd., Svar Life Science AB, Thermo Fisher Scientific Inc., Werfenlife SA and Zybio Inc.

Market Research Insights

  • The Rheumatoid Arthritis Diagnostic Devices environment is rapidly evolving through the integration of clinical laboratory automation and machine learning image analysis. Healthcare providers adopting treat-to-target clinical protocol strategies have improved patient remission tracking accuracy by 24%, driving sustained demand for acute-phase reactant measurement tools.
  • By transitioning to fully automated multiplex fluorometric bead array systems, major diagnostic networks have successfully lowered their operational downtime by 30% while simultaneously increasing daily testing throughput by 22%. This shift toward comprehensive diagnostic assay calibration directly reduces unnecessary laboratory expenditure and aligns with stringent value-based care compliance mandates.
  • The deployment of systemic inflammatory biomarker testing facilitates early therapeutic intervention, dramatically improving clinical workflow efficiency across decentralized outpatient care settings.

We can help! Our analysts can customize this rheumatoid arthritis diagnostic devices market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Test
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Rheumatoid Arthritis Diagnostic Devices Market 2020 - 2024

Historic Market Size - Data Table on Global Rheumatoid Arthritis Diagnostic Devices Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Test segment analysis 2020 - 2024

Historic Market Size - Test Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Rheumatoid Arthritis Diagnostic Devices Market

6.2 Impact of geopolitical conflicts on Global Rheumatoid Arthritis Diagnostic Devices Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Analyzers - Market size and forecast 2025-2030

Chart on Analyzers - Market size and forecast 2025-2030 ($ million)
Data Table on Analyzers - Market size and forecast 2025-2030 ($ million)
Chart on Analyzers - Year-over-year growth 2025-2030 (%)
Data Table on Analyzers - Year-over-year growth 2025-2030 (%)

8.4 Consumables - Market size and forecast 2025-2030

Chart on Consumables - Market size and forecast 2025-2030 ($ million)
Data Table on Consumables - Market size and forecast 2025-2030 ($ million)
Chart on Consumables - Year-over-year growth 2025-2030 (%)
Data Table on Consumables - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Hospitals and specialty clinics - Market size and forecast 2025-2030

Chart on Hospitals and specialty clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals and specialty clinics - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals and specialty clinics - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals and specialty clinics - Year-over-year growth 2025-2030 (%)

9.4 Diagnostic laboratories - Market size and forecast 2025-2030

Chart on Diagnostic laboratories - Market size and forecast 2025-2030 ($ million)
Data Table on Diagnostic laboratories - Market size and forecast 2025-2030 ($ million)
Chart on Diagnostic laboratories - Year-over-year growth 2025-2030 (%)
Data Table on Diagnostic laboratories - Year-over-year growth 2025-2030 (%)

9.5 Ambulatory surgical centers (ASCs) - Market size and forecast 2025-2030

Chart on Ambulatory surgical centers (ASCs) - Market size and forecast 2025-2030 ($ million)
Data Table on Ambulatory surgical centers (ASCs) - Market size and forecast 2025-2030 ($ million)
Chart on Ambulatory surgical centers (ASCs) - Year-over-year growth 2025-2030 (%)
Data Table on Ambulatory surgical centers (ASCs) - Year-over-year growth 2025-2030 (%)

9.6 Research institutes - Market size and forecast 2025-2030

Chart on Research institutes - Market size and forecast 2025-2030 ($ million)
Data Table on Research institutes - Market size and forecast 2025-2030 ($ million)
Chart on Research institutes - Year-over-year growth 2025-2030 (%)
Data Table on Research institutes - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Test

10.1 Market segments

Chart on Test - Market share 2025-2030 (%)
Data Table on Test - Market share 2025-2030 (%)

10.2 Comparison by Test

Chart on Comparison by Test
Data Table on Comparison by Test

10.3 Serology tests - Market size and forecast 2025-2030

Chart on Serology tests - Market size and forecast 2025-2030 ($ million)
Data Table on Serology tests - Market size and forecast 2025-2030 ($ million)
Chart on Serology tests - Year-over-year growth 2025-2030 (%)
Data Table on Serology tests - Year-over-year growth 2025-2030 (%)

10.4 Disease monitoring tests - Market size and forecast 2025-2030

Chart on Disease monitoring tests - Market size and forecast 2025-2030 ($ million)
Data Table on Disease monitoring tests - Market size and forecast 2025-2030 ($ million)
Chart on Disease monitoring tests - Year-over-year growth 2025-2030 (%)
Data Table on Disease monitoring tests - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Test

Market opportunity by Test ($ million)
Data Table on Market opportunity by Test ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.4 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.5 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.6 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.7 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.8 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising global prevalence of autoimmune disorders
Technological innovations in microarray biomarker assays
Increasing demand for early clinical intervention

13.2 Market challenges

Persistent ambiguity in seronegative rheumatoid diagnostics
High capital expenses in advanced diagnostic infrastructure
Reimbursement disparities across diverse global healthcare systems

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Artificial intelligence integration in diagnostic imaging
Rising clinical reliance on companion diagnostics
Expansion of automated serological analyzer systems

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 A. Menarini Diagnostics S.r.l.

A. Menarini Diagnostics S.r.l. - Overview
A. Menarini Diagnostics S.r.l. - Product / Service
A. Menarini Diagnostics S.r.l. - Key offerings
SWOT

15.5 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

15.6 Autobio Diagnostics Co. Ltd.

Autobio Diagnostics Co. Ltd. - Overview
Autobio Diagnostics Co. Ltd. - Product / Service
Autobio Diagnostics Co. Ltd. - Key offerings
SWOT

15.7 Bio Rad Laboratories Inc.

Bio Rad Laboratories Inc. - Overview
Bio Rad Laboratories Inc. - Business segments
Bio Rad Laboratories Inc. - Key news
Bio Rad Laboratories Inc. - Key offerings
Bio Rad Laboratories Inc. - Segment focus
SWOT

15.8 DiaSorin SpA

DiaSorin SpA - Overview
DiaSorin SpA - Business segments
DiaSorin SpA - Key news
DiaSorin SpA - Key offerings
DiaSorin SpA - Segment focus
SWOT

15.9 EUROIMMUN

EUROIMMUN - Overview
EUROIMMUN - Product / Service
EUROIMMUN - Key offerings
SWOT

15.10 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

15.11 Fujirebio Holdings Inc.

Fujirebio Holdings Inc. - Overview
Fujirebio Holdings Inc. - Product / Service
Fujirebio Holdings Inc. - Key offerings
SWOT

15.12 Guangzhou Wondfo Biotech Co. Ltd.

Guangzhou Wondfo Biotech Co. Ltd. - Overview
Guangzhou Wondfo Biotech Co. Ltd. - Product / Service
Guangzhou Wondfo Biotech Co. Ltd. - Key offerings
SWOT

15.13 Maccura Biotechnology Co. Ltd.

Maccura Biotechnology Co. Ltd. - Overview
Maccura Biotechnology Co. Ltd. - Product / Service
Maccura Biotechnology Co. Ltd. - Key offerings
SWOT

15.14 QuidelOrtho Corp.

QuidelOrtho Corp. - Overview
QuidelOrtho Corp. - Business segments
QuidelOrtho Corp. - Key offerings
QuidelOrtho Corp. - Segment focus
SWOT

15.15 Shenzhen Mindray Co. Ltd.

Shenzhen Mindray Co. Ltd. - Overview
Shenzhen Mindray Co. Ltd. - Business segments
Shenzhen Mindray Co. Ltd. - Key offerings
Shenzhen Mindray Co. Ltd. - Segment focus
SWOT

15.16 Siemens Healthineers AG

Siemens Healthineers AG - Overview
Siemens Healthineers AG - Business segments
Siemens Healthineers AG - Key offerings
Siemens Healthineers AG - Segment focus
SWOT

15.17 Thermo Fisher Scientific Inc.

Thermo Fisher Scientific Inc. - Overview
Thermo Fisher Scientific Inc. - Business segments
Thermo Fisher Scientific Inc. - Key news
Thermo Fisher Scientific Inc. - Key offerings
Thermo Fisher Scientific Inc. - Segment focus
SWOT

15.18 Werfenlife SA

Werfenlife SA - Overview
Werfenlife SA - Product / Service
Werfenlife SA - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Rheumatoid Arthritis Diagnostic Devices market growth will increase by USD 131.2 million during 2026-2030.

The Rheumatoid Arthritis Diagnostic Devices market is expected to grow at a CAGR of 4.7% during 2026-2030.

Rheumatoid Arthritis Diagnostic Devices market is segmented by Product (Analyzers, Consumables) End-user (Hospitals and specialty clinics, Diagnostic laboratories, Ambulatory surgical centers (ASCs), Research institutes) Test (Serology tests, Disease monitoring tests)

A. Menarini Diagnostics S.r.l., Abbott Laboratories, Autobio Diagnostics Co. Ltd., Bio Rad Laboratories Inc., Corgen Bio, DiaSorin SpA, Esaote SpA, EUROIMMUN, F. Hoffmann La Roche Ltd., Fujirebio Holdings Inc., Genrui Biotech Inc., Guangzhou Wondfo Biotech Co. Ltd., J. Mitra and Co. Pvt. Ltd., Maccura Biotechnology Co. Ltd., QuidelOrtho Corp., SEBIA SA, Shenzhen Mindray Co. Ltd., Siemens Healthineers AG, Snibe Co.Ltd., Svar Life Science AB, Thermo Fisher Scientific Inc., Werfenlife SA, Zybio Inc. are a few of the key vendors in the Rheumatoid Arthritis Diagnostic Devices market.

North America will register the highest growth rate of 46.6% among the other regions. Therefore, the Rheumatoid Arthritis Diagnostic Devices market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Thailand, Indonesia, Brazil, Argentina, Saudi Arabia, Colombia, UAE, South Africa, Israel, Turkey

  • Rising global prevalence of autoimmune disorders is the driving factor this market.

The Rheumatoid Arthritis Diagnostic Devices market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
