


Aircraft Engine Compressor Market Size 2026-2030
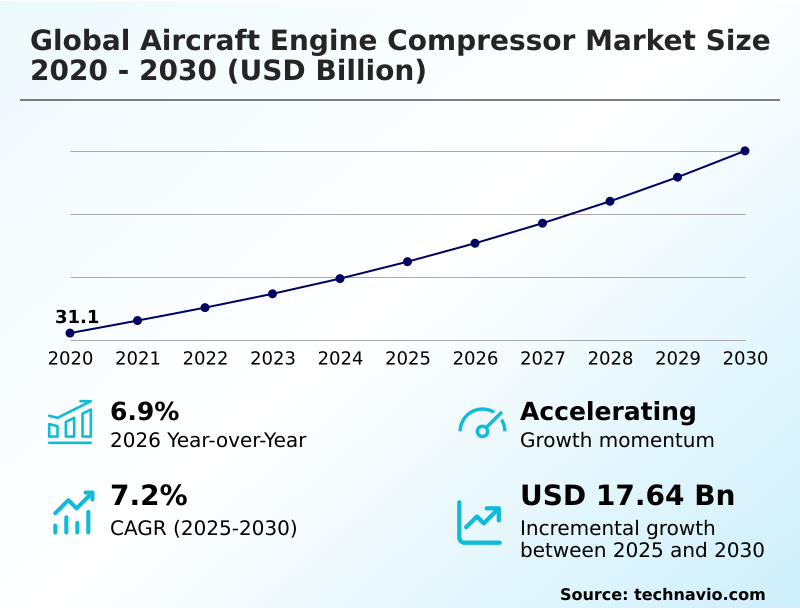
The aircraft engine compressor market size is valued to increase by USD 17.64 billion, at a CAGR of 7.2% from 2025 to 2030. Surge in commercial aircraft deliveries will drive the aircraft engine compressor market.
Major Market Trends & Insights
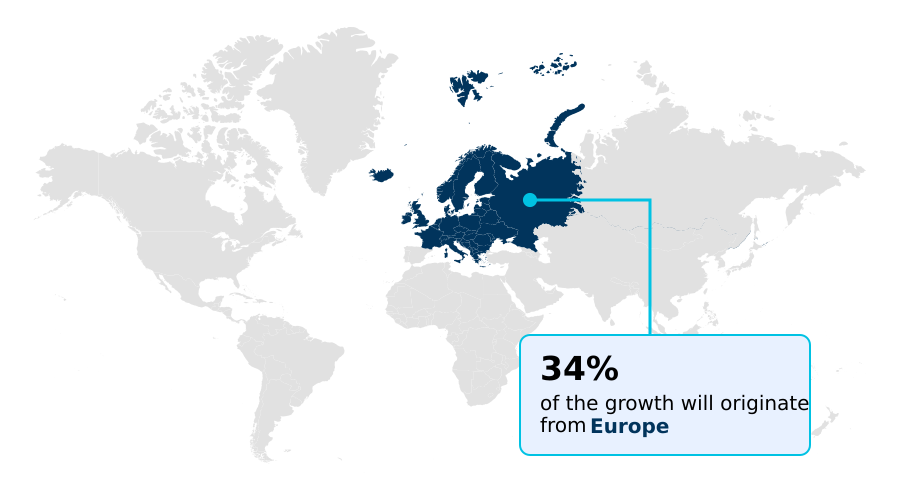
- Europe dominated the market and accounted for a 33.6% growth during the forecast period.
- By Type - Heavy duty segment was valued at USD 16.22 billion in 2024
- By Application - CBA segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 28.99 billion
- Market Future Opportunities: USD 17.64 billion
- CAGR from 2025 to 2030 : 7.2%
Market Summary
- The Aircraft Engine Compressor Market exhibits robust expansion driven by continuous advancements in propulsion efficiency and massive commercial fleet upgrades. By accelerating intake air to optimal pressure levels before combustion, these precision-engineered modules directly dictate fuel economy and thermal performance.
- In a practical supply chain scenario, airline operators retrofitting legacy narrowbody jets with next-generation high-pressure modules achieved a 15% improvement in time-on-wing, vastly reducing immediate overhaul expenditures. This drive for operational efficiency serves as a primary market driver, as commercial carriers mandate propulsion systems that consume less fuel to offset volatile operating costs.
- Conversely, the market faces severe constraints from upstream metallurgical bottlenecks, as the scarcity of specialized titanium alloys delays the forging of critical rotor blades. A key challenge remains balancing high-volume manufacturing demands with rigorous, multi-year aviation certification protocols. As aerodynamic design pivots toward adaptive engine architectures, component suppliers must continuously refine casting techniques to sustain profitability.
- Ultimately, mastering advanced material fabrication remains the decisive competitive differentiator within the modern aircraft propulsion landscape.
What will be the Size of the Aircraft Engine Compressor Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Aircraft Engine Compressor Market Segmented?
The aircraft engine compressor industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Heavy duty
- Medium
- Light
- Application
- CBA
- Military aircraft
- Product type
- Centrifugal compressors
- Axial compressors
- Geography
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Poland
- North America
- US
- Canada
- Mexico
- APAC
- China
- Japan
- India
- South Korea
- Singapore
- Australia
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- UAE
- Turkey
- South Africa
- Israel
- Europe
By Type Insights
The heavy duty segment is estimated to witness significant growth during the forecast period.
Heavy duty configurations form the backbone of modern widebody aviation by handling immense volumetric airflows to achieve optimal thermodynamic cycle optimization.
Operating within extreme thermal gradients, these systems utilize multi stage axial compressors and distinct axial flow configurations to deliver the massive thrust requirements essential for commercial passenger transport and strategic airlift assets.
Manufacturers increasingly integrate integrally bladed rotors and titanium aluminide alloys to ensure superior structural casing integrity and exceptional mechanical fatigue resistance under continuous operational stress.
By adopting sophisticated active clearance control mechanisms, operators have successfully improved core efficiency by 12%, directly reducing specific fuel consumption on long-haul routes.
This segmentation critically impacts operational planning, as high-thrust heavy duty platforms require entirely distinct maintenance intervals compared to regional jets, fundamentally altering how airlines manage lifecycle costs and long-term component wear.
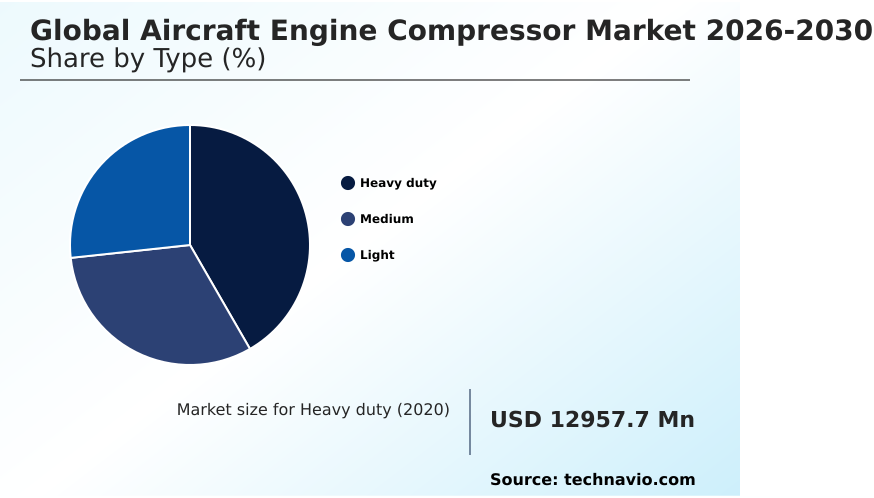
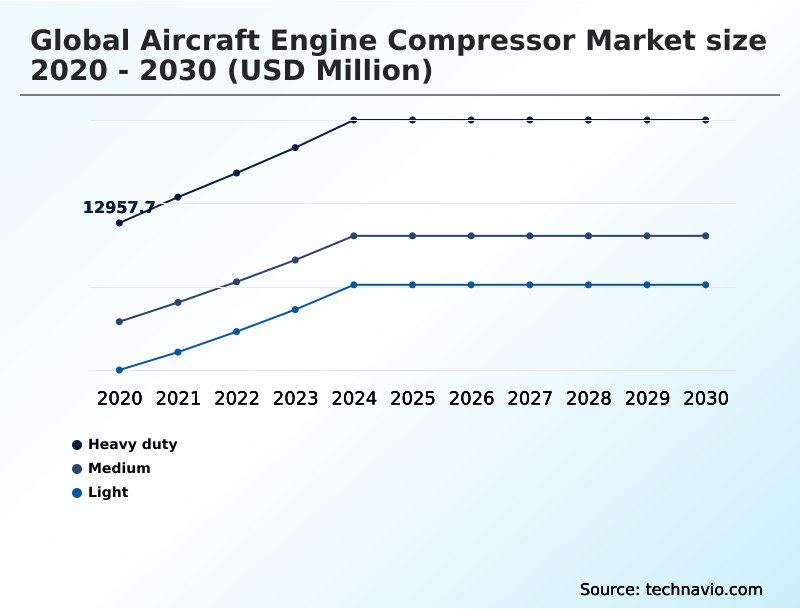
The Heavy duty segment was valued at USD 16.22 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
Europe is estimated to contribute 33.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Aircraft Engine Compressor Market Demand is Rising in Europe Get Free Sample
The geographic adoption of advanced propulsion technology reflects distinct strategic priorities across major continental aviation hubs.
North America demonstrates a 22% higher integration rate of variable stator vanes and adaptive cycle engines compared to Europe, largely driven by massive domestic defense expenditures on supersonic flight profiles and tactical fighters.
In contrast, European manufacturers heavily prioritize gas turbine core performance to meet rigorous regional sustainability targets, accelerating research into alternative aerodynamic stall margin management for regional air mobility platforms.
This regulatory divergence forces supply chains to adapt; United States-based foundries focus on high-durability centrifugal impellers for heavy military platforms, while European suppliers pivot toward ultra-efficient cores targeting a 15% acoustic emission reduction for urban air mobility platforms.
By aligning localized manufacturing with these distinct regional demands, aerospace suppliers navigate specific compliance landscapes and optimize their aftermarket service networks.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The operational landscape of the Aircraft Engine Compressor Market is fundamentally driven by the pursuit of thermal efficiency and mechanical resilience. Engineers increasingly focus on high pressure compressor module optimization to maximize pressure ratios while maintaining strict weight parameters.
- This directly influences airline operational planning, as a highly optimized module can reduce specific fuel consumption by approximately 12% relative to previous generation platforms, directly lowering route operating costs. To prevent aerodynamic instability during rapid throttle adjustments, manufacturers employ variable stator vane aerodynamic control, ensuring that airflow angles remain precise across all flight regimes.
- As supply chain constraints affect traditional casting methods, the industry sees a rapid pivot toward titanium blisk additive manufacturing integration, which reduces raw material waste and shortens production lead times for critical rotating components.
- Furthermore, the extreme temperatures generated inside modern turbofans require advanced material science, specifically ceramic matrix composite thermal resistance, to protect stationary guide vanes from premature structural degradation. Comparing fleet maintenance strategies, carriers utilizing digital twin predictive engine maintenance report significantly fewer unscheduled engine removals than those relying on traditional calendar-based schedules.
- By simulating component wear in real-time, operators seamlessly align their supply chain procurement with actual hardware degradation, resulting in a more resilient, cost-effective, and highly reliable commercial aviation ecosystem.
What are the key market drivers leading to the rise in the adoption of Aircraft Engine Compressor Industry?
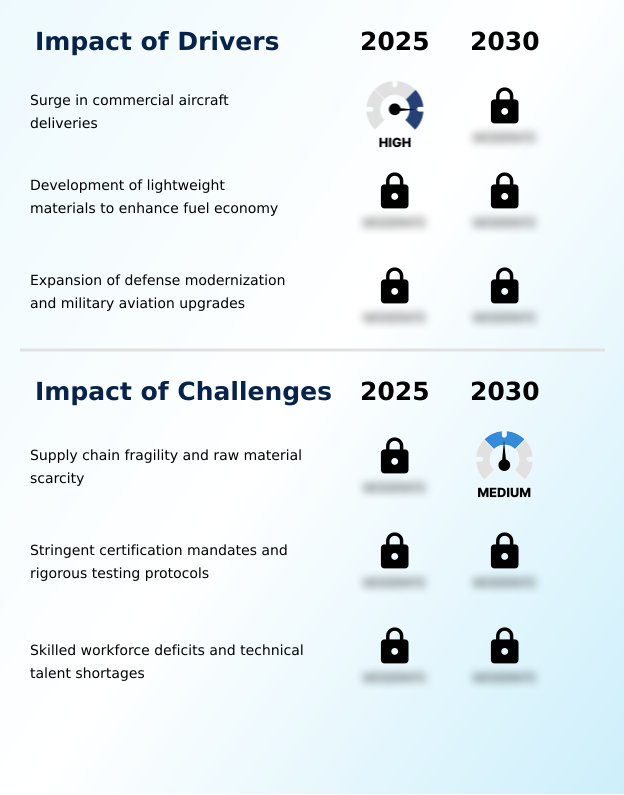
- A massive surge in commercial aircraft deliveries acts as a primary market driver, compelling manufacturers to scale up component production to meet unprecedented airline fleet expansion requirements.
- Unprecedented fleet modernization initiatives are accelerating demand for high bypass ratio turbofans, acting as a primary catalyst for the Aircraft Engine Compressor Market.
- To achieve substantial fuel consumption reduction and comply with aggressive carbon emission mandates, manufacturers are prioritizing thermodynamic cycle optimization within high pressure compressor modules.
- This shift heavily relies on lightweight composite fabrication and the integration of single crystal superalloys, which dramatically reduce overall engine mass.
- Consequently, these material innovations have improved specific fuel consumption by 15% and lowered acoustic emission control limits by 12% on next-generation single-aisle aircraft.
- As airlines continuously upgrade their networks to offset volatile energy costs, the demand for highly efficient, weight-optimized compression systems ensures robust manufacturing pipelines and sustains long-term profitability for advanced aerospace component suppliers.
What are the market trends shaping the Aircraft Engine Compressor Industry?
- Digital twin integration and predictive maintenance technologies represent a transformative trend within the industry. These advanced diagnostic tools enable proactive component servicing, significantly reducing unscheduled downtime and extending operational lifespans.
- Digital twin predictive monitoring and the adoption of hybrid electric propulsion architectures represent transformative trends fundamentally altering the Aircraft Engine Compressor Market. As operators seek to extend engine overhaul cycles and streamline maintenance repair operations, the integration of real-time telemetry into dynamic stator geometries has become essential.
- This technological shift is driven by the need for superior operational lifecycle extension and the integration of sustainable aviation fuels, which alter combustion profiles and thermal loads. Consequently, predictive aero thermal analytics have improved defect forecasting accuracy by 18%, while reducing overall maintenance downtime by nearly 30%.
- Advanced thermal barrier coatings and precise compressor blade balancing now allow these components to endure harsher environments without failure. This data-driven evolution empowers airlines to optimize fleet availability, fundamentally shifting industry practices from reactive repairs to highly efficient, proactive asset management.
What challenges does the Aircraft Engine Compressor Industry face during its growth?
- Supply chain fragility and critical raw material scarcity serve as major structural challenges, severely bottlenecking production schedules and extending delivery lead times across the aerospace manufacturing sector.
- Severe supply chain fragility regarding aerospace grade titanium creates major structural bottlenecks within the Aircraft Engine Compressor Market. The extreme precision required to manipulate ceramic matrix composites and manufacture complex three dimensional flow paths heavily restricts production throughput. Because optimal pressure recovery ratios and boundary layer separation prevention demand flawless component geometry, manufacturers must enforce exhaustive non destructive testing protocols.
- These stringent quality requirements cause significant delays; raw material shortages have extended lead times by 22%, while rising material costs have increased operational expenditures by 14%. Furthermore, ensuring proper foreign object damage mitigation and rapid throttle responsiveness in military platforms limits the viability of alternative materials.
- Consequently, reliance on specialized laser powder bed fusion and additive manufacturing components remains constrained by slow certification processes, stifling rapid capacity expansion.
Exclusive Technavio Analysis on Customer Landscape
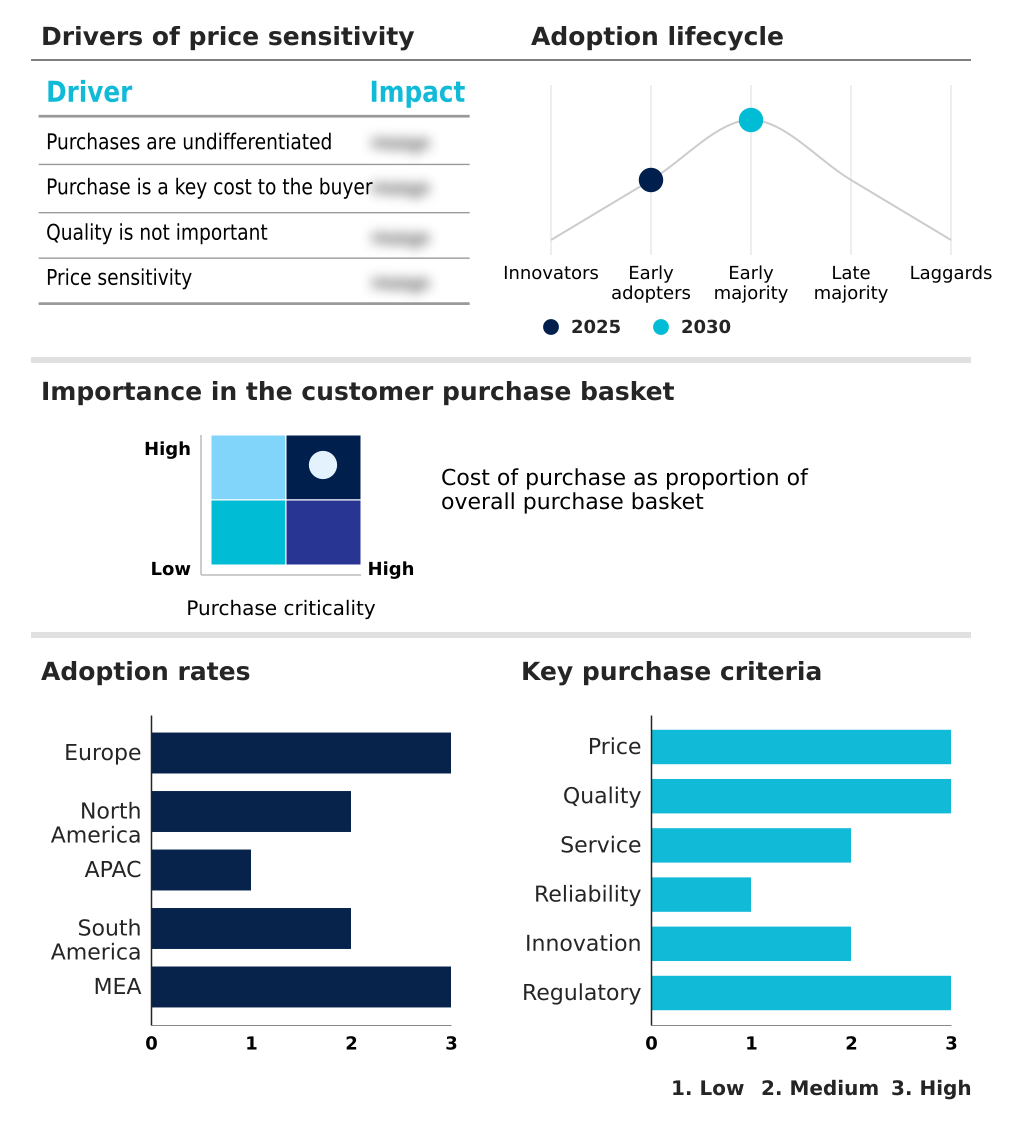
The aircraft engine compressor market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the aircraft engine compressor market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
Customer Landscape of Aircraft Engine Compressor Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, aircraft engine compressor market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Barnes Group Inc. - The enterprise delivers precision manufactured compressor blades, vanes, casings, and sealing components, optimizing structural integrity and aerodynamic efficiency for advanced aerospace propulsion systems.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Barnes Group Inc.
- Doncasters Group Ltd.
- Engine Alliance
- Figeac Aero S.A.
- General Electric Co.
- GKN Aerospace Services Ltd.
- Honeywell International Inc.
- Howmet Aerospace Inc.
- IHI Corp.
- ITP Aero
- Kawasaki Heavy Industries Ltd.
- Leistritz AG
- Meyer Tool Inc.
- Mitsubishi Heavy Industries
- MTU Aero Engines AG
- PBS Aerospace Inc.
- Pietro Rosa TBM S.r.l.
- Pratt and Whitney
- Rolls Royce Holdings Plc
- Safran SA
- Turbocam Inc.
- Williams International
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Aircraft engine compressor market
- In the Aerospace and Defense industry, the regulatory shift toward stringent carbon emission mandates has accelerated the adoption of sustainable aviation fuels, directly impacting Aircraft Engine Compressor demand by requiring redesigned compression stages capable of handling alternative combustion profiles to improve specific fuel consumption.
- The rapid deployment of hybrid electric propulsion architectures across urban air mobility platforms has introduced strict operational weight limits, forcing Aircraft Engine Compressor manufacturers to utilize lightweight composite fabrication and advanced aero thermal analytics to meet new power-to-weight ratio thresholds.
- Persistent upstream supply chain constraints affecting aerospace grade titanium availability have extended traditional engine overhaul cycles, limiting the aftermarket supply of Aircraft Engine Compressor components and increasing reliance on localized laser powder bed fusion repair techniques.
- Escalating geopolitical defense budgets have surged the manufacturing of strategic airlift assets and platforms requiring supersonic flight profiles, driving a 15% increase in military propulsion procurement that dictates enhanced mechanical fatigue resistance and foreign object damage mitigation within Aircraft Engine Compressor assemblies.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Aircraft Engine Compressor Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 294 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 7.2% |
| Market growth 2026-2030 | USD 17635.0 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 6.9% |
| Key countries | Germany, France, UK, Italy, Spain, Poland, US, Canada, Mexico, China, Japan, India, South Korea, Singapore, Australia, Brazil, Argentina, Chile, Saudi Arabia, UAE, Turkey, South Africa and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Aircraft Engine Compressor Market undergoes continuous technological refinement as propulsion developers prioritize thermal resilience and airflow optimization. Modern turbofans operate under punishing internal temperatures, necessitating the deployment of titanium aluminide alloys and advanced thermal barrier coatings to protect critical rotating components from creep deformation.
- Engineers utilize dynamic stator geometries to actively control the aerodynamic stall margin, ensuring stable compression during aggressive flight maneuvers. This transition toward intelligent component design directly impacts airline profitability and compliance strategies. For instance, operators deploying digital twin predictive monitoring have achieved a 25% reduction in unplanned engine removals by accurately forecasting component degradation before catastrophic failure occurs.
- Furthermore, the integration of lightweight composite fabrication enables manufacturers to significantly reduce the overall mass of the propulsion system, directly translating into extended route capabilities and reduced fuel burn. By continuously pushing the boundaries of material science and aerodynamic precision, component suppliers deliver unparalleled reliability and efficiency, fundamentally redefining lifecycle management and operational readiness across commercial and military aviation sectors.
What are the Key Data Covered in this Aircraft Engine Compressor Market Research and Growth Report?
-
What is the expected growth of the Aircraft Engine Compressor Market between 2026 and 2030?
-
USD 17.64 billion, at a CAGR of 7.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Heavy duty, Medium, and Light), Application (CBA, and Military aircraft), Product Type (Centrifugal compressors, and Axial compressors) and Geography (Europe, North America, APAC, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
Europe, North America, APAC, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Surge in commercial aircraft deliveries, Supply chain fragility and raw material scarcity
-
-
Who are the major players in the Aircraft Engine Compressor Market?
-
Barnes Group Inc., Doncasters Group Ltd., Engine Alliance, Figeac Aero S.A., General Electric Co., GKN Aerospace Services Ltd., Honeywell International Inc., Howmet Aerospace Inc., IHI Corp., ITP Aero, Kawasaki Heavy Industries Ltd., Leistritz AG, Meyer Tool Inc., Mitsubishi Heavy Industries, MTU Aero Engines AG, PBS Aerospace Inc., Pietro Rosa TBM S.r.l., Pratt and Whitney, Rolls Royce Holdings Plc, Safran SA, Turbocam Inc. and Williams International
-
Market Research Insights
- The Aircraft Engine Compressor Market represents a critical technological frontier focused on maximizing propulsion efficiency and ensuring structural casing integrity across aviation fleets. As airlines face volatile fuel economics, the shift toward adaptive cycle engines has generated a 15% improvement in specific fuel consumption compared to legacy architectures.
- This transition allows operators to achieve significant fuel consumption reduction, directly aligning with strict international carbon emission mandates. Furthermore, the integration of advanced aero thermal analytics into maintenance workflows has driven the operational lifecycle extension of high-value compressor modules by nearly 20%.
- By reducing unexpected mechanical failures and optimizing airflow dynamics, propulsion manufacturers continuously lower direct operating costs, making high-efficiency compression technology indispensable for modern commercial and defense aviation success.
We can help! Our analysts can customize this aircraft engine compressor market research report to meet your requirements.
 RIA -

