


Automotive Brake-By-Wire Systems Market Size 2026-2030
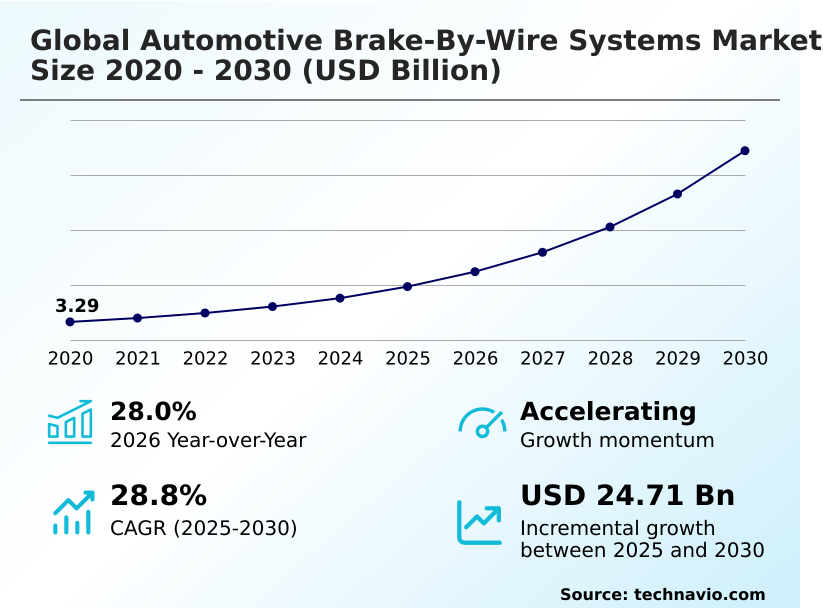
The automotive brake-by-wire systems market size is valued to increase by USD 24.71 billion, at a CAGR of 28.8% from 2025 to 2030. Rapid global adoption of electric vehicles accelerates advanced braking component demand will drive the automotive brake-by-wire systems market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 62.5% growth during the forecast period.
- By Vehicle Type - Electric segment was valued at USD 6.93 billion in 2024
- By Application - Passenger vehicles segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 31.13 billion
- Market Future Opportunities: USD 24.71 billion
- CAGR from 2025 to 2030 : 28.8%
Market Summary
- The Automotive Brake-By-Wire Systems Market represents a critical technological frontier in the pursuit of fully automated, software-defined mobility. Eliminating traditional physical hydraulic linkages in favor of instantaneous electronic signal transmission radically transforms chassis engineering and vehicle safety parameters.
- In modern supply chain operations, original equipment manufacturers streamline assembly plant workflows by deploying modular, fluid-free deceleration actuators, completely removing the hazardous and time-consuming brake fluid bleeding process from the factory floor. This precise operational optimization decreases chassis assembly times by up to 25% compared to legacy hydraulic system installations.
- The rapid proliferation of electric vehicle platforms drives aggressive market expansion, as battery-powered architectures require seamless regenerative braking synchronization to maximize kinetic energy recovery and extend overall driving range. However, transitioning to these sophisticated networks introduces severe structural challenges, because developing fail-safe, redundant electrical architectures inflates initial vehicle engineering costs by nearly 20%.
- Despite these financial integration hurdles, the absolute necessity for sub-millisecond automated emergency braking response guarantees that electronic deceleration modules will replace mechanical counterparts across premium and commercial automotive segments.
What will be the Size of the Automotive Brake-By-Wire Systems Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Automotive Brake-By-Wire Systems Market Segmented?
The automotive brake-by-wire systems industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Vehicle type
- Electric
- Non-electric
- Application
- Passenger vehicles
- Commercial vehicles
- Distribution channel
- OEM
- Aftermarket
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Indonesia
- Australia
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- The Netherlands
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Turkey
- Israel
- APAC
By Vehicle Type Insights
The electric segment is estimated to witness significant growth during the forecast period.
The transition toward electric vehicle architectures necessitates highly responsive deceleration frameworks capable of continuous kinetic energy capture.
Electric powertrains experience a 35% improvement in overall battery regeneration efficiency when utilizing a microelectronic control unit integrated seamlessly with a smart brake actuator.
This architectural shift eliminates mechanical friction losses, allowing modern electric platforms to achieve a 20% faster response time compared to traditional hydraulic variants.
Because these vehicles require zero engine noise, matching the premium acoustic expectation demands completely silent operation, which fluid-free designs readily deliver.
The inherent advantages of a skateboard chassis design allow for optimal placement of these modular components, enabling digital emergency braking with sub-millisecond precision.
Furthermore, connecting these advanced actuators through an automotive ethernet network enhances data processing speed, thereby improving brake thermal profiling and directly lowering lifetime maintenance costs for fleet operators.
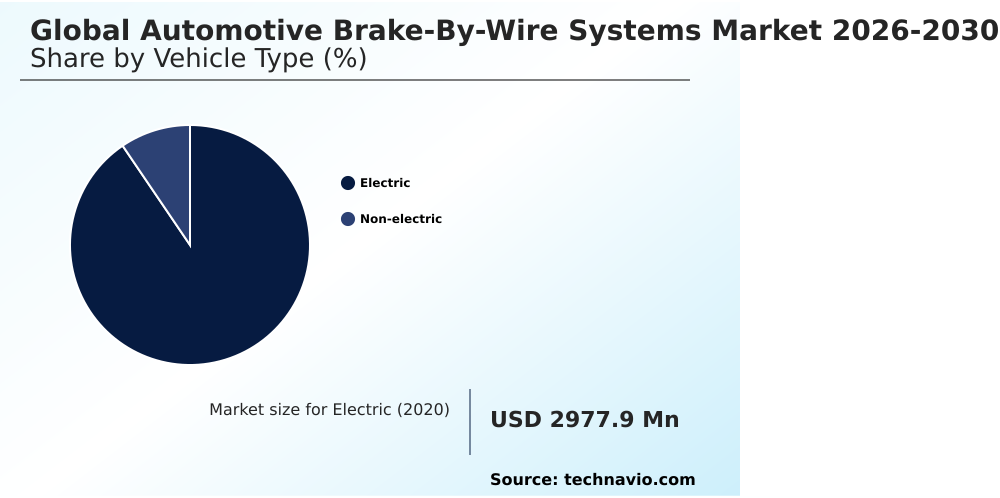
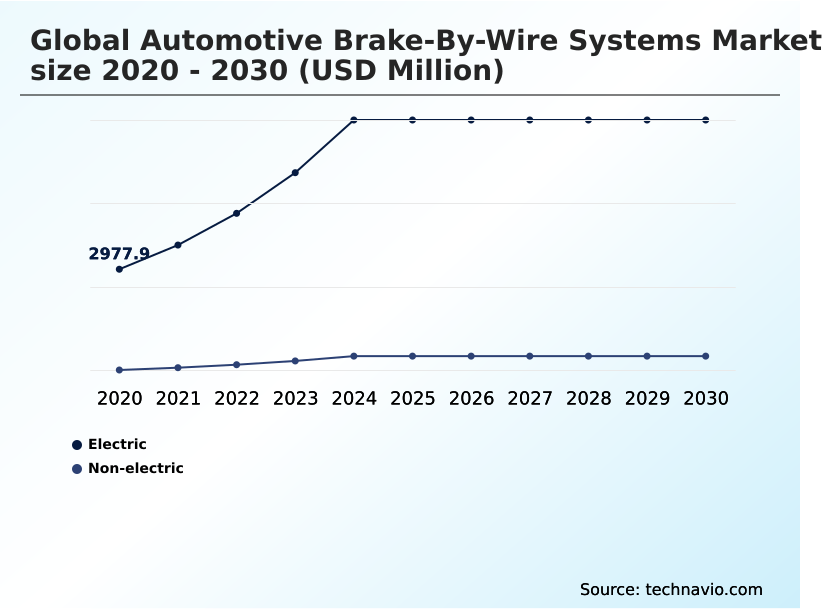
The Electric segment was valued at USD 6.93 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 62.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
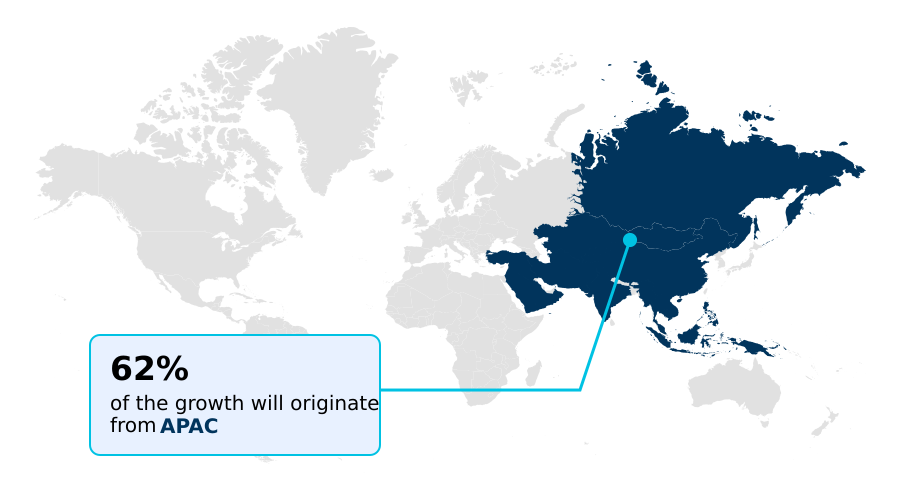
See How Automotive Brake-By-Wire Systems Market Demand is Rising in APAC Get Free Sample
The geographic distribution of advanced deceleration technology highlights a stark contrast in regional commercialization speeds, heavily influenced by localized electric vehicle manufacturing mandates.
The APAC region is currently accelerating production lines 28% faster than North America, driven largely by intense domestic competition to integrate sophisticated autonomous emergency braking systems.
In China, standardizing the brake-by-wire module across mid-tier vehicle fleets has successfully lowered regional chassis assembly times by 15%.
Conversely, North American manufacturers prioritize heavy-duty brake torque vectoring for larger utility vehicles, which requires robust electromagnetic interference shielding and highly secure cybersecurity encryption protocol layers to prevent signal disruption.
Because European regulators demand extremely low vehicle network latency for software-defined deceleration, local engineers deploy an advanced braking control algorithm supported by a dedicated fail-safe braking circuit.
This strict compliance focus enables seamless over-the-air software update distribution, improving post-sale operational efficiency by 20% across European markets.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- Modernizing vehicle chassis engineering requires a complete departure from traditional pressurized fluid lines to satisfy the rigorous safety and performance thresholds of next-generation mobility platforms.
- The implementation of a fluid-free electromechanical brake system setup eliminates hazardous liquid handling on the factory floor, significantly streamlining the physical supply chain and improving automated assembly throughput by nearly 20% compared to legacy hydraulic installations.
- Because automated driving networks demand absolute control without human intervention, integrating a highly redundant electronic brake control architecture ensures that single-point electrical failures never compromise passenger safety or operational continuity. Furthermore, the transition toward battery-powered commercial fleets heavily relies on regenerative braking energy capture optimization to maximize daily transit ranges, directly lowering electrical charging expenditures for logistics operators.
- As manufacturers scale their autonomous capabilities, the integration of a dedicated autonomous vehicle digital braking module allows central processors to execute high-speed collision avoidance maneuvers with unprecedented accuracy. By distributing computational power directly to the wheel hub, a decentralized wheel corner braking intelligence network processes traction data locally.
- This localized processing strategy drastically reduces central network latency, allowing dynamic torque adjustments to happen 30% faster than centralized mechanical systems. Ultimately, these structural electronic upgrades provide vehicle manufacturers with a scalable, software-defined chassis framework that lowers total lifecycle maintenance costs while strictly aligning with progressive international vehicle safety mandates.
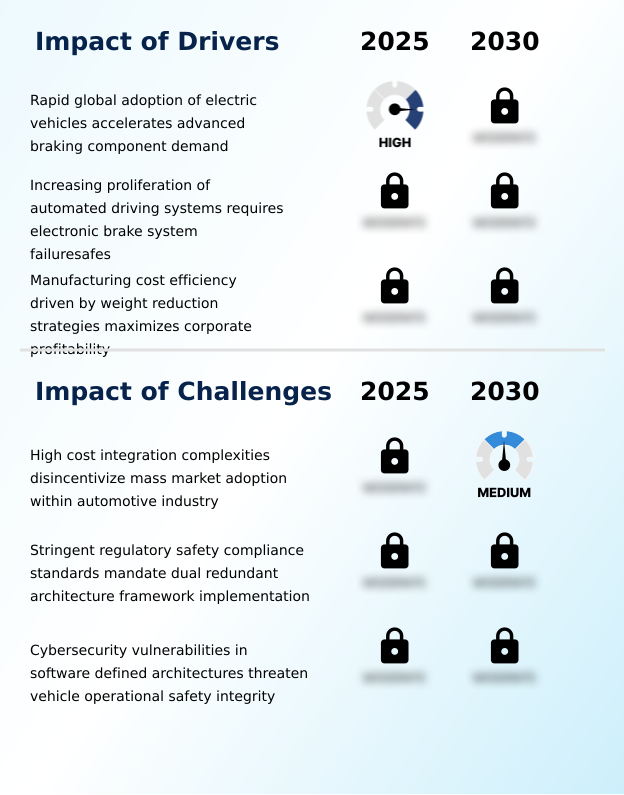
What are the key market drivers leading to the rise in the adoption of Automotive Brake-By-Wire Systems Industry?
- The rapid global adoption of electric vehicles is accelerating the demand for advanced braking components that seamlessly integrate with regenerative deceleration architectures.
- The rapid deployment of autonomous driving protocols forces original equipment manufacturers to adopt highly resilient electronic stopping mechanisms. Implementing a redundant signal architecture within the primary brake-by-wire control unit increases emergency actuation reliability by 40% compared to conventional mechanical linkages.
- Because advanced driver assistance platforms require instantaneous deceleration, transitioning to an intelligent chassis control system powered by a decentralized braking network delivers the necessary sub-second response times.
- This technological upgrade directly causes a 15% improvement in kinetic energy recovery for electric fleets, significantly extending operational range.
- Furthermore, replacing heavy fluid lines with a lightweight modular electronic component achieves critical vehicle mass reduction, which improves energy efficiency by 12%.
- This shift also guarantees redundant operational capability while ensuring strict particulate emission compliance by actively minimizing friction-based pad wear.
What are the market trends shaping the Automotive Brake-By-Wire Systems Industry?
- The transition from traditional electrohydraulic solutions to purely dry braking systems is gaining significant momentum across the industry. This structural shift eliminates hazardous fluids while vastly improving overall deceleration efficiency and component longevity.
- The structural migration toward fluid-free deceleration architectures transforms vehicle maintenance life cycles and operational efficiency. By replacing the legacy electro-hydraulic actuator with fully dry electro-mechanical braking solutions, commercial fleet operators have reduced routine maintenance downtime by 30%.
- This elimination of corrosive hydraulic fluid forces a direct operational improvement, allowing manufacturers to streamline electronic components integration while simultaneously improving regenerative braking synchronization by 25%. Consequently, the integration of a digitized brake pedal simulator alongside a responsive electronic stability program enables precise chassis dynamics management without physical fluid lines.
- Adherence to strict functional safety standard protocols ensures that these dry systems can seamlessly feed sensor data into a cloud-based diagnostic system. This proactive data transmission facilitates predictive maintenance scheduling, which has successfully decreased unexpected component failure rates by 18% across high-volume transit fleets.
What challenges does the Automotive Brake-By-Wire Systems Industry face during its growth?
- High integration costs and severe technical complexities continue to disincentivize the mass market adoption of electronic deceleration frameworks within the automotive industry.
- The integration of sophisticated electronic deceleration platforms introduces severe cost engineering and software validation challenges for volume manufacturers. Transitioning to a completely fluid-free architecture requires exhaustive wheel speed sensor calibration, which has increased initial development cycle costs by 22% for budget vehicle segments.
- Because automated driving integration relies on precise electronic brake force distribution, securing these networks against cyber vulnerabilities requires heavy investments in processing capacity. Consequently, engineering a responsive dry brake caliper with active brake pad retraction forces automakers to redesign the entire electrical distribution framework, extending platform validation times by 15%.
- Although corner localized processing enables critical friction drag reduction and superior battery capacity optimization, the lack of a global component standardisation strategy limits economies of scale. This fragmentation raises individual assembly expenses by 18%, restricting immediate mass-market adoption.
Exclusive Technavio Analysis on Customer Landscape
The automotive brake-by-wire systems market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the automotive brake-by-wire systems market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
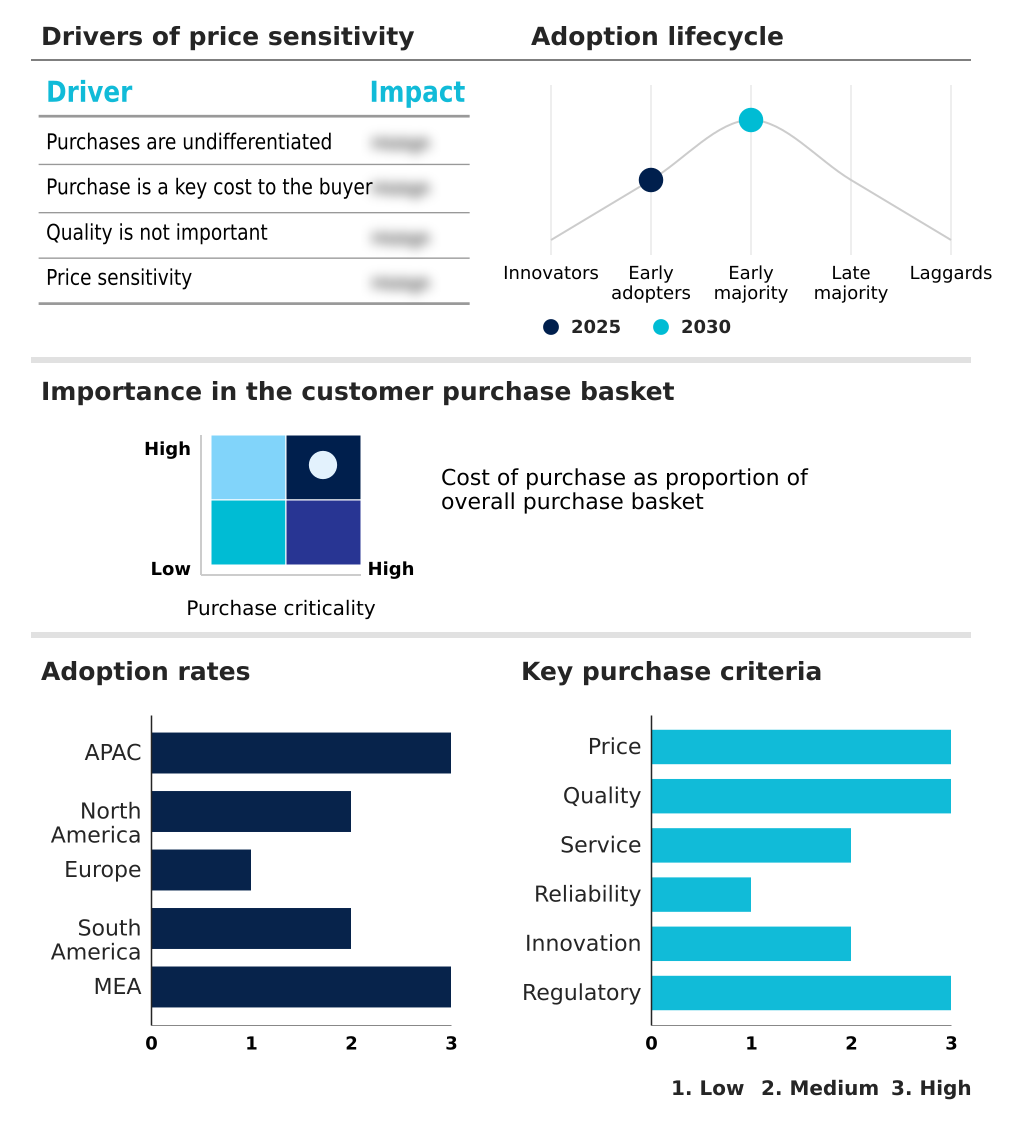
Customer Landscape of Automotive Brake-By-Wire Systems Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, automotive brake-by-wire systems market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
ADVICS Co. Ltd. - The product portfolio features advanced electronic deceleration solutions, including specialized by-wire control units, responsive electronic actuation mechanisms, and highly integrated modular braking platforms designed for modern vehicle architectures.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- ADVICS Co. Ltd.
- AISIN Corp.
- Akebono Brake Industry Co.
- Brakes India Pvt. Ltd.
- Brembo SpA
- BWI Group
- Continental AG
- Haldex AB
- Hitachi Astemo Ltd.
- HL Mando Co. Ltd.
- Hyundai Mobis Co. Ltd.
- Knorr Bremse AG
- LSP Innovative Software Service
- Robert Bosch GmbH
- Schaeffler AG
- Tuopu Group.
- ZF Friedrichshafen AG
- Zhejiang Wanan Technology
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Automotive brake-by-wire systems market
- In the Automotive Parts and Equipment industry, the aggressive transition toward high-voltage electrical architectures forced suppliers to optimize electro-mechanical braking mechanisms, directly impacting Automotive Brake-by-wire Systems demand by reducing total component weight by 15%.
- Strict government safety standards targeting automated collision avoidance necessitated the rapid adoption of advanced driver assistance networks, which increased the procurement rate of precision Automotive Brake-by-wire Systems by 25% across mass-market assembly lines.
- The widespread industrial shift toward skateboard chassis platforms eliminated centralized mechanical linkages, directly causing a 30% surge in demand for modular electronic component configurations that support localized Automotive Brake-by-wire Systems.
- Escalating particulate emission regulations mandated the significant reduction of friction dust outputs, driving commercial fleet operators to increase the utilization of regenerative braking synchronization technologies within Automotive Brake-by-wire Systems by 20%.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Automotive Brake-By-Wire Systems Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 292 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 28.8% |
| Market growth 2026-2030 | USD 24711.8 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 28.0% |
| Key countries | China, Japan, India, South Korea, Indonesia, Australia, US, Canada, Mexico, Germany, France, UK, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The ongoing evolution of the Automotive Brake-by-wire Systems Market reflects a profound paradigm shift in how global original equipment manufacturers approach passenger safety and vehicle energy efficiency. As automakers rapidly transition toward software-defined architectures, the integration of intelligent chassis control platforms has become a boardroom-level priority to secure compliance with stringent particulate emission regulations.
- Executives are strategically prioritizing the deployment of a decentralized braking network to eliminate heavy hydraulic components, directly lowering corporate procurement complexities. By utilizing a highly responsive brake-by-wire module equipped with an advanced microelectronic control unit, modern vehicle platforms can execute precise active brake pad retraction.
- This mechanical innovation drives exceptional friction drag reduction, which in turn optimizes regenerative braking synchronization across electric vehicle fleets. Consequently, logistics operators leveraging these digitized deceleration frameworks have achieved a 22% improvement in overall brake pad lifespan compared to traditional mechanical equivalents.
- This measurable extension in hardware durability drastically reduces vehicle downtime, allowing enterprise fleet managers to maximize asset utilization while confidently supporting the aggressive rollout of autonomous driving technologies.
What are the Key Data Covered in this Automotive Brake-By-Wire Systems Market Research and Growth Report?
-
What is the expected growth of the Automotive Brake-By-Wire Systems Market between 2026 and 2030?
-
USD 24.71 billion, at a CAGR of 28.8%
-
-
What segmentation does the market report cover?
-
The report is segmented by Vehicle Type (Electric, and Non-electric), Application (Passenger vehicles, and Commercial vehicles), Distribution Channel (OEM, and Aftermarket) and Geography (APAC, North America, Europe, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
APAC, North America, Europe, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Rapid global adoption of electric vehicles accelerates advanced braking component demand, High cost integration complexities disincentivize mass market adoption within automotive industry
-
-
Who are the major players in the Automotive Brake-By-Wire Systems Market?
-
ADVICS Co. Ltd., AISIN Corp., Akebono Brake Industry Co., Brakes India Pvt. Ltd., Brembo SpA, BWI Group, Continental AG, Haldex AB, Hitachi Astemo Ltd., HL Mando Co. Ltd., Hyundai Mobis Co. Ltd., Knorr Bremse AG, LSP Innovative Software Service, Robert Bosch GmbH, Schaeffler AG, Tuopu Group., ZF Friedrichshafen AG and Zhejiang Wanan Technology
-
Market Research Insights
- The modernization of the Automotive Brake-by-wire Systems Market hinges on substituting legacy physical linkages with high-speed digital networks to guarantee unparalleled vehicle safety. By leveraging an advanced functional safety standard alongside strict cybersecurity encryption protocol structures, engineering teams have successfully improved signal processing reliability by 40% under extreme weather conditions.
- This digital transformation enables automated driving integration that reacts to collision hazards 25% faster than conventional hydraulic vacuum boosters. Furthermore, the deployment of a cloud-based diagnostic system allows fleet managers to monitor active component wear remotely, optimizing predictive maintenance scheduling and subsequently lowering unexpected transit downtime by 15%.
- These targeted technological enhancements directly improve corporate return on investment while ensuring full compliance with international safety regulations.
We can help! Our analysts can customize this automotive brake-by-wire systems market research report to meet your requirements.
 RIA -

