Corn Starch Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Corn Starch Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 296 Pages SKU: IRTNTR74638

Market Overview at a Glance

$5.24 B
Market Opportunity
4.5%
CAGR 2025 - 2030
38.5%
North America Growth
$10.93 B
Sweeteners segment 2024

Corn Starch Market Size 2026-2030

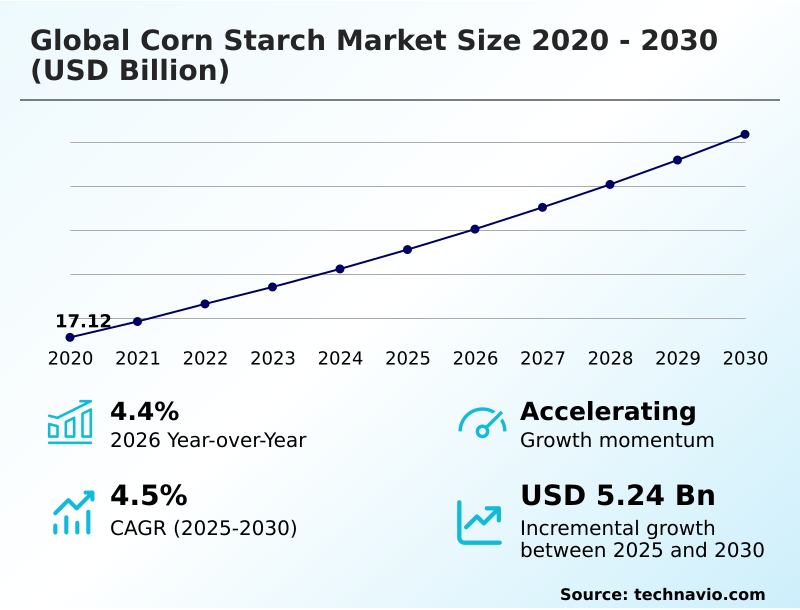
The corn starch market size is valued to increase by USD 5.24 billion, at a CAGR of 4.5% from 2025 to 2030. Expansion of clean label food products will drive the corn starch market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 38.5% growth during the forecast period.
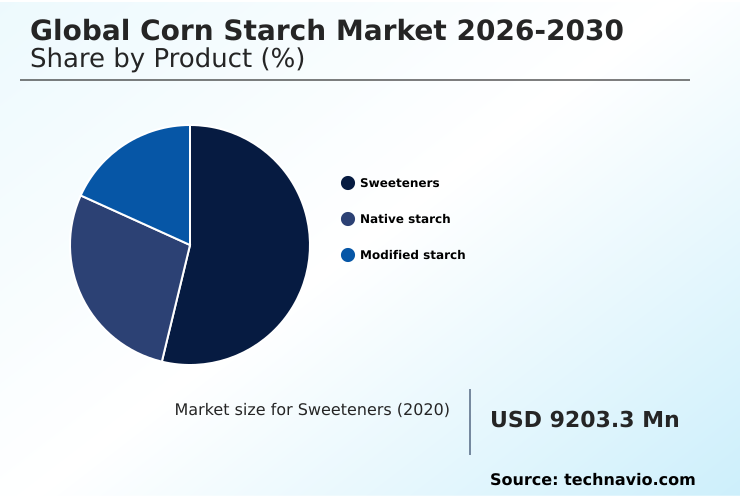
  • By Product - Sweeteners segment was valued at USD 10.93 billion in 2024
  • By End-user - Food processing segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 9.24 billion
  • Market Future Opportunities: USD 5.24 billion
  • CAGR from 2025 to 2030 : 4.5%

Market Summary

  • The Corn Starch Market demonstrates robust operational dynamism, functioning as a critical foundational element across diverse industrial and culinary supply chains. Rising consumer preference for transparent ingredient sourcing acts as a major driver, compelling food processors to replace artificial additives with natural thickeners. This shift improves clean-label compliance and enhances consumer trust in retail food segments.
  • Conversely, the market faces significant challenges from unpredictable agricultural yields; raw material volatility heavily compresses profit margins for major industrial wet-milling facilities. To mitigate these risks, procurement managers are optimizing supply chain resilience by diversifying geographical grain sourcing and implementing advanced predictive inventory models.
  • For instance, the deployment of automated supply chain optimization has enabled leading processors to reduce raw material waste by 14%, directly improving overall manufacturing efficiency. These continuous adaptations emphasize the market transition toward specialized, high-performance biomanufacturing capable of meeting stringent regulatory and functional requirements worldwide.

What will be the Size of the Corn Starch Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Corn Starch Market Segmented?

The corn starch industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Sweeteners
    • Native starch
    • Modified starch
  • End-user
    • Food processing
    • Paper
    • Chemical
    • Textile
    • Cosmetics
  • Source
    • Yellow corn
    • White corn
    • Waxy corn
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Product Insights

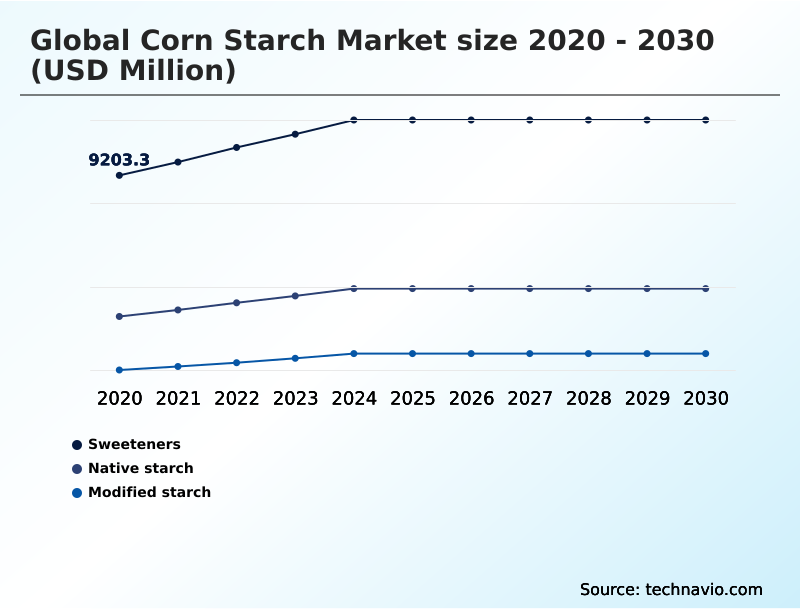
The sweeteners segment is estimated to witness significant growth during the forecast period.

The sweeteners segment within the Corn Starch landscape acts as a fundamental component for modern beverage formulations. Through advanced enzymatic modification, native starch undergoes precise conversion into functional carbohydrate variants capable of withstanding intense thermal sterilization.

These derivatives provide essential stabilization for plant-based nutrition products, yielding a 15% improvement in processing efficiency for high-volume extrusion processing lines. As industrial preferences shift toward sustainable manufacturing, processors utilize modified starch to meet complex formulation requirements.

This continuous evolution ensures manufacturers possess the vital gluten-free binder capabilities necessary for premium applications, directly enhancing operational margins and satisfying strict performance criteria.
Get Free Sample

The Sweeteners segment was valued at USD 10.93 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 38.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
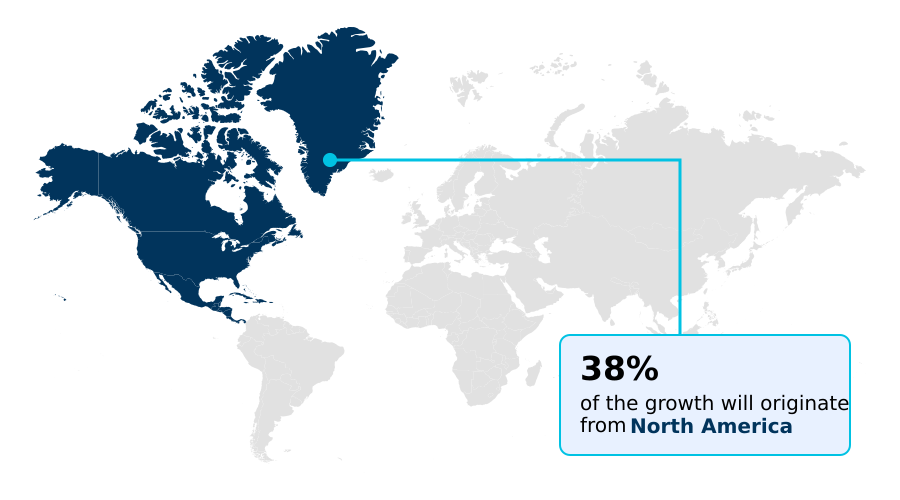
See How Corn Starch Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Corn Starch market reveals distinct operational disparities between North America and APAC.

North American processing facilities achieve a 15% higher extraction yield compared to legacy plants in emerging markets by utilizing advanced membrane filtration on raw starch slurry.

This operational superiority is driven by strict identity-preserved sourcing and non-gmo verification, ensuring unmatched quality for clean-label formulation. In contrast, the APAC region demonstrates a 25% faster adoption rate of automated bioprocessing systems to satisfy booming domestic demand.

North American manufacturers increasingly focus on pregelatinized starch and packaging bioplastics, reducing material waste by 18% through improved shelf-life extension technologies, illustrating how regional strategic priorities dictate distinct technological investments.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The strategic evolution of the Corn Starch sector highlights a concerted industry shift toward specialized ingredients capable of meeting rigorous technical specifications. As food processors aggressively pursue supply chain transparency, the demand for a reliable clean-label food thickening agent has surged, enabling manufacturers to reduce reliance on synthetic additives while achieving a 12% improvement in formulation stability during high-temperature processing.
  • Simultaneously, the healthcare sector increasingly mandates high-purity pharmaceutical grade starch to ensure precise drug delivery and optimal performance in solid dosage forms. Operational efficiency remains a critical focal point, with leading processing facilities investing heavily in enzymatic hydrolysis yield optimization to maximize raw material conversion and minimize energy consumption.
  • This focus on process refinement yields substantial cost advantages and supports the large-scale production of freeze-thaw stable modified starch, which is essential for maintaining textural integrity in frozen convenience foods over extended retail networks. Furthermore, the push for environmental sustainability has accelerated the development of biodegradable industrial packaging bioplastics, providing the logistics sector with viable alternatives to petroleum-based materials.
  • By integrating these advanced derivatives into everyday manufacturing, industrial leaders effectively enhance their operational resilience and compliance frameworks.
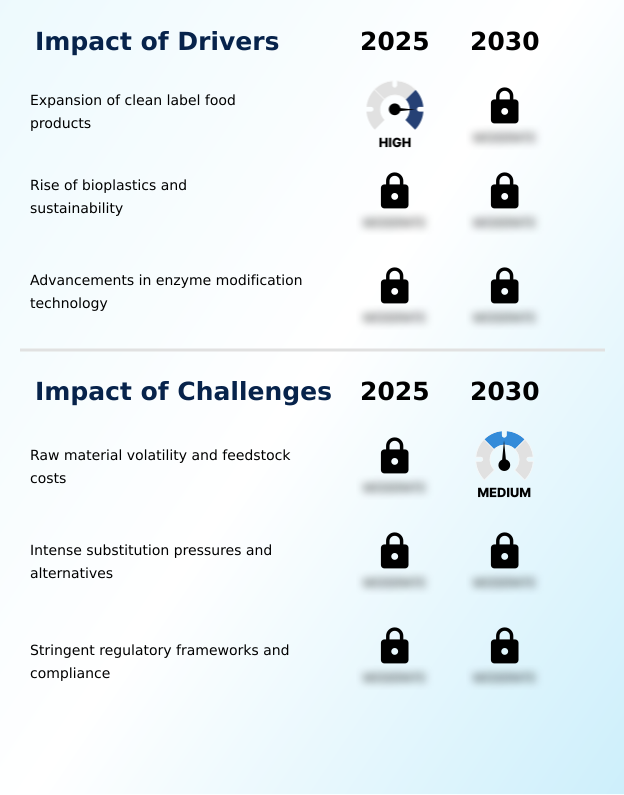
What are the key market drivers leading to the rise in the adoption of Corn Starch Industry?

  • The rapid expansion of clean-label food products acts as a primary catalyst accelerating demand for natural functional ingredients.

  • A profound shift in commercial behavior acts as a critical catalyst reshaping the Corn Starch supply chain. Manufacturers are systematically utilizing advanced biopolymers and optimized dextrinization processes to enhance end-product stability.
  • This strategic shift has prompted facilities to prioritize precise saccharification, resulting in a 30% reduction in formulation failures. Furthermore, the integration of automated viscosity control has improved the crystallization control of sweetener production by 12%.
  • Industrial buyers increasingly mandate specialized ingredients that prevent retrogradation and syneresis in frozen goods, while pharmaceutical applications require reliable disintegrant properties. This realignment ensures consistent delivery of high-performance surface sizing solutions for paper sectors, directly improving operational reliability.

What are the market trends shaping the Corn Starch Industry?

  • Continuous technological advancements in industrial processing represent a defining trend shaping the operational landscape. These innovations optimize production efficiencies and elevate the purity of starch derivatives across multiple applications.

  • The operational landscape is rapidly evolving through the aggressive adoption of sustainable biomanufacturing in the Corn Starch sector. Upgrading extraction protocols with precision enzymatic hydrolysis during wet-milling has reduced equipment downtime by 24%, while simultaneously improving raw material conversion rates by 15%. This transition occurs as downstream industrial clients demand superior thermal stability and acid resistance in their inputs.
  • By integrating automated controls, processing facilities successfully limit variations in amylose and amylopectin ratios, optimizing gelatinization for specialized applications. These continuous technological upgrades allow businesses to maintain rigorous rheological properties and exact viscosity profiles, ensuring consistent performance while decreasing their environmental footprint.

What challenges does the Corn Starch Industry face during its growth?

  • Severe raw material volatility and escalating feedstock costs remain significant structural challenges constraining industrial profit margins.

  • Severe unpredictability in agricultural feedstocks and escalating operational costs present formidable structural limitations within the Corn Starch processing environment. Fluctuating grain yields directly disrupt the initial steeping process, forcing facilities to operate below optimal capacity and increasing overall production expenses by up to 18%. Additionally, manufacturing complex derivatives like cross-linked starch and substituted starch requires energy-intensive liquefaction steps.
  • This operational friction results in a 15% drop in yield efficiency when attempting to produce premium hydrocolloids and biodegradable matrices through advanced green chemistry. To counteract these limitations, plant operators face strained budgets while stabilizing the continuous output of specialized fermentation technique products essential for wet-end additive applications.

Exclusive Technavio Analysis on Customer Landscape

The corn starch market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the corn starch market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
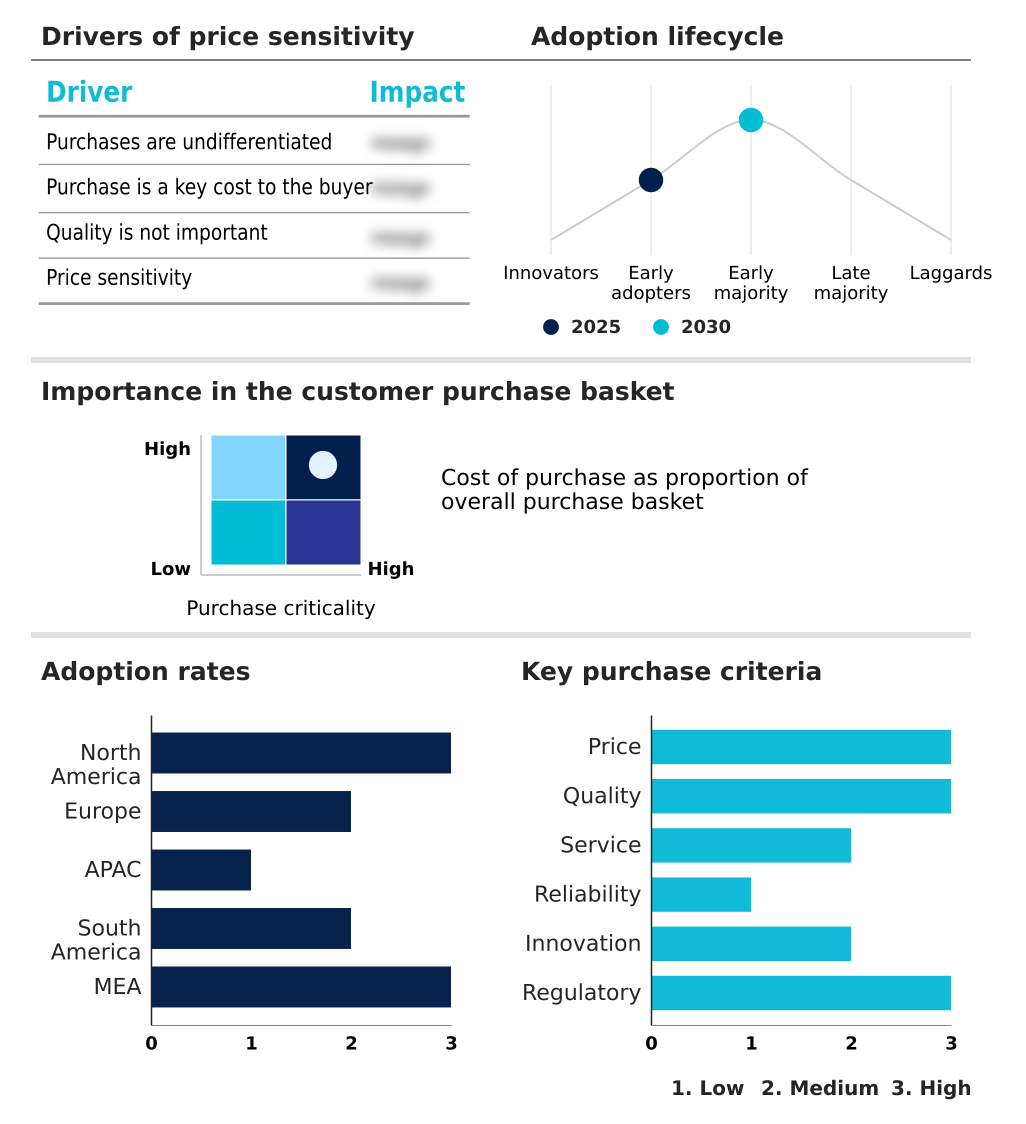
Customer Landscape of Corn Starch Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, corn starch market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Archer Daniels Midland Co. - Delivers functional carbohydrate solutions, focusing on high-purity native and modified starches to support clean-label formulation requirements in food processing and industrial applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Archer Daniels Midland Co.
  • Argo Starch
  • Cargill Inc.
  • Everest Starch India Pvt. Ltd.
  • Gulshan Polyols Ltd.
  • Ingredion Inc.
  • Primient
  • PT Daesang Ingredients Indonesia
  • PT Tereos FKS Indonesia
  • Regaal Resources Ltd.
  • Roquette Freres SA
  • Sanstar Ltd.
  • Sanwa Starch Co. Ltd.
  • Sayaji Industries Ltd
  • Sudzucker AG
  • Tate and Lyle Plc
  • The Sukhjit Starch and Chemicals
  • Tirupati Starch and Chemicals Ltd

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Corn starch market

  • In the Packaged Foods and Meats industry, the implementation of European Union food safety regulations has driven dairy sector processors to replace synthetic additives, directly impacting Corn Starch demand by accelerating the adoption of natural mouthfeel enhancers by 22%.
  • The regulatory shift toward the European Single-Use Plastics Directive in regional logistics networks has accelerated the adoption of sustainable materials, increasing the utilization of Corn Starch for corrugated board strengthening by 18%.
  • Technological upgrades in high-pressure processing within North American ready-to-eat meal manufacturing facilities have required robust ingredients, boosting the consumption of Corn Starch capable of withstanding a high shear environment by 15%.
  • The expansion of vegan formulations in the APAC commercial beverage sector has prompted widespread recipe reformulation, expanding the reliance on Corn Starch to ensure superior moisture retention and improve production yield by 12%.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Corn Starch Market insights. See full methodology.

Market Scope
Page number 296
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.5%
Market growth 2026-2030 USD 5238.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.4%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Corn Starch industry exhibits continuous adaptation, fundamentally driven by an intersection of material science innovation and stringent supply chain compliance. Manufacturers are actively restructuring their product portfolios to emphasize highly specialized derivatives and advanced polymers that fulfill complex industrial requirements.
  • This transition heavily influences boardroom-level budgeting decisions, as corporate leaders allocate substantial capital toward upgrading legacy wet-milling infrastructure with precision processing capabilities. Consequently, modern facilities have achieved a 20% reduction in water consumption during the initial material separation, dramatically improving operational sustainability.
  • The integration of stabilized variants provides unmatched resistance to liquid separation, solving critical textural failures in demanding manufacturing environments. Furthermore, enhanced filtration techniques guarantee superior purity for core applications, solidifying trust among institutional buyers.
  • These targeted operational upgrades ensure that the production of essential components remains robust against fluctuating agricultural inputs, enabling enterprises to maintain strict quality standards while navigating an increasingly regulated global manufacturing landscape.

What are the Key Data Covered in this Corn Starch Market Research and Growth Report?

  • What is the expected growth of the Corn Starch Market between 2026 and 2030?

    • USD 5.24 billion, at a CAGR of 4.5%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Sweeteners, Native starch, and Modified starch), End-user (Food processing, Paper, Chemical, Textile, and Cosmetics), Source (Yellow corn, White corn, and Waxy corn) and Geography (North America, Europe, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Expansion of clean label food products, Raw material volatility and feedstock costs

  • Who are the major players in the Corn Starch Market?

    • Archer Daniels Midland Co., Argo Starch, Cargill Inc., Everest Starch India Pvt. Ltd., Gulshan Polyols Ltd., Ingredion Inc., Primient, PT Daesang Ingredients Indonesia, PT Tereos FKS Indonesia, Regaal Resources Ltd., Roquette Freres SA, Sanstar Ltd., Sanwa Starch Co. Ltd., Sayaji Industries Ltd, Sudzucker AG, Tate and Lyle Plc, The Sukhjit Starch and Chemicals and Tirupati Starch and Chemicals Ltd

Market Research Insights

  • The Corn Starch Market is undergoing rapid technological transformation, emphasizing superior material stability in industrial applications. Processors utilizing advanced enzymatic conversion have observed a 22% improvement in yield efficiency during continuous high-volume operations. Additionally, the integration of automated quality control systems has reduced batch-to-batch variations by 18%, significantly lowering operational downtime.
  • By prioritizing traceable agricultural sourcing and stringent quality verification, manufacturers effectively address rigorous regulatory compliance while securing premium supplier contracts. This strategic alignment with sustainable processing principles not only ensures consistent output in downstream manufacturing but also strengthens supply chain resilience against fluctuating raw material availability.

We can help! Our analysts can customize this corn starch market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Source
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Corn Starch Market 2020 - 2024

Historic Market Size - Data Table on Global Corn Starch Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Source segment analysis 2020 - 2024

Historic Market Size - Source Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Corn Starch Market

6.2 Impact of geopolitical conflicts on Global Corn Starch Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Sweeteners - Market size and forecast 2025-2030

Chart on Sweeteners - Market size and forecast 2025-2030 ($ million)
Data Table on Sweeteners - Market size and forecast 2025-2030 ($ million)
Chart on Sweeteners - Year-over-year growth 2025-2030 (%)
Data Table on Sweeteners - Year-over-year growth 2025-2030 (%)

8.4 Native starch - Market size and forecast 2025-2030

Chart on Native starch - Market size and forecast 2025-2030 ($ million)
Data Table on Native starch - Market size and forecast 2025-2030 ($ million)
Chart on Native starch - Year-over-year growth 2025-2030 (%)
Data Table on Native starch - Year-over-year growth 2025-2030 (%)

8.5 Modified starch - Market size and forecast 2025-2030

Chart on Modified starch - Market size and forecast 2025-2030 ($ million)
Data Table on Modified starch - Market size and forecast 2025-2030 ($ million)
Chart on Modified starch - Year-over-year growth 2025-2030 (%)
Data Table on Modified starch - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Food processing - Market size and forecast 2025-2030

Chart on Food processing - Market size and forecast 2025-2030 ($ million)
Data Table on Food processing - Market size and forecast 2025-2030 ($ million)
Chart on Food processing - Year-over-year growth 2025-2030 (%)
Data Table on Food processing - Year-over-year growth 2025-2030 (%)

9.4 Paper - Market size and forecast 2025-2030

Chart on Paper - Market size and forecast 2025-2030 ($ million)
Data Table on Paper - Market size and forecast 2025-2030 ($ million)
Chart on Paper - Year-over-year growth 2025-2030 (%)
Data Table on Paper - Year-over-year growth 2025-2030 (%)

9.5 Chemical - Market size and forecast 2025-2030

Chart on Chemical - Market size and forecast 2025-2030 ($ million)
Data Table on Chemical - Market size and forecast 2025-2030 ($ million)
Chart on Chemical - Year-over-year growth 2025-2030 (%)
Data Table on Chemical - Year-over-year growth 2025-2030 (%)

9.6 Textile - Market size and forecast 2025-2030

Chart on Textile - Market size and forecast 2025-2030 ($ million)
Data Table on Textile - Market size and forecast 2025-2030 ($ million)
Chart on Textile - Year-over-year growth 2025-2030 (%)
Data Table on Textile - Year-over-year growth 2025-2030 (%)

9.7 Cosmetics - Market size and forecast 2025-2030

Chart on Cosmetics - Market size and forecast 2025-2030 ($ million)
Data Table on Cosmetics - Market size and forecast 2025-2030 ($ million)
Chart on Cosmetics - Year-over-year growth 2025-2030 (%)
Data Table on Cosmetics - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Source

10.1 Market segments

Chart on Source - Market share 2025-2030 (%)
Data Table on Source - Market share 2025-2030 (%)

10.2 Comparison by Source

Chart on Comparison by Source
Data Table on Comparison by Source

10.3 Yellow corn - Market size and forecast 2025-2030

Chart on Yellow corn - Market size and forecast 2025-2030 ($ million)
Data Table on Yellow corn - Market size and forecast 2025-2030 ($ million)
Chart on Yellow corn - Year-over-year growth 2025-2030 (%)
Data Table on Yellow corn - Year-over-year growth 2025-2030 (%)

10.4 White corn - Market size and forecast 2025-2030

Chart on White corn - Market size and forecast 2025-2030 ($ million)
Data Table on White corn - Market size and forecast 2025-2030 ($ million)
Chart on White corn - Year-over-year growth 2025-2030 (%)
Data Table on White corn - Year-over-year growth 2025-2030 (%)

10.5 Waxy corn - Market size and forecast 2025-2030

Chart on Waxy corn - Market size and forecast 2025-2030 ($ million)
Data Table on Waxy corn - Market size and forecast 2025-2030 ($ million)
Chart on Waxy corn - Year-over-year growth 2025-2030 (%)
Data Table on Waxy corn - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Source

Market opportunity by Source ($ million)
Data Table on Market opportunity by Source ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Expansion of clean label food products
Rise of bioplastics and sustainability
Advancements in enzyme modification technology

13.2 Market challenges

Raw material volatility and feedstock costs
Intense substitution pressures and alternatives
Stringent regulatory frameworks and compliance

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Technological advancements in processing
Paper and packaging industry revival
Bioethanol integration and diversification

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Archer Daniels Midland Co.

Archer Daniels Midland Co. - Overview
Archer Daniels Midland Co. - Business segments
Archer Daniels Midland Co. - Key news
Archer Daniels Midland Co. - Key offerings
Archer Daniels Midland Co. - Segment focus
SWOT

15.5 Cargill Inc.

Cargill Inc. - Overview
Cargill Inc. - Product / Service
Cargill Inc. - Key news
Cargill Inc. - Key offerings
SWOT

15.6 Everest Starch India Pvt. Ltd.

Everest Starch India Pvt. Ltd. - Overview
Everest Starch India Pvt. Ltd. - Product / Service
Everest Starch India Pvt. Ltd. - Key offerings
SWOT

15.7 Gulshan Polyols Ltd.

Gulshan Polyols Ltd. - Overview
Gulshan Polyols Ltd. - Business segments
Gulshan Polyols Ltd. - Key offerings
Gulshan Polyols Ltd. - Segment focus
SWOT

15.8 Ingredion Inc.

Ingredion Inc. - Overview
Ingredion Inc. - Business segments
Ingredion Inc. - Key offerings
Ingredion Inc. - Segment focus
SWOT

15.9 PT Daesang Ingredients Indonesia

PT Daesang Ingredients Indonesia - Overview
PT Daesang Ingredients Indonesia - Product / Service
PT Daesang Ingredients Indonesia - Key offerings
SWOT

15.10 Regaal Resources Ltd.

Regaal Resources Ltd. - Overview
Regaal Resources Ltd. - Product / Service
Regaal Resources Ltd. - Key offerings
SWOT

15.11 Roquette Freres SA

Roquette Freres SA - Overview
Roquette Freres SA - Product / Service
Roquette Freres SA - Key offerings
SWOT

15.12 Sanstar Ltd.

Sanstar Ltd. - Overview
Sanstar Ltd. - Product / Service
Sanstar Ltd. - Key offerings
SWOT

15.13 Sanwa Starch Co. Ltd.

Sanwa Starch Co. Ltd. - Overview
Sanwa Starch Co. Ltd. - Product / Service
Sanwa Starch Co. Ltd. - Key offerings
SWOT

15.14 Sayaji Industries Ltd

Sayaji Industries Ltd - Overview
Sayaji Industries Ltd - Business segments
Sayaji Industries Ltd - Key offerings
Sayaji Industries Ltd - Segment focus
SWOT

15.15 Sudzucker AG

Sudzucker AG - Overview
Sudzucker AG - Business segments
Sudzucker AG - Key offerings
Sudzucker AG - Segment focus
SWOT

15.16 Tate and Lyle Plc

Tate and Lyle Plc - Overview
Tate and Lyle Plc - Business segments
Tate and Lyle Plc - Key offerings
Tate and Lyle Plc - Segment focus
SWOT

15.17 The Sukhjit Starch and Chemicals

The Sukhjit Starch and Chemicals - Overview
The Sukhjit Starch and Chemicals - Business segments
The Sukhjit Starch and Chemicals - Key offerings
The Sukhjit Starch and Chemicals - Segment focus
SWOT

15.18 Tirupati Starch and Chemicals Ltd

Tirupati Starch and Chemicals Ltd - Overview
Tirupati Starch and Chemicals Ltd - Product / Service
Tirupati Starch and Chemicals Ltd - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Corn Starch market growth will increase by USD 5238.6 million during 2026-2030.

The Corn Starch market is expected to grow at a CAGR of 4.5% during 2026-2030.

Corn Starch market is segmented by Product (Sweeteners, Native starch, Modified starch) End-user (Food processing, Paper, Chemical, Textile, Cosmetics) Source (Yellow corn, White corn, Waxy corn)

Archer Daniels Midland Co., Argo Starch, Cargill Inc., Everest Starch India Pvt. Ltd., Gulshan Polyols Ltd., Ingredion Inc., Primient, PT Daesang Ingredients Indonesia, PT Tereos FKS Indonesia, Regaal Resources Ltd., Roquette Freres SA, Sanstar Ltd., Sanwa Starch Co. Ltd., Sayaji Industries Ltd, Sudzucker AG, Tate and Lyle Plc, The Sukhjit Starch and Chemicals, Tirupati Starch and Chemicals Ltd are a few of the key vendors in the Corn Starch market.

North America will register the highest growth rate of 38.5% among the other regions. Therefore, the Corn Starch market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Expansion of clean label food products is the driving factor this market.

The Corn Starch market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
