


Deepwater And Ultra-Deepwater Drilling Market Size 2026-2030
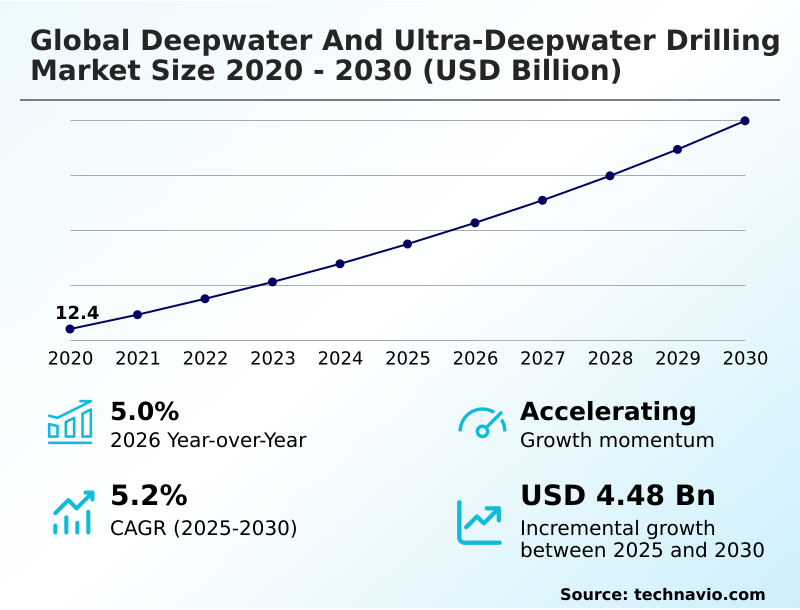
The deepwater and ultra-deepwater drilling market size is valued to increase by USD 4.48 billion, at a CAGR of 5.2% from 2025 to 2030. Imperative for national energy supply security will drive the deepwater and ultra-deepwater drilling market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 31.2% growth during the forecast period.
- By Application - Deepwater drilling segment was valued at USD 9.67 billion in 2024
- By Type - Drill ships segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 7.57 billion
- Market Future Opportunities: USD 4.48 billion
- CAGR from 2025 to 2030 : 5.2%
Market Summary
- The Deepwater And Ultra-deepwater Drilling sector demonstrates robust structural expansion as energy operators target unexploited subsea basins to secure long-term production plateaus. In a recent supply chain optimization scenario, the integration of real-time sensor networks and remote operation centers allowed operators to monitor multiple offshore rigs simultaneously, reducing required on-board crew sizes and cutting operational expenditures by 20%.
- The imperative for national energy supply security acts as a primary driver, compelling sovereign governments to expand offshore acreage auctions and reduce reliance on volatile foreign crude imports. Conversely, the market faces severe headwinds from capital allocation constraints and elevated day rates, which force independent operators to defer major offshore drilling projects during periods of commodity price volatility.
- To navigate these dynamics, drilling contractors are heavily investing in dual-activity derrick technology and active-heave compensation to maximize drilling uptime. As the industry evolves, the continuous refinement of subsea automation control and acoustic shear rams ensures that complex well-completion services meet stringent safety and environmental mandates.
What will be the Size of the Deepwater And Ultra-Deepwater Drilling Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Deepwater And Ultra-Deepwater Drilling Market Segmented?
The deepwater and ultra-deepwater drilling industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Application
- Deepwater drilling
- Ultra-deepwater drilling
- Type
- Drill ships
- Semisubmersible
- Technology
- Blowout preventer
- Drilling riser
- Seafloor pumping
- Geography
- North America
- US
- Canada
- Mexico
- APAC
- China
- Australia
- India
- Indonesia
- Japan
- South Korea
- Europe
- UK
- France
- Germany
- Italy
- Spain
- The Netherlands
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Turkey
- South America
- Brazil
- Argentina
- Chile
- North America
By Application Insights
The deepwater drilling segment is estimated to witness significant growth during the forecast period.
The deepwater drilling segment within the Deepwater And Ultra-deepwater Drilling sector represents a critical operational domain for complex well-completion services across continental shelves.
Operators increasingly rely on automated drilling control and directional drilling systems to safely navigate extreme hydrostatic pressure and complex subsea engineering capabilities. By integrating closed-loop waste management, companies have improved rate of penetration optimization by 15%, significantly reducing non-productive time.
This segment's continuous evolution is driven by the deployment of subsea tie-back frameworks, which connect newly discovered reservoirs in deep subsea geological strata to existing infrastructure, lowering capital expenditure.
As deepwater field developments expand, the reliance on hydraulic fracturing equipment ensures sustained operational efficiency and robust extraction capabilities.
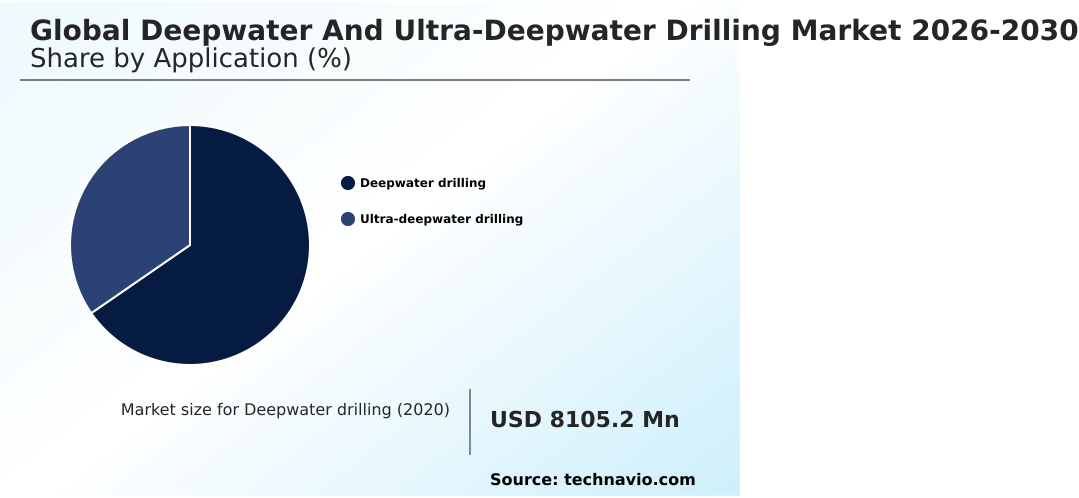
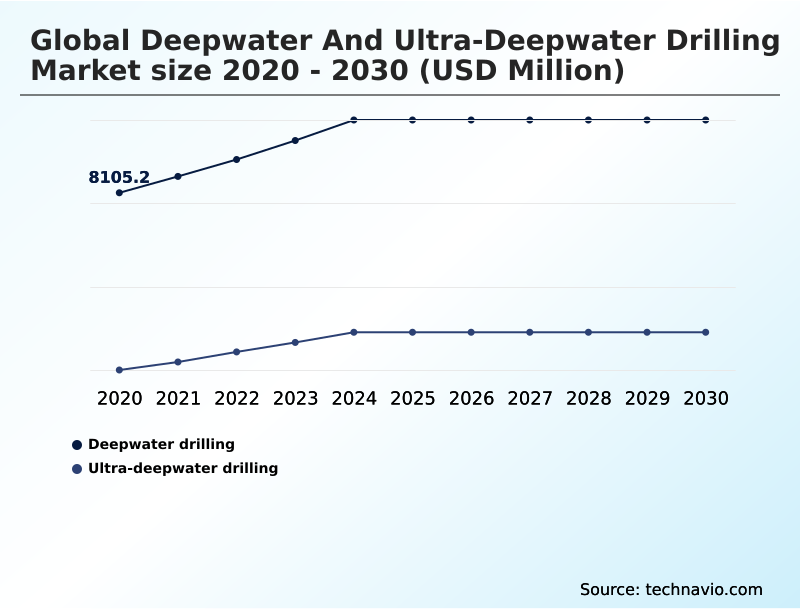
The Deepwater drilling segment was valued at USD 9.67 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
North America is estimated to contribute 31.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
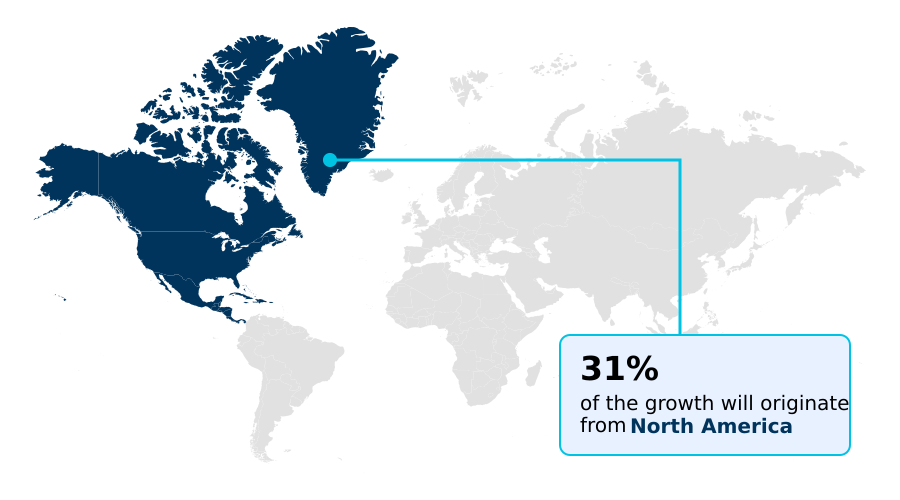
See How Deepwater And Ultra-Deepwater Drilling Market Demand is Rising in North America Get Free Sample
The Deepwater And Ultra-deepwater Drilling landscape exhibits distinct regional variations driven by regulatory frameworks and offshore extraction technologies.
North America leads the sector, leveraging advanced subsea completion architectures and riserless mud recovery to achieve a 30% higher operational efficiency compared to South America.
In the United States Gulf of Mexico, the rapid deployment of multiplex control pods and high-pressure wellheads has reduced equipment failure incidents by 24%, optimizing ultra-deepwater exploration.
Conversely, South America is accelerating its deepwater growth through extensive offshore acreage auctions to access high-volume offshore hydrocarbon reserves, though it faces a 15% higher supply chain latency.
As both regions expand, the integration of downhole vibration analysis and predictive maintenance analytics continues to bridge the efficiency gap across diverse marine environments.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The continuous evolution of the Deepwater And Ultra-deepwater Drilling sector is fundamentally reshaping how energy operators approach complex offshore hydrocarbon extraction. A critical component of this transformation is the integration of autonomous digital drilling control systems, which allows operators to dynamically adjust weight-on-bit and rotary speeds, resulting in a 20% higher operational consistency compared to manual legacy operations.
- As exploration moves into more extreme hydrostatic pressure zones, the high-pressure subsea blowout preventer integration has become paramount for maintaining wellbore integrity and ensuring rigorous compliance with environmental safety mandates. Furthermore, ultra-deepwater drillship dynamic positioning enables these massive vessels to maintain precise station-keeping against severe ocean currents, significantly optimizing supply chain logistics and reducing fuel consumption during multi-well exploratory campaigns.
- The strategic subsea tie-back framework deployment is also accelerating, allowing newly discovered reservoirs to be connected directly to existing floating production platforms, thereby reducing initial capital expenditure requirements by nearly a third. To support these complex architectures, operators are increasingly relying on real-time seismic imaging software to map deep subsea geological strata accurately, minimizing the risk of dry holes.
- Together, these technological advancements ensure that deepwater and ultra-deepwater drilling operations remain resilient, cost-effective, and highly efficient in fulfilling long-term global energy demands.
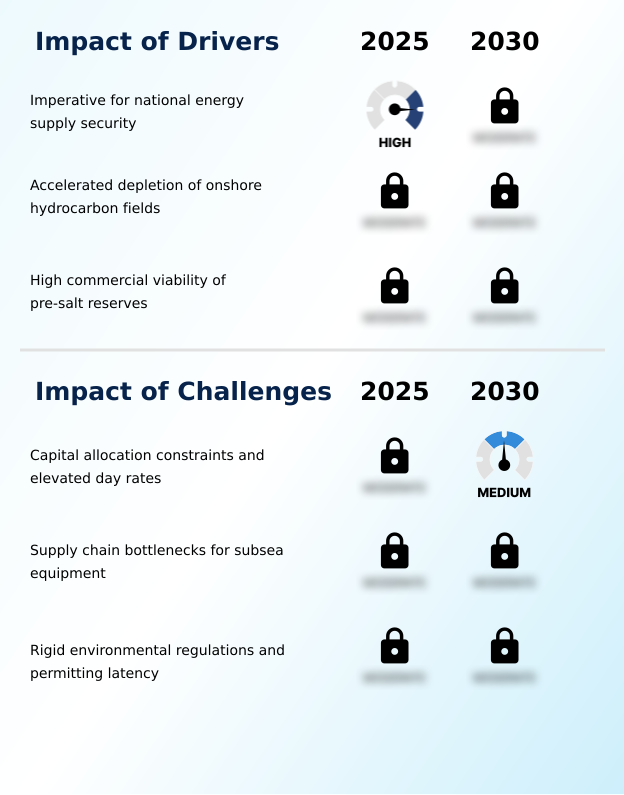
What are the key market drivers leading to the rise in the adoption of Deepwater And Ultra-Deepwater Drilling Industry?
- The imperative for national energy supply security serves as a primary driver propelling market expansion.
- The escalating imperative for national energy security is fundamentally accelerating Deepwater And Ultra-deepwater Drilling activity across unexploited maritime basins. Sovereign governments are aggressively expanding offshore hydrocarbon exploration to tap into new reserves and secure long-life production plateaus.
- This strategic push compels operators to deploy dual-activity derrick technology and advanced dynamic positioning systems to navigate harsh offshore environments safely.
- By leveraging subsea reservoir mapping, companies have lowered operational costs by 15% and reduced on-board personnel requirements by 20% during exploratory drilling campaigns.
- The adoption of high-performance tubulars, hybrid power systems, and drilling fluid systems ensures precise well placement, driving higher extraction yields. Ultimately, this pursuit guarantees sustained demand and robust operational advancements in the offshore energy sector.
What are the market trends shaping the Deepwater And Ultra-Deepwater Drilling Industry?
- The deployment of autonomous digital drilling technologies represents a pivotal trend shaping the market landscape. This advancement significantly enhances operational precision and efficiency in complex offshore environments.
- The Deepwater And Ultra-deepwater Drilling sector is experiencing a rapid shift toward autonomous digitalization to optimize offshore automated operations. Operators are increasingly adopting digital twin integration and subsea automation control to monitor subsea blowout preventers and marine riser systems. This transition is driven by the need to mitigate human error in remote operation centers.
- Consequently, businesses utilizing these advanced autonomous drilling control systems have reduced downtime by 30% and improved forecasting accuracy by 18%. The deployment of well-bore instability prevention algorithms and real-time seismic imaging allows engineering teams to anticipate pressure anomalies instantly, enhancing operational safety.
- As these technological shifts become the industry standard, they ensure that extraction processes remain highly efficient and resilient against the mechanical challenges of the ocean floor.
What challenges does the Deepwater And Ultra-Deepwater Drilling Industry face during its growth?
- Capital allocation constraints and elevated day rates constitute significant challenges impeding industry growth.
- Severe capital allocation constraints and escalating day rates present substantial structural challenges to the Deepwater And Ultra-deepwater Drilling sector. Executing ultra-deepwater offshore drilling projects requires massive initial investments, forcing operators to utilize subsea construction vessel charters cautiously.
- Supply chain bottlenecks for specialized equipment, such as high-pressure high-temperature wellhead components and high-specification semi-submersibles, have increased supply chain latency by 22% compared to shallow-water operations. Additionally, rigid environmental permitting processes create significant operational friction, reducing overall fleet utilization efficiency by 14%.
- To mitigate these logistical hurdles, drilling contractors must continuously optimize their active-heave compensation, acoustic shear rams, and edge-computing automation to prevent costly equipment failures. The integration of real-time sensor networks is critical for maintaining project viability despite these constraints.
Exclusive Technavio Analysis on Customer Landscape
The deepwater and ultra-deepwater drilling market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the deepwater and ultra-deepwater drilling market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
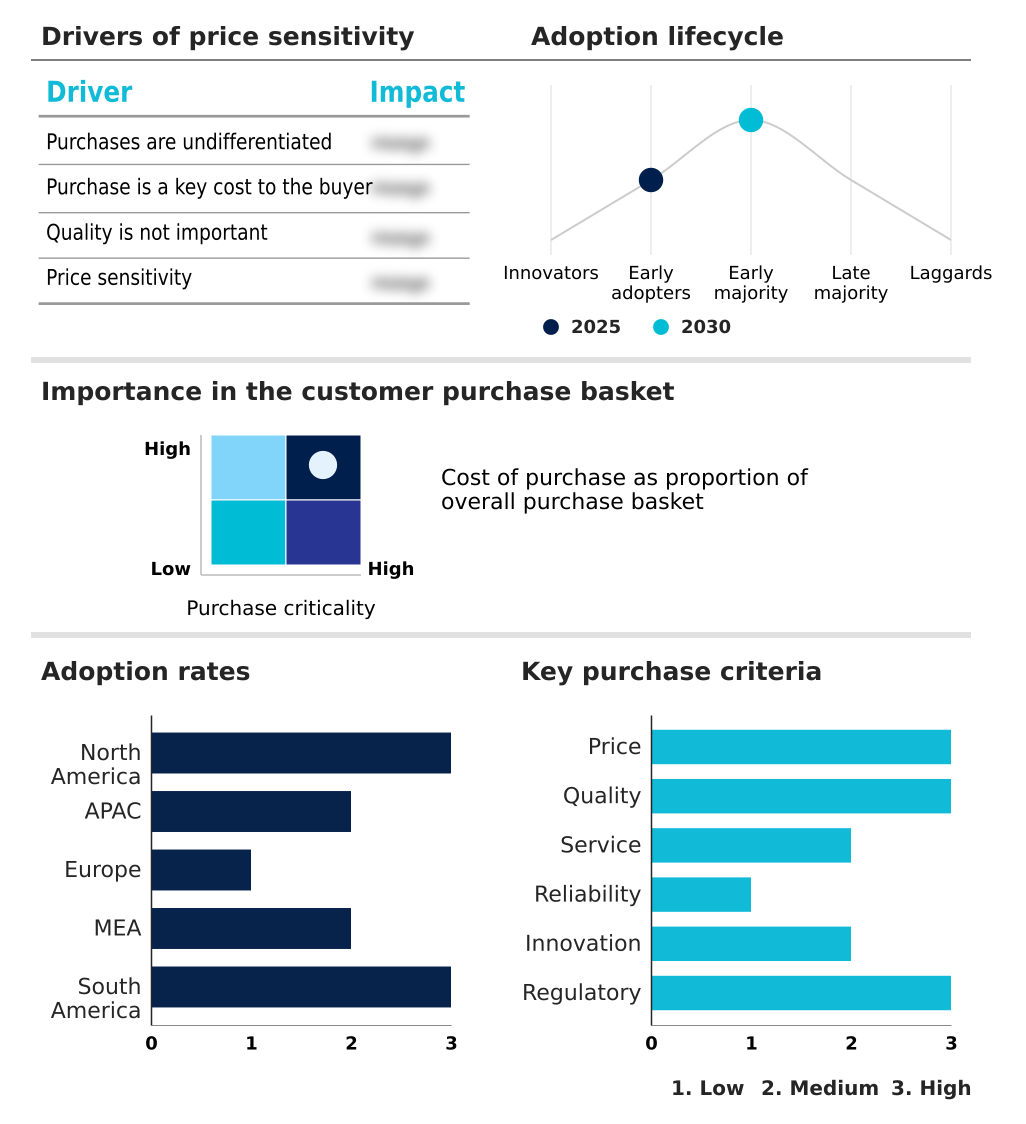
Customer Landscape of Deepwater And Ultra-Deepwater Drilling Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, deepwater and ultra-deepwater drilling market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Atlantica Tender Drilling - Provides advanced deepwater and ultra-deepwater drilling solutions, specializing in ultra-deepwater drillship operations and comprehensive offshore drilling services to optimize complex subsea hydrocarbon extraction.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Atlantica Tender Drilling
- Caspian Drilling Co. Ltd.
- China Oilfield Services Ltd.
- Constellation Oil Services
- Dolphin Drilling AS
- Eldorado Drilling AS
- Japan Drilling Co. Ltd.
- Nabors Industries Ltd.
- Noble Corp. Plc
- Northern Ocean Ltd.
- Odfjell Drilling Ltd.
- Saipem S.p.A.
- Seadrill Ltd.
- Stena Drilling Ltd.
- Transocean Ltd.
- Valaris Ltd.
- Vantage Drilling Int Ltd.
- Ventura Offshore
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Deepwater and ultra-deepwater drilling market
- In the Oil and Gas Equipment and Services industry, the rapid adoption of edge-computing automation and digital twin integration has optimized predictive maintenance analytics, directly impacting Deepwater And Ultra-deepwater Drilling demand by reducing equipment downtime by 22%.
- Stringent maritime emission regulations mandating closed-loop waste management and hybrid power systems have accelerated the modernization of offshore extraction technologies, driving the Deepwater And Ultra-deepwater Drilling market to upgrade legacy fleets to meet new compliance thresholds.
- The shift toward high-volume offshore hydrocarbon reserves in remote basins has necessitated the deployment of high-pressure high-temperature wellhead components and high-performance tubulars, boosting Deepwater And Ultra-deepwater Drilling efficiency by 18% in harsh offshore environments.
- Advancements in real-time seismic imaging and subsea reservoir mapping have enhanced exploratory drilling campaigns, increasing the success rate of ultra-deepwater exploration by 14% and stimulating demand for advanced Deepwater And Ultra-deepwater Drilling services.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Deepwater And Ultra-Deepwater Drilling Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 278 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 5.2% |
| Market growth 2026-2030 | USD 4480.9 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 5.0% |
| Key countries | US, Canada, Mexico, China, Australia, India, Indonesia, Japan, South Korea, UK, France, Germany, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Deepwater And Ultra-deepwater Drilling sector is undergoing a profound technological transformation as operators seek to maximize hydrocarbon recovery in harsh offshore environments. A critical boardroom-level focus is the deployment of closed-loop waste management and hybrid power systems to align operational strategies with stringent environmental compliance mandates.
- By implementing edge-computing automation and subsea automation control, drilling contractors have successfully reduced non-productive time, achieving a 25% improvement in overall drilling efficiency compared to conventional methods. The integration of dual-activity derrick technology and active-heave compensation allows for the simultaneous handling of drill pipes and casing strings, significantly accelerating well-completion timelines.
- Furthermore, the reliance on marine riser systems and acoustic shear rams ensures that high-pressure operations maintain absolute wellbore integrity under extreme conditions. As the industry continuously evolves, the adoption of directional drilling systems and drilling fluid systems optimizes the rate of penetration, ensuring that complex ultra-deepwater projects remain both operationally viable and economically resilient amidst fluctuating energy demands.
What are the Key Data Covered in this Deepwater And Ultra-Deepwater Drilling Market Research and Growth Report?
-
What is the expected growth of the Deepwater And Ultra-Deepwater Drilling Market between 2026 and 2030?
-
USD 4.48 billion, at a CAGR of 5.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Application (Deepwater drilling, and Ultra-deepwater drilling), Type (Drill ships, and Semisubmersible), Technology (Blowout preventer, Drilling riser, and Seafloor pumping) and Geography (North America, APAC, Europe, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
North America, APAC, Europe, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Imperative for national energy supply security, Capital allocation constraints and elevated day rates
-
-
Who are the major players in the Deepwater And Ultra-Deepwater Drilling Market?
-
Atlantica Tender Drilling, Caspian Drilling Co. Ltd., China Oilfield Services Ltd., Constellation Oil Services, Dolphin Drilling AS, Eldorado Drilling AS, Japan Drilling Co. Ltd., Nabors Industries Ltd., Noble Corp. Plc, Northern Ocean Ltd., Odfjell Drilling Ltd., Saipem S.p.A., Seadrill Ltd., Stena Drilling Ltd., Transocean Ltd., Valaris Ltd., Vantage Drilling Int Ltd. and Ventura Offshore
-
Market Research Insights
- The Deepwater And Ultra-deepwater Drilling sector is rapidly evolving as operators prioritize ultra-deepwater offshore drilling projects to access high-volume offshore hydrocarbon reserves. By leveraging autonomous drilling control systems, companies have increased drilling efficiency by 25% and reduced mechanical failure rates by 18%.
- The integration of predictive maintenance analytics within remote operation centers has further optimized asset utilization, cutting maintenance-related downtime by 22%. This technological shift enables more precise exploratory drilling campaigns in harsh offshore environments.
- As energy demands escalate, the strategic deployment of high-specification semi-submersibles ensures that deepwater field developments remain economically viable, driving sustained operational improvements and robust compliance alignment across the offshore energy landscape.
We can help! Our analysts can customize this deepwater and ultra-deepwater drilling market research report to meet your requirements.
 RIA -

