


In Mold Labelling Market Size 2026-2030
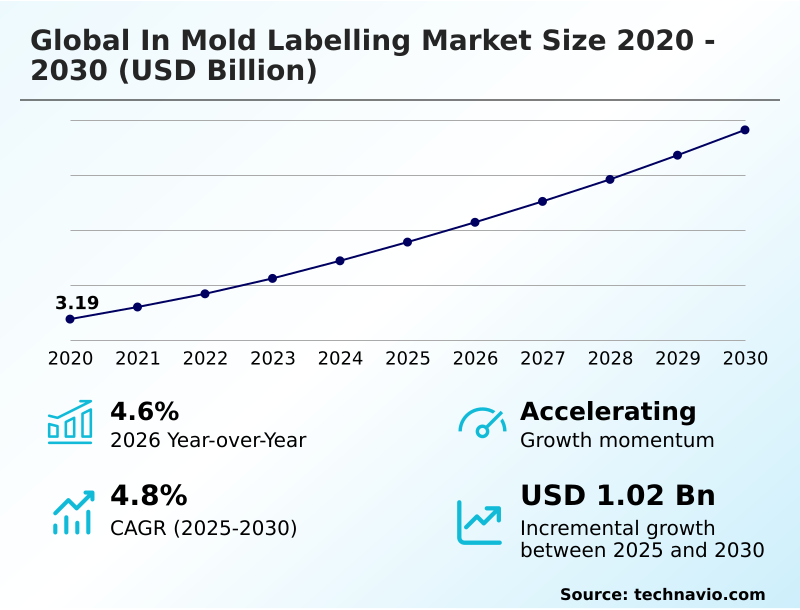
The in mold labelling market size is valued to increase by USD 1.02 billion, at a CAGR of 4.8% from 2025 to 2030. Sustainability regulations driving mono material shift will drive the in mold labelling market.
Major Market Trends & Insights
- Europe dominated the market and accounted for a 48.2% growth during the forecast period.
- By Technology - Injection molding segment was valued at USD 2.36 billion in 2024
- By End-user - Food and beverage segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 1.72 billion
- Market Future Opportunities: USD 1.02 billion
- CAGR from 2025 to 2030 : 4.8%
Market Summary
- The In Mold Labelling Market demonstrates robust structural expansion driven by the necessity for highly durable and visually seamless consumer packaging. Manufacturers increasingly integrate pre-printed thermoplastic films directly into plastic containers during the molding phase to eliminate secondary adhesive application steps.
- In a practical supply chain scenario, a major dairy producer transitioning to integrated labeling achieved a 15% reduction in production cycle times by removing post-mold decoration delays. This operational efficiency is primarily propelled by strict environmental sustainability policies that champion mono material structures, ensuring both label and container utilize compatible polypropylene substrates for seamless recyclability.
- Conversely, the market faces notable constraints due to the high capital expenditures required to install precision robotic handling systems and custom mold cavities. Establishing these automated production lines demands significant upfront investment, creating a steep barrier to entry for smaller localized converters.
- Despite these financial hurdles, the continuous demand for superior moisture resistance and tactile finishes in consumer goods ensures sustained investment in advanced molding technologies.
What will be the Size of the In Mold Labelling Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the In Mold Labelling Market Segmented?
The in mold labelling industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Technology
- Injection molding
- Blow molding
- Thermoforming
- End-user
- Food and beverage
- Cosmetics
- Pharmaceuticals
- Others
- Material
- Polypropylene
- Polyethylene
- Polyvinyl chloride
- Acrylonitrile butadiene styrene
- Others
- Geography
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- North America
- US
- Canada
- Mexico
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Turkey
- South America
- Brazil
- Argentina
- Chile
- Europe
By Technology Insights
The injection molding segment is estimated to witness significant growth during the forecast period.
The injection molding process dominates the In Mold Labelling Market by seamlessly fusing pre-printed labels with container walls during the polymer injection phase.
This monolithic integration guarantees superior dimensional stability and structural rigidity, essential for rigid food containers and industrial pails. Businesses adopting these advanced methods report a 15% improvement in defect detection rates compared to post-production labeling techniques.
The single-step manufacturing nature drastically reduces assembly time and optimizes supply chain efficiency for brand owners. Although establishing dedicated lines equipped with robotic handling systems requires substantial initial investment, modern high cavitation production presses maximize throughput to offset these costs.
Continuous refinement in robotic speeds and the expansion of thin wall packaging applications ensure this segment remains foundational to modern container decoration strategies.
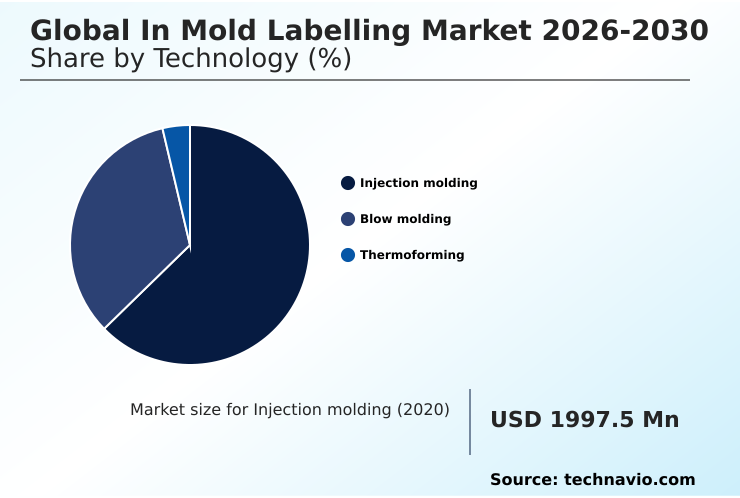
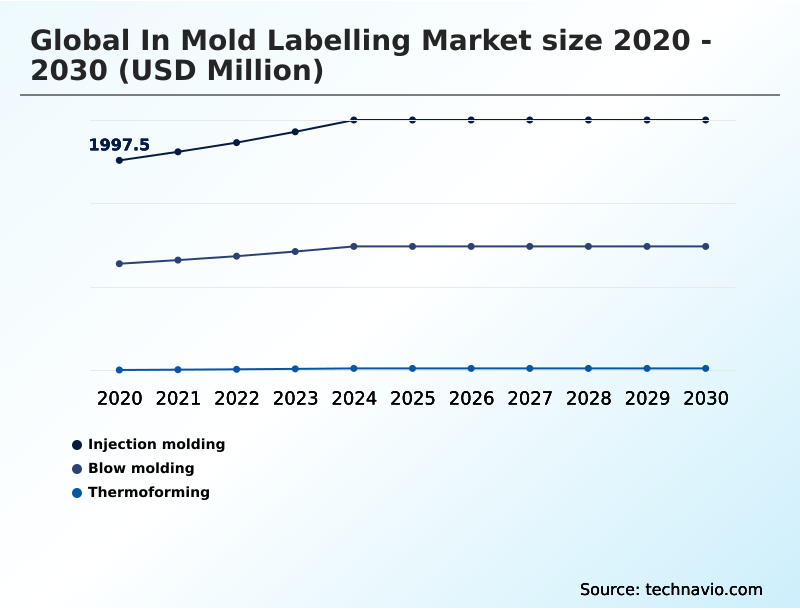
The Injection molding segment was valued at USD 2.36 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
Europe is estimated to contribute 48.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
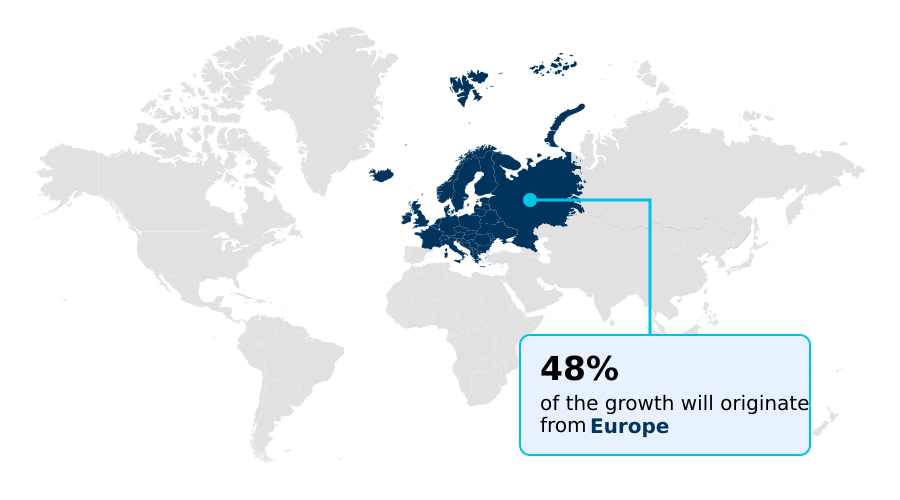
See How In Mold Labelling Market Demand is Rising in Europe Get Free Sample
The geographic landscape of the In Mold Labelling Market highlights a stark contrast in adoption maturity between Europe and North America.
Driven by comprehensive circular economy mandates, Europe commands a significant operational advantage, where regional converters have achieved a 30% reduction in post-industrial adhesive waste by universally adopting mono material structures.
In contrast, North America displays a more gradual transition, balancing high initial automation costs with an emerging demand for post consumer recycled substrates.
European facilities utilizing advanced robotic automation cells report a 22% higher throughput efficiency compared to standard North American molding operations.
This disparity stems from Europe's strict regulatory frameworks that financially penalize non-recyclable packaging formats, compelling a rapid shift toward seamlessly integrated thermoplastic films.
As North American sustainable packaging compliance standards tighten, supply chain managers are increasingly adopting high cavitation production presses to bridge the efficiency gap and align with global closed loop economic systems.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The operational dynamics of the In Mold Labelling Market are continuously reshaped by the demand for streamlined manufacturing and ecologically viable packaging. A critical development in this sector is the widespread adoption of injection molded rigid plastic packaging, which offers unparalleled structural integrity and shelf appeal for consumer goods.
- To meet stringent environmental targets, industry leaders are prioritizing mono material polypropylene container recycling, ensuring that both the container and its label can be processed together without the need for manual separation. This seamless integration provides a 25% improvement in recycling throughput efficiency compared to formats requiring adhesive removal.
- Furthermore, the modern supply chain is increasingly reliant on rfid enabled smart packaging solutions, allowing brand owners to execute real-time inventory tracking and advanced anti counterfeiting measures directly from the production line. Executing these complex designs requires highly precise automated robotic label placement systems that can accurately position graphics within milliseconds before polymer injection occurs.
- When combined with high barrier label film integration, the resulting packaging exhibits superior chemical resistance and durability during cold chain logistics. By completely eliminating secondary decoration steps, manufacturers effectively reduce operational downtime and minimize raw material waste.
- This transition underscores a fundamental shift in packaging strategy, where sustainability and digital traceability are integrated at the foundation of the manufacturing process to secure long-term operational resilience and brand equity.
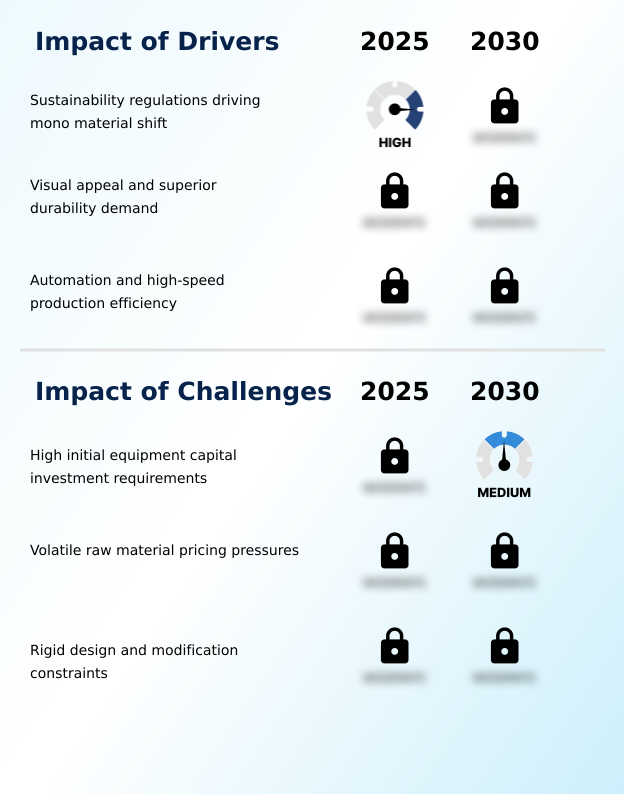
What are the key market drivers leading to the rise in the adoption of In Mold Labelling Industry?
- Strict sustainability regulations driving the transition toward mono material structures serve as a primary catalyst accelerating market expansion.
- Stringent governmental regulations targeting plastic waste reduction act as the primary catalyst propelling the In Mold Labelling Market.
- Legislative bodies are enforcing circular economy mandates that heavily penalize multi-material packaging waste, compelling fast-moving consumer goods corporations to transition toward mono material structures.
- By utilizing highly compatible polyethylene resins for both the label and the container base, manufacturers guarantee seamless processing within existing mechanical recycling infrastructure.
- Operations transitioning to these single-material formats report a 35% decrease in post-industrial adhesive waste and have lowered overall energy use by 12% by eliminating secondary heating and curing stages.
- This operational streamlining directly enables brand owners to meet aggressive corporate sustainability targets while maintaining the structural integrity required for demanding retail environments.
What are the market trends shaping the In Mold Labelling Industry?
- Sustainable packaging mandates driving adoption constitutes a prominent trend shaping the industry landscape. This shift compels manufacturers to integrate eco-friendly materials that align with rigorous environmental compliance standards.
- The transition toward intelligent and interactive packaging constitutes a dominant trend continuously reshaping the In Mold Labelling Market across diverse consumer sectors. Manufacturers are rapidly integrating supply chain transparency tools, such as embedded tracking chips and serialized codes, directly into the packaging substrate during the blow molding technology phase.
- This structural innovation has allowed logistics managers to improve inventory forecast accuracy by 18% while simultaneously deploying robust anti counterfeiting measures. By utilizing high resolution digital printing on thermoplastic films, brands can deliver intricate, tamper evident seals without requiring secondary application steps.
- Consequently, packaging facilities implementing these advanced digital features have reduced operational downtime by 24% compared to traditional secondary labeling lines. This technological shift empowers businesses to deliver verifiable product authenticity to end-users while streamlining manufacturing workflows.
What challenges does the In Mold Labelling Industry face during its growth?
- High initial equipment capital investment requirements represent a significant operational barrier constraining broader industry adoption.
- The substantial capital expenditures required for specialized machinery pose a significant barrier to entry within the In Mold Labelling Market. Unlike conventional labeling methods, this technology necessitates full integration with molding hardware, requiring expensive robotic handling systems and precision custom mold cavities.
- Small and medium-sized enterprises frequently lack the budgetary capacity to acquire these advanced robotic automation cells, which can increase initial facility setup costs by up to 40%. Furthermore, integrating these sophisticated components into existing thermoformed plastic containers production lines often leads to temporary operational disruptions, with transition phases temporarily reducing output efficiency by 15%.
- The intricate synchronization required between label insertion and the polymer injection cycle demands highly skilled engineering oversight, compounding ongoing maintenance expenditures for localized packaging converters.
Exclusive Technavio Analysis on Customer Landscape
The in mold labelling market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the in mold labelling market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
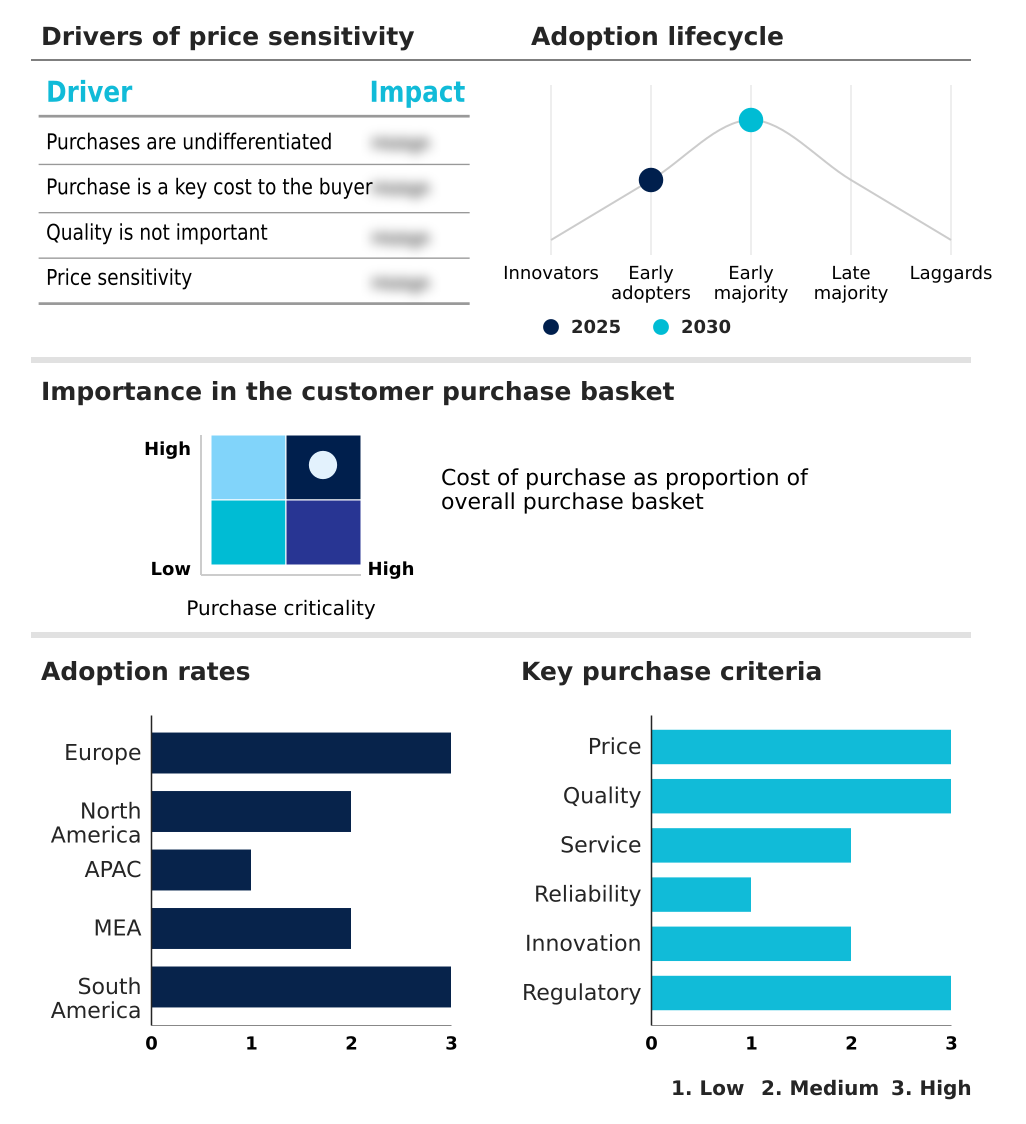
Customer Landscape of In Mold Labelling Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, in mold labelling market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Amcor Plc - The firm provides advanced in mold labelling solutions including decorated and lightweight packaging configurations designed to enhance product durability and visual appeal across consumer goods sectors.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Amcor Plc
- CCL Label
- Constantia Flexibles GmbH
- Coveris Management GmbH
- Double H Plastics Inc.
- EVCO Plastics
- Fuji Seal International Inc.
- Greiner Packaging International
- Huhtamaki Oyj
- Inland Label and Marketing Service
- ITC Packaging
- Leaderform Group
- Mold Tek Packaging Ltd.
- Multi Color Corp.
- Nissha Metallizing Solutions
- Plastmore
- Purity Flexpack Ltd
- Sonoco Products Co.
- Taghleef Industries SpA
- Winpak Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in In mold labelling market
- In the Metal, Glass and Plastic Containers industry, the implementation of stringent circular economy mandates across Europe has accelerated the transition toward mono material structures, directly impacting In Mold Labelling demand by prioritizing labels that share identical polymer composition with their base substrates.
- The shift toward advanced robotic automation cells in rigid packaging manufacturing has reduced operational downtime by 20%, enhancing the precision of thermoplastic films placement and accelerating the adoption of integrated labeling techniques over traditional secondary adhesives.
- Surging requirements for supply chain transparency in consumer goods packaging have driven the integration of anti counterfeiting measures and inventory tracking features into plastic containers, propelling the use of smart labels embedded directly during the blow molding technology phase.
- Advancements in post consumer recycled substrates for commercial packaging have required the development of highly compatible decoration methods, fueling the expansion of In Mold Labelling as a preferred solution to maintain mechanical recycling infrastructure integrity without risking chemical contamination.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled In Mold Labelling Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 301 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 4.8% |
| Market growth 2026-2030 | USD 1020.9 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 4.6% |
| Key countries | Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The In Mold Labelling Market undergoes continuous transformation as structural packaging demands intersect with rigorous environmental compliance strategies. Boardroom executives are increasingly prioritizing sustainable packaging compliance by migrating toward mono material structures, a strategic product decision that safeguards brand equity against tightening regulatory penalties.
- This material alignment heavily utilizes polypropylene substrates to ensure both the label and container can be processed seamlessly through existing mechanical recycling infrastructure. Facilities transitioning to these integrated thermoplastic films have achieved a 30% reduction in secondary processing time by eliminating post-mold adhesive applications.
- Furthermore, the deployment of robotic handling systems within high cavitation production presses ensures flawless graphic positioning and superior tactile finishes without sacrificing production velocity. The strategic integration of advanced robotic automation cells allows converters to mitigate raw material price volatility and reduce energy consumption during high-speed manufacturing runs.
- As the industry pivots away from conventional shrink sleeve alternatives, the reliance on high resolution digital printing ensures that complex branding and essential nutritional information remain intact throughout rigorous cold chain logistics and extensive retail displays.
What are the Key Data Covered in this In Mold Labelling Market Research and Growth Report?
-
What is the expected growth of the In Mold Labelling Market between 2026 and 2030?
-
USD 1.02 billion, at a CAGR of 4.8%
-
-
What segmentation does the market report cover?
-
The report is segmented by Technology (Injection molding, Blow molding, and Thermoforming), End-user (Food and beverage, Cosmetics, Pharmaceuticals, and Others), Material (Polypropylene, Polyethylene, Polyvinyl chloride, Acrylonitrile butadiene styrene, and Others) and Geography (Europe, North America, APAC, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
Europe, North America, APAC, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Sustainability regulations driving mono material shift, High initial equipment capital investment requirements
-
-
Who are the major players in the In Mold Labelling Market?
-
Amcor Plc, CCL Label, Constantia Flexibles GmbH, Coveris Management GmbH, Double H Plastics Inc., EVCO Plastics, Fuji Seal International Inc., Greiner Packaging International, Huhtamaki Oyj, Inland Label and Marketing Service, ITC Packaging, Leaderform Group, Mold Tek Packaging Ltd., Multi Color Corp., Nissha Metallizing Solutions, Plastmore, Purity Flexpack Ltd, Sonoco Products Co., Taghleef Industries SpA and Winpak Ltd.
-
Market Research Insights
- The In Mold Labelling Market is rapidly evolving as fast-moving consumer goods sectors transition toward fully recyclable packaging formats to meet rigorous environmental sustainability policies. By utilizing highly compatible polypropylene substrates, manufacturers have achieved a 25% improvement in processing speeds compared to traditional pressure-sensitive alternatives.
- Furthermore, the integration of advanced inventory tracking features directly into the packaging structure has enhanced supply chain transparency, reducing logistical tracking errors by 18%. This shift supports closed loop economic systems by preventing adhesive contamination during the recycling wash cycle.
- As regulatory pressures intensify, brand owners are increasingly leveraging bio based plastic substrates to lower carbon footprints while maintaining superior graphic fidelity and structural integrity on retail shelves.
We can help! Our analysts can customize this in mold labelling market research report to meet your requirements.
 RIA -

