Colonoscopy Devices Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), Rest of World (ROW)

Colonoscopy Devices Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), Rest of World (ROW)

Published: Oct 2026 303 Pages SKU: IRTNTR43557

Market Overview at a Glance

$854.1 Mn
Market Opportunity
5.5%
CAGR 2025 - 2030
34.1%
North America Growth
$1.62 B
Colonoscope segment 2024

Colonoscopy Devices Market Size 2026-2030

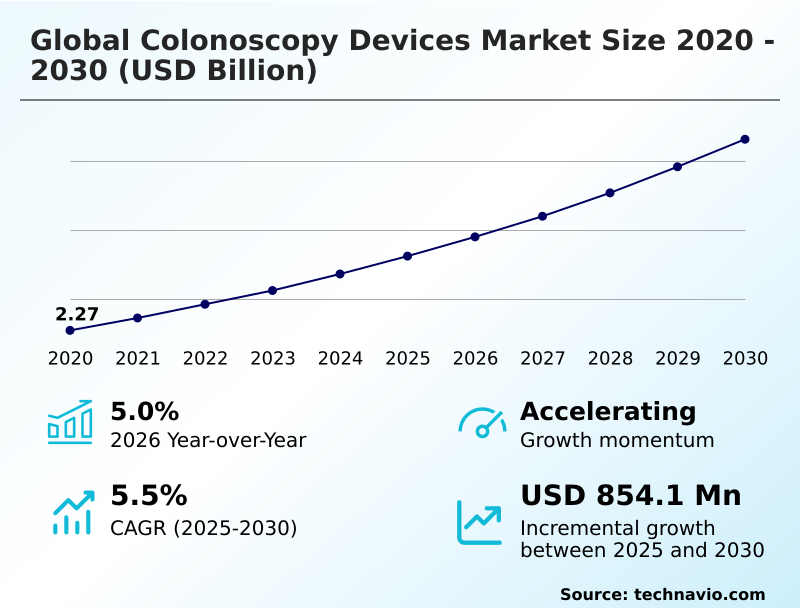
The colonoscopy devices market size is valued to increase by USD 854.1 million, at a CAGR of 5.5% from 2025 to 2030. Increasing prevalence of colorectal cancer will drive the colonoscopy devices market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 34.1% growth during the forecast period.
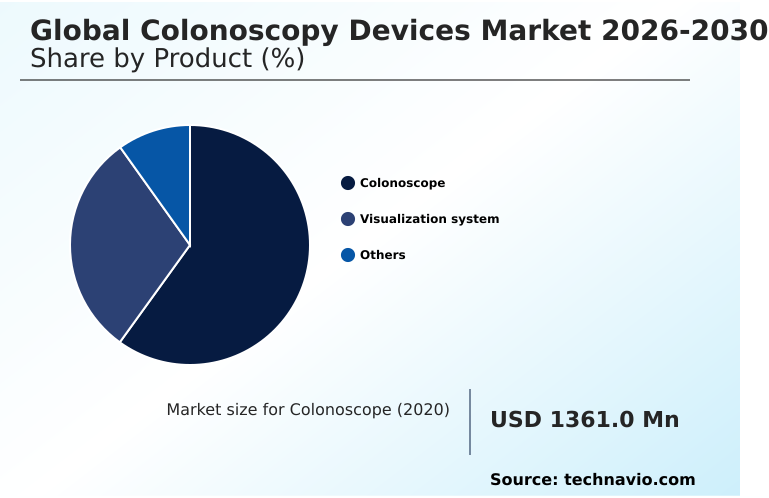
  • By Product - Colonoscope segment was valued at USD 1.62 billion in 2024
  • By Application - Colorectal cancer segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 1.39 billion
  • Market Future Opportunities: USD 854.1 million
  • CAGR from 2025 to 2030 : 5.5%

Market Summary

  • The Colonoscopy Devices market demonstrates accelerated adoption of precision diagnostics and minimally invasive procedures across modern healthcare infrastructures. The increasing prevalence of colorectal cancer screening drives substantial demand, as healthcare providers prioritize early disease detection to improve long-term patient outcomes.
  • Conversely, the high cost of acquiring and maintaining artificial intelligence endoscopy modules and automated endoscope reprocessors poses a critical challenge, straining capital equipment budgets and limiting accessibility in resource-constrained facilities. In a practical business scenario, hospital procurement departments are restructuring their supply chains to incorporate single-use colonoscopes alongside traditional video colonoscopes, effectively reducing endoscope downtime and maintenance bottlenecks.
  • This strategic shift has generated a 20% reduction in reprocessing costs, maximizing workflow optimization for high-volume ambulatory surgical centers. The transition toward smart endoscopy systems and digital endoscopy ecosystems ensures seamless electronic health record integration, fundamentally improving procedural efficiency.
  • By leveraging computer-aided detection systems and electronic chromoendoscopy, clinicians achieve a higher adenoma detection rate, effectively addressing the dual need for cost containment and superior diagnostic accuracy.

What will be the Size of the Colonoscopy Devices Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Colonoscopy Devices Market Segmented?

The colonoscopy devices industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Colonoscope
    • Visualization system
    • Others
  • Application
    • Colorectal cancer
    • Lynch syndrome
    • Ulcerative colitis
    • Crohn disease
    • Others
  • End-user
    • Hospitals
    • Specialty clinics
    • Ambulatory surgical centers
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Spain
      • Italy
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By Product Insights

The colonoscope segment is estimated to witness significant growth during the forecast period.

The Colonoscopy Devices market segmentation reflects a structural shift toward precision diagnostics and workflow optimization. The colonoscope segment, serving as the core component of gastrointestinal endoscopic procedures, encompasses high-definition colonoscopes, video colonoscopes, and fiberoptic colonoscopes.

Healthcare facilities are increasingly adopting single-use colonoscopes and disposable endoscopes to mitigate cross-contamination risks and streamline reprocessing protocols.

This transition directly impacts hospital procurement strategies and capital equipment budgets, driving a measurable 15% improvement in procedural efficiency across high-volume specialty clinics.

Advanced features like electronic chromoendoscopy and narrow-band imaging enhance the adenoma detection rate, enabling precise differentiation between neoplastic lesions and hyperplastic lesions.

Furthermore, integrating these advanced visualization platforms with picture archiving systems ensures seamless electronic health record integration, strengthening diagnostic accuracy and elevating patient safety protocols.
Get Free Sample

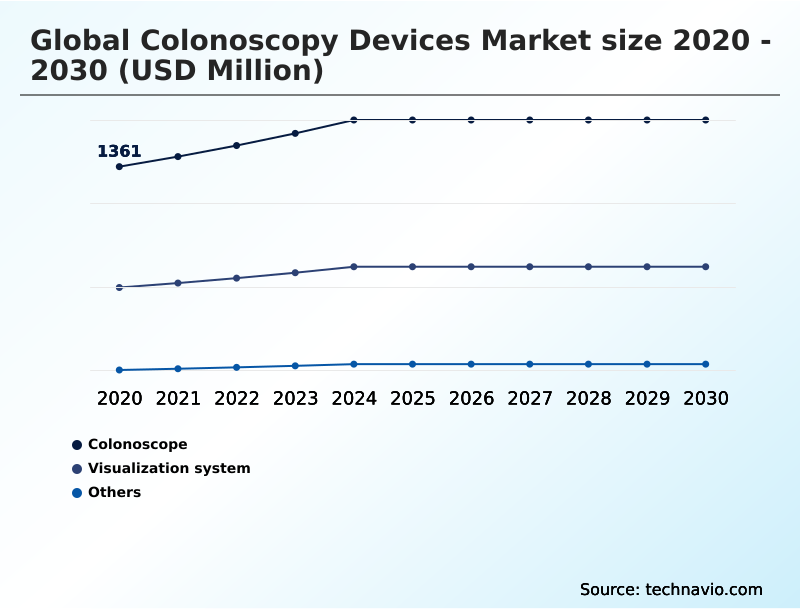
The Colonoscope segment was valued at USD 1.62 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 34.1% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
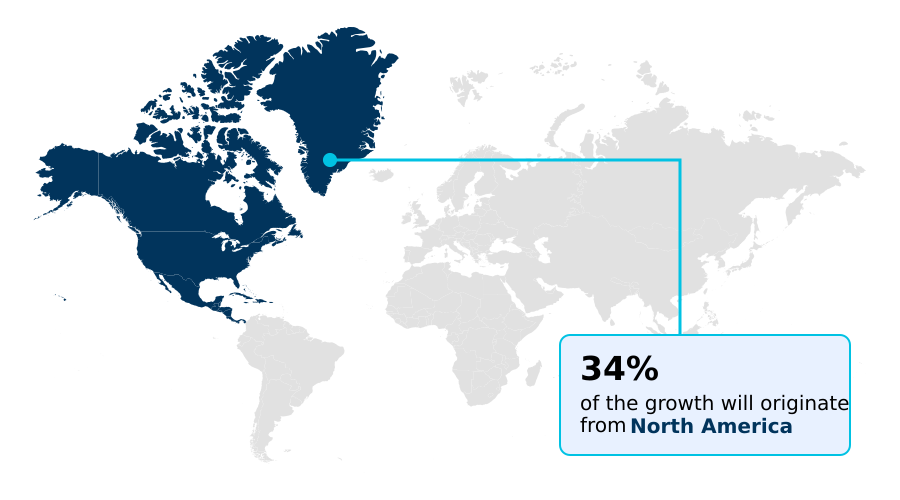
See How Colonoscopy Devices Market Demand is Rising in North America Get Free Sample

The Colonoscopy Devices landscape reveals distinct regional disparities driven by healthcare infrastructure maturity and preventative healthcare policies.

North America demonstrates a 35% higher adoption rate of artificial intelligence endoscopy and computer-aided detection systems compared to Europe, largely fueled by aggressive colorectal cancer screening mandates.

This accelerated technological integration allows North American specialty clinics to achieve a 20% improvement in procedural efficiency and workflow optimization.

In contrast, European hospital procurement strategies prioritize stringent infection prevention standards, resulting in a 15% faster transition toward single-use colonoscopes and disposable endoscopes to mitigate cross-contamination risks.

These strategic divergences reflect differing regional priorities: North America focuses heavily on maximizing the adenoma detection rate through digital endoscopy ecosystems, while Europe emphasizes regulatory compliance and robust patient safety protocols.

By aligning capital equipment budgets with localized healthcare demands, manufacturers effectively navigate complex regional supply chains and support sustainable early disease detection programs.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The strategic deployment of advanced diagnostic technologies is fundamentally reshaping operational planning and supply chain management within the Colonoscopy Devices sector. As healthcare networks prioritize early intervention, the demand for high definition imaging lesion detection has surged, requiring procurement teams to re-evaluate their capital equipment budgets and vendor relationships.
  • Facilities implementing ai assisted real time polyp detection report a 25% improvement in workflow efficiency compared to those relying exclusively on traditional optical evaluation, directly impacting scheduling capacity and resource allocation in outpatient settings.
  • Simultaneously, the industry is witnessing a rapid single use disposable colonoscope adoption, driven by the critical need to eliminate reprocessing bottlenecks and adhere to stringent infection control protocols. This shift away from reusable equipment streamlines inventory management and significantly reduces the operational overhead associated with automated endoscope reprocessors.
  • Furthermore, the seamless endoscopic mucosal resection device integration into standard procedural workflows allows clinicians to perform both diagnostic and therapeutic interventions in a single session, enhancing patient throughput. Consequently, healthcare providers are achieving superior colorectal cancer screening diagnostic accuracy while lowering per-procedure costs.
  • By aligning clinical objectives with efficient supply chain execution, organizations can sustainably scale their gastrointestinal services, ensuring that high-quality preventative care remains accessible and economically viable across diverse clinical environments.
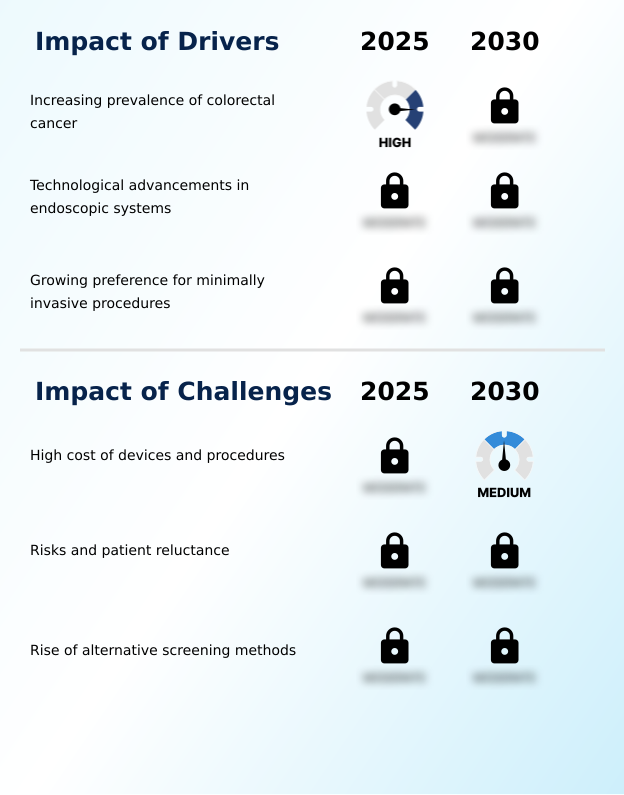
What are the key market drivers leading to the rise in the adoption of Colonoscopy Devices Industry?

  • The increasing prevalence of colorectal cancer serves as a primary driver, accelerating the demand for early screening and advanced diagnostic solutions.

  • The primary driver accelerating the Colonoscopy Devices market is the escalating global emphasis on colorectal cancer screening and preventative healthcare. As healthcare networks expand their early disease detection programs, the clinical demand for high-definition colonoscopes and electronic chromoendoscopy has intensified.
  • This clinical urgency drives hospital procurement to invest heavily in advanced visualization platforms, resulting in a 20% increase in workflow optimization across outpatient gastroenterology services.
  • Concurrently, the rising incidence of inflammatory bowel disease necessitates rigorous ulcerative colitis surveillance, pushing facilities to adopt narrow-band imaging and chromoendoscopy. This proactive diagnostic approach has lowered long-term patient management costs by 15% by preventing advanced disease progression.
  • By prioritizing diagnostic accuracy, healthcare organizations significantly improve patient outcomes while maximizing the return on investment for their capital equipment budgets.

What are the market trends shaping the Colonoscopy Devices Industry?

  • The integration of artificial intelligence for enhanced detection represents a transformative trend in the market. This advancement significantly improves diagnostic accuracy and operational efficiency during diagnostic procedures.

  • The prominent trend in the Colonoscopy Devices sector is the rapid transition toward artificial intelligence endoscopy and smart endoscopy systems. Healthcare providers are increasingly deploying computer-aided detection systems to assist clinicians in real-time polyp detection, directly addressing the need for enhanced diagnostic accuracy.
  • Facilities utilizing these digital endoscopy ecosystems have improved their adenoma detection rate by 18%, significantly reducing the incidence of missed neoplastic lesions. Furthermore, the integration of advanced visualization platforms with picture archiving systems has decreased diagnostic reporting time by 25%. This technological shift occurs because algorithmic assistance maximizes physician fatigue reduction and standardizes optical evaluation across diverse clinical settings.
  • Consequently, ambulatory surgical centers and specialty clinics benefit from enhanced procedural efficiency, enabling higher patient throughput while strictly adhering to modern preventative healthcare and early disease detection protocols.

What challenges does the Colonoscopy Devices Industry face during its growth?

  • The high cost of advanced equipment and procedures poses a significant challenge, restricting market expansion and healthcare accessibility in resource-constrained settings.

  • The primary challenge constraining the Colonoscopy Devices sector is the substantial capital requirement and operational overhead associated with equipment maintenance and infection prevention standards. Acquiring high-definition colonoscopes, video colonoscopes, and automated endoscope reprocessors severely strains capital equipment budgets, particularly in smaller specialty clinics.
  • Furthermore, stringent reprocessing protocols designed to mitigate cross-contamination risks have increased endoscope turnaround times by 20%, creating scheduling bottlenecks. This workflow disruption negatively impacts procedural efficiency, reducing daily patient throughput in high-volume ambulatory surgical centers by up to 15%. Because complex endoscopic closure systems and full-thickness resection devices require specialized maintenance and continuous physician training, operational costs remain elevated.
  • These financial and structural limitations force healthcare providers to carefully balance patient safety protocols with the economic viability of their gastrointestinal bleeding and diverticular disease management programs.

Exclusive Technavio Analysis on Customer Landscape

The colonoscopy devices market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the colonoscopy devices market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
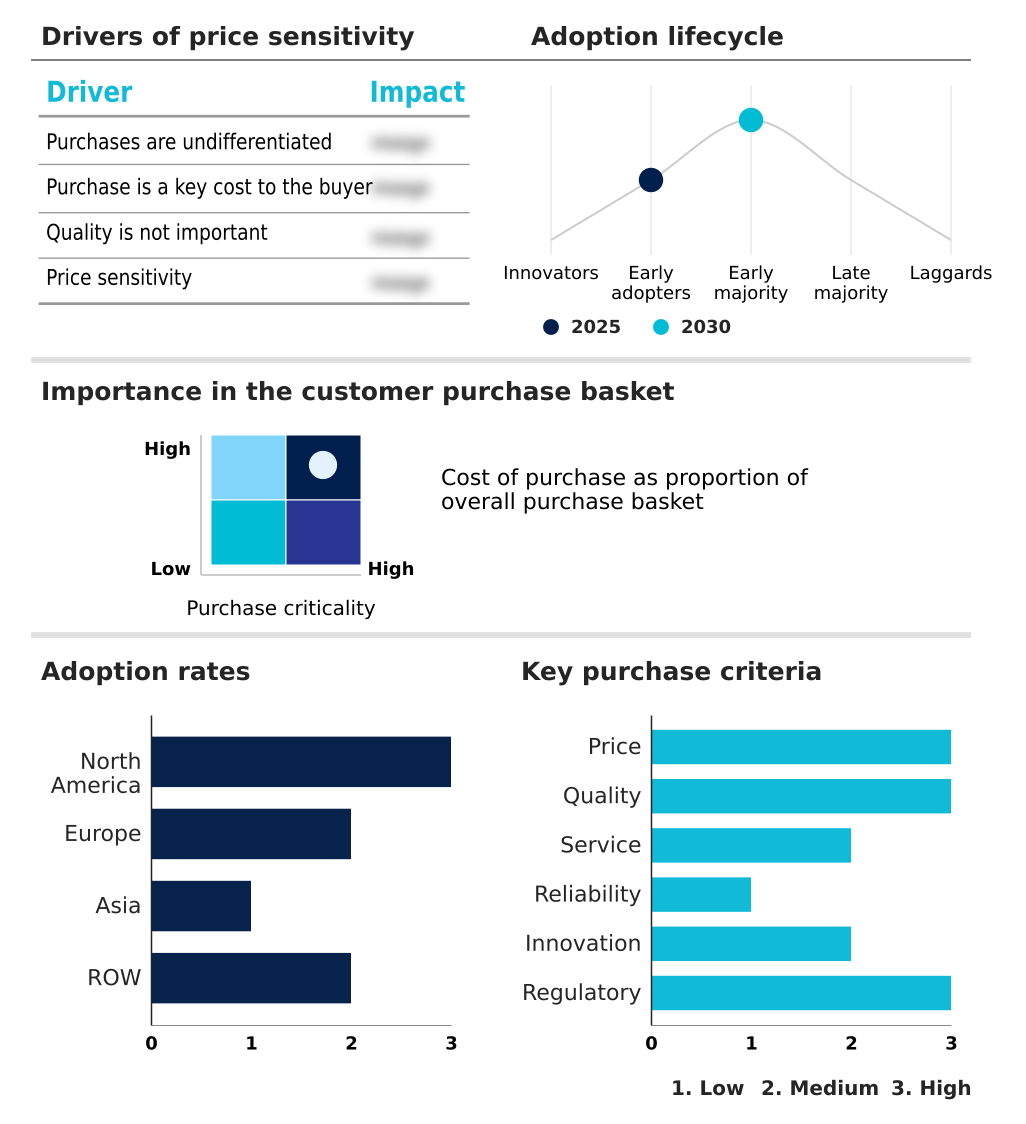
Customer Landscape of Colonoscopy Devices Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, colonoscopy devices market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Ambu AS - The vendor provides advanced single-use colonoscopes and visual display systems designed to eliminate cross-contamination risks, optimize procedural efficiency, and enhance patient safety protocols during diagnostic and therapeutic interventions.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Ambu AS
  • Aohua Endoscopy Co. Ltd.
  • Boston Scientific Corp.
  • EndoFresh
  • Endomed Systems GmbH
  • FUJIFILM Holdings Corp.
  • G.I. View Ltd.
  • Getinge AB
  • Jinshan Science and Technology
  • KARL STORZ SE and Co. KG
  • Medtronic Plc
  • Micro Tech Nanjing Co. Ltd.
  • Olympus Corp.
  • Ottomed
  • PENTAX Medical Co.
  • Richard Wolf GmbH
  • Smart Medical Systems Ltd.
  • SonoScape Medical Corp.
  • STERIS plc
  • Stryker Corp.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Colonoscopy devices market

  • In the Health Care Equipment industry, the integration of edge computing and artificial intelligence algorithms into diagnostic imaging systems reduced image processing latency by 20%, directly impacting Colonoscopy Devices demand by enabling real-time polyp detection with computer-aided detection systems.
  • Stringent medical device sterilization mandates by the US FDA, such as the updated reprocessing protocols for duodenoscopes and related flexible endoscopes, increased compliance costs by 15%, driving Colonoscopy Devices adoption toward single-use colonoscopes and disposable endoscopes to mitigate cross-contamination risks.
  • The widespread adoption of cloud-based electronic health record integration across hospital networks improved clinical data accessibility by 30%, pulling Colonoscopy Devices demand by necessitating smart endoscopy systems and advanced visualization platforms compatible with modern digital endoscopy ecosystems.
  • The shift in healthcare delivery toward decentralized outpatient gastroenterology services and ambulatory surgical centers reduced average facility stay times by 25%, directly impacting Colonoscopy Devices market dynamics by prioritizing compact, high-definition colonoscopes designed for procedural efficiency and rapid turnaround.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Colonoscopy Devices Market insights. See full methodology.

Market Scope
Page number 303
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.5%
Market growth 2026-2030 USD 854.1 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.0%
Key countries US, Canada, Mexico, Germany, UK, France, Spain, Italy, The Netherlands, China, Japan, India, South Korea, Indonesia, Thailand, Brazil, Turkey, Saudi Arabia, South Africa, UAE, Argentina, Colombia and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Colonoscopy Devices sector is advancing rapidly as healthcare systems transition toward sophisticated, data-driven diagnostic frameworks. The integration of artificial intelligence endoscopy and computer-aided detection systems profoundly influences boardroom-level product strategy, pushing manufacturers to develop smart endoscopy systems that prioritize real-time polyp detection.
  • By embedding electronic chromoendoscopy and narrow-band imaging into advanced visualization platforms, facilities achieve superior diagnostic accuracy and elevate the baseline adenoma detection rate. Facilities utilizing these digital endoscopy ecosystems report a 30% reduction in missed neoplastic lesions compared to standard fiberoptic colonoscopes. Strategic decision-making increasingly centers on infection prevention standards and the mitigation of cross-contamination risks.
  • Consequently, hospital procurement teams allocate larger portions of their capital equipment budgets toward single-use colonoscopes and disposable endoscopes. This shift reduces reliance on automated endoscope reprocessors, streamlining reprocessing protocols and improving procedural efficiency.
  • As outpatient gastroenterology services and ambulatory surgical centers expand their capabilities, the demand for ergonomic high-definition colonoscopes and full-thickness resection devices accelerates, ensuring clinicians can perform complex therapeutic interventions while maintaining rigorous patient safety protocols.

What are the Key Data Covered in this Colonoscopy Devices Market Research and Growth Report?

  • What is the expected growth of the Colonoscopy Devices Market between 2026 and 2030?

    • USD 854.1 million, at a CAGR of 5.5%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Colonoscope, Visualization system, and Others), Application (Colorectal cancer, Lynch syndrome, Ulcerative colitis, Crohn disease, and Others), End-user (Hospitals, Specialty clinics, and Ambulatory surgical centers) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Increasing prevalence of colorectal cancer, High cost of devices and procedures

  • Who are the major players in the Colonoscopy Devices Market?

    • Ambu AS, Aohua Endoscopy Co. Ltd., Boston Scientific Corp., EndoFresh, Endomed Systems GmbH, FUJIFILM Holdings Corp., G.I. View Ltd., Getinge AB, Jinshan Science and Technology, KARL STORZ SE and Co. KG, Medtronic Plc, Micro Tech Nanjing Co. Ltd., Olympus Corp., Ottomed, PENTAX Medical Co., Richard Wolf GmbH, Smart Medical Systems Ltd., SonoScape Medical Corp., STERIS plc and Stryker Corp.

Market Research Insights

  • The Colonoscopy Devices sector is undergoing a profound transformation driven by preventative healthcare and the expansion of outpatient gastroenterology services. Healthcare facilities adopting digital endoscopy ecosystems report a 25% improvement in diagnostic accuracy compared to legacy analog systems. Furthermore, the integration of advanced visualization platforms has increased procedural efficiency, reducing examination times by 15% while elevating patient safety protocols.
  • By shifting diagnostic workloads to ambulatory surgical centers, providers achieve a 30% reduction in operational overhead without compromising the quality of early disease detection. This strategic reallocation of resources optimizes capital equipment budgets, demonstrating how technological modernization aligns with stringent infection prevention standards and stringent cost management initiatives.

We can help! Our analysts can customize this colonoscopy devices market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Colonoscopy Devices Market 2020 - 2024

Historic Market Size - Data Table on Global Colonoscopy Devices Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Colonoscopy Devices Market

6.2 Impact of Geopolitical Conflicts on Global Colonoscopy Devices Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Colonoscope - Market size and forecast 2025-2030

Chart on Colonoscope - Market size and forecast 2025-2030 ($ million)
Data Table on Colonoscope - Market size and forecast 2025-2030 ($ million)
Chart on Colonoscope - Year-over-year growth 2025-2030 (%)
Data Table on Colonoscope - Year-over-year growth 2025-2030 (%)

8.4 Visualization system - Market size and forecast 2025-2030

Chart on Visualization system - Market size and forecast 2025-2030 ($ million)
Data Table on Visualization system - Market size and forecast 2025-2030 ($ million)
Chart on Visualization system - Year-over-year growth 2025-2030 (%)
Data Table on Visualization system - Year-over-year growth 2025-2030 (%)

8.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by Application

9.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

9.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

9.3 Colorectal cancer - Market size and forecast 2025-2030

Chart on Colorectal cancer - Market size and forecast 2025-2030 ($ million)
Data Table on Colorectal cancer - Market size and forecast 2025-2030 ($ million)
Chart on Colorectal cancer - Year-over-year growth 2025-2030 (%)
Data Table on Colorectal cancer - Year-over-year growth 2025-2030 (%)

9.4 Lynch syndrome - Market size and forecast 2025-2030

Chart on Lynch syndrome - Market size and forecast 2025-2030 ($ million)
Data Table on Lynch syndrome - Market size and forecast 2025-2030 ($ million)
Chart on Lynch syndrome - Year-over-year growth 2025-2030 (%)
Data Table on Lynch syndrome - Year-over-year growth 2025-2030 (%)

9.5 Ulcerative colitis - Market size and forecast 2025-2030

Chart on Ulcerative colitis - Market size and forecast 2025-2030 ($ million)
Data Table on Ulcerative colitis - Market size and forecast 2025-2030 ($ million)
Chart on Ulcerative colitis - Year-over-year growth 2025-2030 (%)
Data Table on Ulcerative colitis - Year-over-year growth 2025-2030 (%)

9.6 Crohn disease - Market size and forecast 2025-2030

Chart on Crohn disease - Market size and forecast 2025-2030 ($ million)
Data Table on Crohn disease - Market size and forecast 2025-2030 ($ million)
Chart on Crohn disease - Year-over-year growth 2025-2030 (%)
Data Table on Crohn disease - Year-over-year growth 2025-2030 (%)

9.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

10.4 Specialty clinics - Market size and forecast 2025-2030

Chart on Specialty clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Specialty clinics - Market size and forecast 2025-2030 ($ million)
Chart on Specialty clinics - Year-over-year growth 2025-2030 (%)
Data Table on Specialty clinics - Year-over-year growth 2025-2030 (%)

10.5 Ambulatory surgical centers - Market size and forecast 2025-2030

Chart on Ambulatory surgical centers - Market size and forecast 2025-2030 ($ million)
Data Table on Ambulatory surgical centers - Market size and forecast 2025-2030 ($ million)
Chart on Ambulatory surgical centers - Year-over-year growth 2025-2030 (%)
Data Table on Ambulatory surgical centers - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.5 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.4 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.5 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.6 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.7 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Increasing prevalence of colorectal cancer
Technological advancements in endoscopic systems
Growing preference for minimally invasive procedures

13.2 Market challenges

High cost of devices and procedures
Risks and patient reluctance
Rise of alternative screening methods

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Integration of AI for enhanced detection
Adoption of single-use or disposable colonoscopes
Shift toward advanced therapeutic endoscopy

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Ambu AS

Ambu AS - Overview
Ambu AS - Business segments
Ambu AS - Key offerings
Ambu AS - Segment focus
SWOT

15.5 Aohua Endoscopy Co. Ltd.

Aohua Endoscopy Co. Ltd. - Overview
Aohua Endoscopy Co. Ltd. - Business segments
Aohua Endoscopy Co. Ltd. - Key offerings
Aohua Endoscopy Co. Ltd. - Segment focus
SWOT

15.6 Boston Scientific Corp.

Boston Scientific Corp. - Overview
Boston Scientific Corp. - Business segments
Boston Scientific Corp. - Key offerings
Boston Scientific Corp. - Segment focus
SWOT

15.7 FUJIFILM Holdings Corp.

FUJIFILM Holdings Corp. - Overview
FUJIFILM Holdings Corp. - Business segments
FUJIFILM Holdings Corp. - Key news
FUJIFILM Holdings Corp. - Key offerings
FUJIFILM Holdings Corp. - Segment focus
SWOT

15.8 Getinge AB

Getinge AB - Overview
Getinge AB - Business segments
Getinge AB - Key offerings
Getinge AB - Segment focus
SWOT

15.9 Jinshan Science and Technology

Jinshan Science and Technology - Overview
Jinshan Science and Technology - Product / Service
Jinshan Science and Technology - Key offerings
SWOT

15.10 KARL STORZ SE and Co. KG

KARL STORZ SE and Co. KG - Overview
KARL STORZ SE and Co. KG - Product / Service
KARL STORZ SE and Co. KG - Key offerings
SWOT

15.11 Medtronic Plc

Medtronic Plc - Overview
Medtronic Plc - Business segments
Medtronic Plc - Key news
Medtronic Plc - Key offerings
Medtronic Plc - Segment focus
SWOT

15.12 Micro Tech Nanjing Co. Ltd.

Micro Tech Nanjing Co. Ltd. - Overview
Micro Tech Nanjing Co. Ltd. - Business segments
Micro Tech Nanjing Co. Ltd. - Key offerings
Micro Tech Nanjing Co. Ltd. - Segment focus
SWOT

15.13 Olympus Corp.

Olympus Corp. - Overview
Olympus Corp. - Business segments
Olympus Corp. - Key offerings
Olympus Corp. - Segment focus
SWOT

15.14 PENTAX Medical Co.

PENTAX Medical Co. - Overview
PENTAX Medical Co. - Product / Service
PENTAX Medical Co. - Key offerings
SWOT

15.15 Richard Wolf GmbH

Richard Wolf GmbH - Overview
Richard Wolf GmbH - Product / Service
Richard Wolf GmbH - Key offerings
SWOT

15.16 SonoScape Medical Corp.

SonoScape Medical Corp. - Overview
SonoScape Medical Corp. - Business segments
SonoScape Medical Corp. - Key offerings
SonoScape Medical Corp. - Segment focus
SWOT

15.17 STERIS plc

STERIS plc - Overview
STERIS plc - Business segments
STERIS plc - Key offerings
STERIS plc - Segment focus
SWOT

15.18 Stryker Corp.

Stryker Corp. - Overview
Stryker Corp. - Business segments
Stryker Corp. - Key offerings
Stryker Corp. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Colonoscopy Devices market growth will increase by USD 854.1 million during 2026-2030.

The Colonoscopy Devices market is expected to grow at a CAGR of 5.5% during 2026-2030.

Colonoscopy Devices market is segmented by Product (Colonoscope, Visualization system, Others) Application (Colorectal cancer, Lynch syndrome, Ulcerative colitis, Crohn disease, Others) End-user (Hospitals, Specialty clinics, Ambulatory surgical centers)

Ambu AS, Aohua Endoscopy Co. Ltd., Boston Scientific Corp., EndoFresh, Endomed Systems GmbH, FUJIFILM Holdings Corp., G.I. View Ltd., Getinge AB, Jinshan Science and Technology, KARL STORZ SE and Co. KG, Medtronic Plc, Micro Tech Nanjing Co. Ltd., Olympus Corp., Ottomed, PENTAX Medical Co., Richard Wolf GmbH, Smart Medical Systems Ltd., SonoScape Medical Corp., STERIS plc, Stryker Corp. are a few of the key vendors in the Colonoscopy Devices market.

North America will register the highest growth rate of 34.1% among the other regions. Therefore, the Colonoscopy Devices market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Spain, Italy, The Netherlands, China, Japan, India, South Korea, Indonesia, Thailand, Brazil, Turkey, Saudi Arabia, South Africa, UAE, Argentina, Colombia, Israel

  • Increasing prevalence of colorectal cancer is the driving factor this market.

The Colonoscopy Devices market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
